
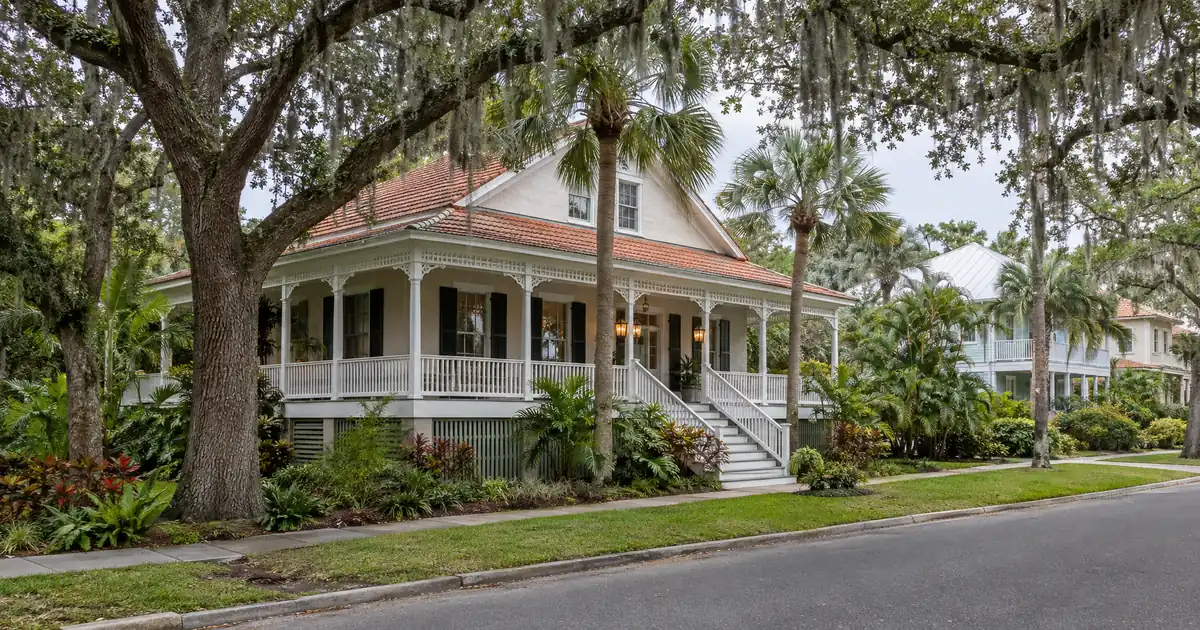
Picture an investor holding a duplex pair purchased a few years back in the Imperial River Corridor, just south of Downtown Bonita Springs, for somewhere in the mid-$500,000s. The units have been leased continuously to a mix of retirees and Herc Rentals corporate transferees ever since. Appraised value has since climbed into the $650,000 range, and the investor is sitting on equity that’s doing nothing but appreciating on paper. The question isn’t whether to refinance — it’s how much of that equity can actually convert to deployable capital without breaking the deal’s cash flow.
The Quick Read: A cash-out refinance on a Bonita Springs investment property is underwritten primarily on the property’s rental income measured against its full monthly obligation, capped at 75 percent loan-to-value under standard program guidelines, with roughly six months of seasoning required before the appraisal-based payoff can proceed.
DSCR Cash-Out Calculator
Run the cash-out numbers in Bonita Springs, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 17, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 17, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Florida cash-out LTV caps near 70 percent, below the 75 percent ceiling used elsewhere.
- Seasoning runs about six months from the title recording date before a cash-out refinance can close.
- Inland duplex pairs near $375,000-$650,000 often clear better coverage math than beach-corridor single-family homes.
- Coastal zip 34134 shows average prices near $740,000, down 24.5 percent year over year — appreciation cooling, not disappearing.
- Herc Rentals’ roughly 420-employee Field Support Center anchors a corporate tenant pool most Southwest Florida markets this size don’t have.
Bonita Springs Market Snapshot
A quick read on the Bonita Springs investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $589K median (Redfin Housing Market) |
| Typical rents | $2,213 median (Redfin Rental Market) |
| Population | 55,904 population (Census Reporter) |
| Employment | 9,600 employees (2025) (Wikipedia: Herc Rentals) |
| Vacancy | 32.3% (NeighborhoodScout) |
The Imperial River Corridor Is Where the Refinance Math Actually Works
The strongest cash-out candidates in Bonita Springs sit inland, along the Imperial River Corridor and the East Bonita/Morton Avenue pocket — not on the beach. Local multi-family listing data identifies these as the areas with “high rental demand from professionals and retirees” and “affordable duplex opportunities with reliable long-term tenants,” per DuplexForSale.com’s Bonita Springs market breakdown.
That distinction matters because Bonita Springs’ housing stock skews overwhelmingly toward detached single-family product — roughly 96 percent, by one MLS-aggregator estimate, against just 1 percent duplex share. Multi-unit inventory is scarce, which means the handful of duplex-triplex properties that do trade tend to concentrate in these inland pockets rather than the gated coastal communities. Homes.com’s multi-family listing tracker shows Bonita Springs multi-family homes priced between $375,000 and $9,000,000, with 61 active listings and an average of 118 days on market — nearly identical hold time to the broader single-family market, meaning investors aren’t paying a liquidity penalty to access the lower entry point.
Run the numbers on a modeled scenario: a duplex pair appraised at $650,000 following a period of ownership, refinanced at Florida’s cash-out ceiling of roughly 70 percent LTV. Combined rent on two-bedroom units near the metro’s rental range — using Redfin’s rental market data showing a $2,213 average monthly rent citywide as a directional anchor — lands somewhere near $4,800 to $5,000 per month combined. Layering a full PITIA calculation (principal, interest, taxes near 0.91 percent of value annually, and insurance near 0.80 percent) against that rent produces a modeled coverage ratio in the low-1.2x range. That’s comfortably above the 1.00 DSCR floor most standard programs are built around, though the exact number moves with the appraisal, the actual lease terms, and current loan pricing — none of which are fixed inputs here. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Compare that to a single detached home purchased in the $460,000-$500,000 range and refinanced on the same terms. Using the city’s $2,213 average rent against a comparable PITIA structure, the modeled coverage ratio drops closer to the mid-0.7x range — below the 1.00 benchmark. That price-to-income gap is the entire argument for why duplex-pair product, scarce as it is here, deserves first look on any Bonita Springs cash-out file.
The 34134 vs. 34135 Split: Appreciation Story, Cash-Flow Story
Bonita Springs splits cleanly into two investment theses depending on which zip code an investor is standing in, and conflating them is the single most common mistake in underwriting this market. Coastal 34134 — home to Bonita Bay, Spanish Wells, and the beach corridor — is the appreciation play. Inland 34135 is the cash-flow play.
Redfin’s zip-level data for 34134 shows an average house price of $740,000, down 24.5 percent year over year — a sharp pullback that’s still working through the system after a run of new luxury supply. WCI’s Altaira high-rise, described as the company’s first new luxury condo tower in Bonita Springs in nearly a decade, is landing into that same segment alongside additional Lennar, Toll Brothers, and Pulte projects, per a SkyCoastal roundup of new construction. New supply entering a segment that’s already down double digits year over year is a signal worth tracking closely — it suggests coastal comps could stay volatile for a while, which matters directly for how confidently a post-seasoning cash-out appraisal can lean on recent 34134 sales.
Inland 34135 tells a different story. New land and construction inventory there lists at a median price near $500,000, per Redfin’s 34135 listings — a meaningfully lower basis than the coastal corridor, and the zip where rent-to-price ratios have the best odds of clearing DSCR thresholds on today’s rent rolls. The Zillow Home Value Index for the broader city puts the average home value at $504,875, down 4.6 percent over the past year with homes going to pending in around 88 days, per Zillow’s ZHVI data — a figure that sits well below Redfin’s reported $589,000 MLS median sale price for the same market. That spread between the two data sources is itself a reminder that “the median price in Bonita Springs” depends heavily on methodology; investors should treat any single number as directional rather than precise.
The stronger cash-out play right now is probably 34135 over 34134 for an investor prioritizing coverage ratio — though someone underwriting for long-run appreciation with a longer hold horizon could reasonably argue the coastal correction is exactly the entry point they’ve been waiting for. That’s a genuine judgment call, not a settled answer.
Why Herc Rentals’ Headquarters Changes the Tenant Math
Bonita Springs, a city of roughly 55,904 residents per the Census Reporter’s ACS 2024 five-year profile, is the global corporate headquarters of Herc Holdings — a Fortune 1000 equipment-rental company trading as NYSE: HRI. Herc Rentals’ Wikipedia entry puts revenue at $4.376 billion and companywide employee count near 9,600. That’s a national field workforce figure, not a local one — the number that matters for a rental thesis is the roughly 420 employees staffed at the Bonita Springs Field Support Center itself, per Herc’s own careers page.
Four hundred and twenty white-collar corporate jobs in a city this size is unusual. No other Lee or Collier County municipality of comparable population hosts a NYSE-listed headquarters at this scale. That creates a tenant pool most Southwest Florida markets don’t have: relocating and transferring corporate professionals layered on top of an already dominant retiree and seasonal population. Bonita Springs’ median age sits at 61.9 years, with 44.2 percent of residents 65 or older, according to Wikipedia’s citation of 2020 Census data — an outlier even by Florida retirement standards. Pair that with a $95,210 median household income, per Florida-Demographics.com, and the tenant base for a well-positioned inland rental skews toward stable, financially qualified renters rather than transient or price-sensitive tenants.
Regional healthcare employment reinforces that stability. Gulfshore Business’s coverage of an FGCU Regional Economic Research Institute study puts Lee Health at 16,506 regional employees, the largest single employer in the corridor, with NCH Healthcare System adding several thousand more on the Collier County side.
Working DSCR brokers see a recurring pattern in dual-demand markets like this one: files anchored to a single dominant corporate employer often carry stronger, more predictable rent rolls than files built around purely seasonal or tourist-driven demand, because corporate-transfer tenants tend to sign longer leases and turn over less. Coastal, seasonal-heavy submarkets like Pelican Landing typically show the opposite pattern — strong sticker prices but a vacancy profile that reflects second-home ownership rather than active rental demand.
Skip the Golf Communities for Cash-Flow Refinancing
Pelican Landing, The Colony, and Bonita Bay are Bonita Springs’ most recognizable addresses — and among the weakest fits for a coverage-driven cash-out strategy. NeighborhoodScout’s data on the Colony at Pelican Landing/Spring Creek Village reports an average rent of just $1,923, alongside a striking 32.3 percent residential vacancy rate — higher than 96.2 percent of neighborhoods nationally.
That vacancy figure isn’t a rental-demand problem; it reflects the neighborhood’s second-home and seasonal-ownership composition, not a shortage of tenants. But for a DSCR file, the effect is the same either way: a high-value property with thin, seasonal rental income produces weak coverage math regardless of the underlying cause. Not ideal for an equity-extraction strategy that depends on rent covering the new obligation. Investors chasing appreciation in these gated communities are playing a different game than investors chasing cash flow, and the two strategies shouldn’t be underwritten the same way.
One notable exception worth tracking: a Gulf-access parcel currently listed in 34134 carries zoning entitlement for up to 10 units, with 8 already built and rented, per Redfin’s 34134 multi-family listings. Entitlement that exceeds current improvement changes both the appraised value basis and the long-run refinance ceiling on that property — a different risk-and-reward profile than a standard single-family lot, and the kind of upside optionality worth flagging for an investor already comfortable underwriting multi-unit product.
How the Seasoning Clock and Florida’s 70 Percent Cap Actually Work
Most cash-out refinance programs on the network Lendmire arranges through require about six months of ownership seasoning, measured from the title recording date, before the payoff and new appraisal can proceed. That timeline exists to give the property a documented ownership history the new appraisal can lean on — not to slow anyone down artificially.
Florida carries no state overlay on top of standard program guidelines: cash-out LTV here caps near 75 percent, the same ceiling that applies in other states. On a property appraised at $650,000, that 75 percent ceiling — combined with the minimum 1.00 DSCR floor most standard programs require, and credit tiers that generally run from 620 up through 700 depending on pricing and reserves — sets the practical boundaries of what’s available. Reserve requirements typically run around six months of PITIA, stepping up near nine months on loan balances above $1,500,000. None of these are guarantees; they’re the range within which a given file gets reviewed, and the specific number depends on the borrower’s credit profile, the property’s rent roll, and reserves on hand.
Investors holding title through an LLC can generally still access these programs, subject to lender program eligibility and documentation requirements specific to entity-owned files. Lendmire’s DSCR cash-out refinance program overview covers the broader mechanics, and Lendmire’s refi programs page walks through the range of structures available beyond a straight cash-out. For investors comparing this against a conventional refinance, the side-by-side comparison breaks down why property-income underwriting tends to fit LLC-titled and self-employed investors better than a standard W-2 file.
Lendmire, a mortgage broker (NMLS# 2371349) rather than a direct lender, works this file type through wholesale channels specific to Florida DSCR investor loans, and reaching the team directly at 828-256-2183 or through talk to Lendmire is generally the fastest way to get a specific property’s numbers reviewed rather than modeled.
What DSCR Means for a Refinance File
DSCR — debt-service coverage ratio — is simply the property’s monthly rent divided by its full monthly carrying cost, including principal, interest, taxes, insurance, and any HOA dues. Lendmire’s primer on DSCR loans walks through the mechanics in more depth, but the short version for a cash-out file is this: the higher the rent clears that number relative to the new obligation after refinancing, the more room the file has to support a larger cash-out draw at the same 70 percent ceiling.
Frequently Asked Questions
How much of Bonita Springs’ equity growth is realistic to pull out via cash-out refinance?
That depends entirely on the current appraisal, not the purchase price. Given Florida’s 70 percent LTV cap on cash-out refinances, an investor’s available equity is a function of appraised value, existing loan balance, and whether the rent roll clears the required DSCR floor — not a fixed percentage of appreciation gains. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
DSCR vs. conventional financing
Two common ways to finance an investment property in Bonita Springs, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Why is inland Bonita Springs (34135) a stronger cash-out candidate than the beach corridor (34134)?
Inland 34135 carries a lower price basis — new listings there run near a $500,000 median — while coastal 34134 averages $740,000 with prices down 24.5 percent year over year. Lower basis relative to rent typically produces a stronger DSCR at refinance, even though the coastal segment may carry a stronger long-run appreciation case.
Does the Herc Rentals headquarters actually affect rental demand for a specific property?
It affects the tenant pool available to landlords near the Imperial River Corridor and downtown Bonita, where the roughly 420-employee Field Support Center is based. Corporate transferees tied to that campus tend to seek professional long-term rentals rather than short seasonal stays, which can support steadier occupancy than a purely retiree- or tourist-driven submarket.
Are duplex and triplex properties actually available to refinance in Bonita Springs?
They exist, but they’re scarce — roughly 1 percent of the local housing stock by one estimate, concentrated in listings between $375,000 and $9,000,000 according to Homes.com’s tracking. Investors holding one of these properties already have access to a rarer asset type in this market, which is part of why the combined-unit rent math on a duplex pair often produces stronger coverage than a comparable-priced single-family home.
How does the seasonal-heavy vacancy in communities like Pelican Landing affect a cash-out application?
It doesn’t disqualify a file outright, but it typically weakens the DSCR math. Pelican Landing’s 32.3 percent vacancy rate reflects second-home ownership patterns rather than a rental shortage, yet an appraiser and lender still evaluate actual lease income, so investors in these gated, seasonal-heavy communities should expect tighter coverage ratios than an inland workforce rental would produce.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. Eligibility review generally centers on the property’s rental income rather than the borrower’s personal income, subject to lender and program guidelines, which tends to fit self-employed investors and LLC-owned portfolios particularly well. The firm was named a 2026 Scotsman Guide Top Mortgage Workplace and a 2025 Scotsman Guide Top Mortgage Workplace, recognition detailed in the 2026 industry recognition release. Investors working a Florida file can also start from the state-level overview of DSCR investor loans in Florida. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
For broader investor-financing rules and property-type coverage across the state, see Florida DSCR loans.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Redfin — Bonita Springs Rental Market
5. NeighborhoodScout — Colony at Pelican Landing/Spring Creek Village
6. DuplexForSale.com — Bonita Springs
7. Homes.com — Bonita Springs Multi-Family Listings
8. Redfin — 34134 Zip Housing Market
9. Redfin — 34135 Zip Land Listings
10. Zillow Home Value Index — Bonita Springs
11. Census Reporter’s ACS 2024 five-year profile
12. Herc Rentals Careers — Corporate Field Support
13. Florida-Demographics.com — Bonita Springs Demographics
14. Gulfshore Business — Top Regional Employers Study
15. Redfin — 34134 Multi-Family Listings
16. 2025
17. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Bonita Springs · DSCR Loans Naples FL: Investor Financing for Old Naples, Marco Island, Bonita Springs, Estero & Real Estate Investors · Investment Property Loans in Palm Springs, CA: The 2026 DSCR Financing Guide to Sunrise Way
Guides: Investment Property Cash-Out Refinance in Bonita Springs, FL · Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.