
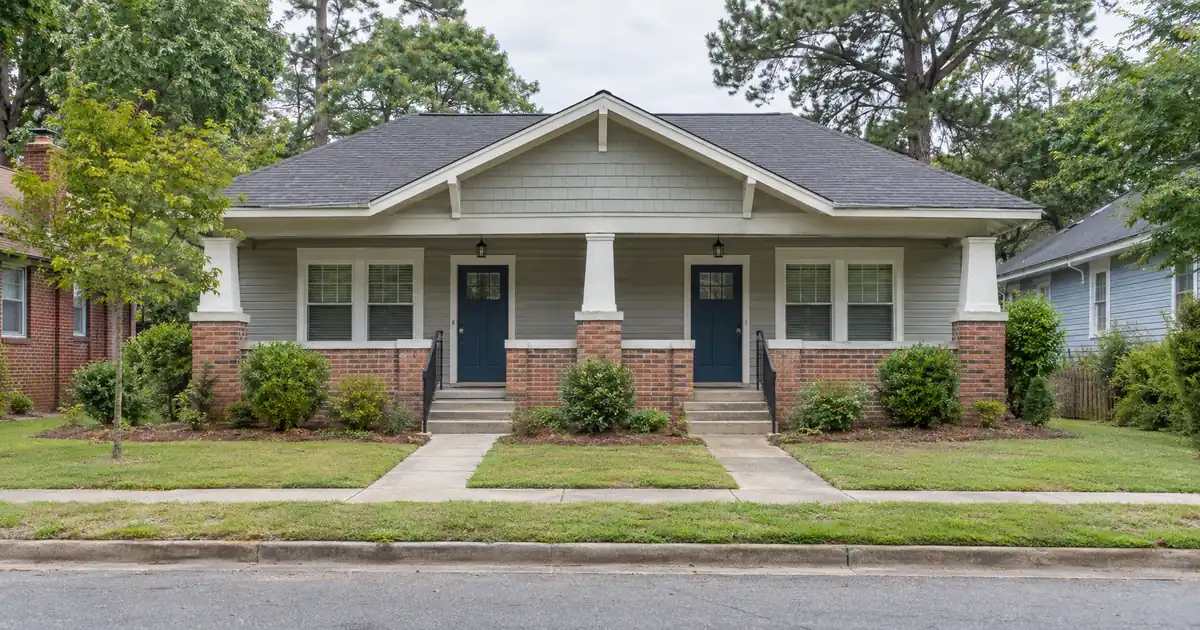
Only 5.44% of Decatur’s housing units are duplexes, converted homes, or small apartment buildings. Single-family detached homes are 69.90%. That split decides most cash-out files here. A single-family rental carries one rent against the full monthly obligation. A fourplex stacks four rents against one. The appraised value sets the 75% ceiling, and the rent decides whether the file clears 1.00.
DSCR Cash-Out Calculator
Run the cash-out numbers in Decatur, AL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A DSCR cash-out refinance on an investment property in Decatur, Alabama is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the loan sized off appraised value. About 37% of Decatur households rent, which keeps a real tenant pool behind the collateral.
- Cash-out tops out at 75% LTV, with about 6 months of ownership seasoning from title recording.
- Small 2-4 unit stock is thin, so fourplexes and duplexes carry the strongest stacked-rent math.
- Prices are flat to soft and sales are slower, so expect equity from buy-basis, not market lift.
- Demand rests on industrial, hospital, and aerospace payroll, not population growth.
- A single-family rental at the city median can land under 1.00 once taxes and insurance are in.
- Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
For Decatur, Alabama rental property financing, Lendmire helps arrange DSCR loans through lenders operating in 41 markets, including Washington, D.C. This article covers the equity-extraction side only. It assumes you already own the property.
The Seasoning Clock Starts at Recording
Cash-out on a DSCR file generally requires about 6 months of ownership, measured from title recording, and caps at 75% LTV. The rent has to cover the full payment, principal, interest, taxes, insurance, and any HOA dues, at or above 1.00x on most standard programs, subject to lender guidelines.
Files that stall here usually stall on seasoning. The investor counts from closing day or from when the rehab wrapped. The lender counts from the recording date on the deed, and the settlement statement proves it. If you bought in an LLC, have the operating agreement and the title vesting match before you submit. LLC vesting is workable, subject to lender program eligibility, but a mismatch between the entity on title and the entity on the application is a preventable gap.
The 75% cap is a ceiling, not a payout. Equity available depends on rent used for lender review, the full monthly obligation, reserves, and appraised value. Reserves run about 6 months of the full payment, and higher on larger balances. Reserves documentation is where people get sloppy, so pull two months of statements showing the funds sit in an account titled to the borrower or entity. Credit tiers on the standard programs start at a 620 floor and step up through 660, 680, and 700. Pricing and leverage improve as the score climbs, and exact eligibility depends on the lender and the file.
Balances run up to $3,000,000 on standard programs. Smaller balances route through select lenders in the network, which matters in Decatur’s lower-priced pockets, covered below. The cash-out refinance walkthrough lays out the general mechanics if you want the program-level detail.
What Decatur’s Housing Stock Does to the Coverage Number
Fourplexes and duplexes are the best DSCR cash-out candidates in Decatur because the rent stacks across units. They are also scarce. Workforce single-family homes are the deepest pool of stock, but they carry a single rent stream and run thinner on coverage.
Start with the multi-unit side. Homes.com showed 11 multi-family homes for sale in Decatur, priced from $200,000 to $750,000. Two of them are telling. One is a fourplex in the southwest part of the city with four identical 2-bed/1-bath units. Another is a quadplex in the Glenmier area with four 2-bed/1-bath units, updated with vinyl plank flooring and modernized kitchens, and it was fully occupied when listed. That is the format the rent data supports.
Run the numbers on a modeled fourplex. Rentcast data via Prop-Metrics puts median two-bedroom rent at $1,040. Four units at that figure gross roughly $4,160 a month. That is a modeled assumption that mixes a rent source with listing-style unit counts, not a published rent-to-value figure. Assume the building appraises near $400,000 and you refinance at 75% LTV. Coverage, including taxes and insurance, modeled on the full monthly obligation, runs comfortably above 1.5x. Push the appraisal toward $500,000 and it slides to roughly 1.4x. Either way the file clears the 1.00x benchmark with room to absorb a vacant unit. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Now the single-family side. Take a house at the city median, about $240,000, and assume it rents near Zillow’s all-type average of $1,195. Refinance at 75% and coverage including taxes and insurance lands around 0.85x. That is under 1.00 on long-term rent alone. Options a lender may review include a sub-1.00 program, an interest-only structure, a lower LTV, or more cash left in the deal. Eligibility under any of those depends on lender guidelines, credit profile, reserves, and property review. Thin files like this one get declined more often than they get restructured.
Two-bedroom and one-bedroom units make up 54.6% and 20.6% of the rental stock, according to the same Rentcast data. Small-format units are what Decatur tenants rent. Buy or hold that format and the math stays workable. Hold a large single-family house in a submarket where comps are older and rents are lower, and the coverage gets harder to defend.
(Five-plus unit buildings are a different product. Listings in the $799,000 to $939,000 range typically get commercial-style underwriting, not the 1-4 unit DSCR box. Keep them out of this conversation.)
Soft Prices, Slow Sales: The Appraisal Problem
Decatur is a cash-flow market, not an appreciation market. Prices are flat to slightly down and homes sit longer, so a cash-out appraisal is more likely to reflect the investor’s original buy-basis and any rehab than a rising market.
The sources disagree on the exact median, so treat the figure as a range. Redfin’s median for the most recent three-month window was $240,000, down 3.1% year over year, with 84 days on market versus 55 a year earlier. Movoto placed it higher at $263,400 with 78 days on market versus 46. Zillow’s home value index runs lower, at $215,807, up 2.4%. The methods differ. The direction does not: flat to slightly soft, with slower sales. This article uses the Redfin figure as its reference point. Zillow’s one-year projection is slightly negative, about -0.4%, per the Prop-Metrics page.
What that does to a file is mechanical. A cash-out loan sizes off appraised value. Slower sales mean fewer recent comps, and an appraiser working with thin, older comps tends to come in conservative. Underwrite on today’s rent and today’s value, with no assumed price growth. If you pencil a refinance assuming a 10% bump over what you paid, expect the value to come back short and the loan amount to come back smaller.
Appraisal reconsideration is a routine step on files like this, not an emergency move. A packet with recent sales in the same neighborhood, condition adjustments, and a documented scope of any rehab recovers value when the first comps are light. It won’t manufacture equity that isn’t there. The stronger play is to buy at a discount, improve the unit, and refinance on the improved value. Waiting for the market to do the work is the weaker one. One more caution: some lenders layer a declining-market overlay onto files in softening metros, which can trim the maximum LTV below 75%. Ask before you order the appraisal.
Where the Rent Comes From
Decatur’s rental demand rests on industrial, hospital, and aerospace payroll, not on population growth. The city sits at about 57,361 residents per Census Bureau QuickFacts, with median household income of $61,563, so the thesis is jobs and location.
The Decatur-Morgan County Chamber’s top employer list reads like a workforce-housing tenant roll. Decatur Morgan Hospital leads at 1,900 employees. Decatur City Schools follows at 1,445, then GE Appliances at 1,400, Morgan County Schools at 1,000, Wayne-Sanderson Farms Prepared Foods at 820, 3M at 788, and Nucor Steel Decatur at 767. Data USA counts 14,634 manufacturing workers in the Decatur area, 8,682 in retail, and 6,900 in construction. Those are the people renting two-bedroom units.
The hook is United Launch Alliance. Its About page places manufacturing, assembly, and integration at Decatur. The Washington Times describes a 2.4-million-square-foot plant aiming for 20 to 25 vehicles a year, and a ULA executive puts the five-year North Alabama economic impact above $5 billion. That last figure is a company statement, not an independent study. Read it as an employer signal, not a rent forecast.
Commuting data shows why the tenant pool reaches past city limits. Per NAIDA, 27,148 Morgan County residents work outside the county, and 28,688 outside residents commute in. Jobs in the wider corridor feed Decatur’s rental demand. Business Alabama reports that Mazda Toyota Manufacturing in neighboring Limestone County has more than 4,000 employees, and that Nucor Towers & Structures is building utility steel pole production in Decatur. Calhoun Community College crossed 10,000 students per WHNT, up from 9,119 the prior fall per the Decatur Daily. It is a commuter campus, so it adds workforce renters, not a dorm market.
Rent trends are mixed and roughly flat. Zillow shows the all-type average at $1,195, down $100 year over year. RentCafe shows apartment averages at $955, up 2.94%, but covers only buildings with 50 or more units. Rentcast’s averages are higher than either. Use whichever figure your lender’s rent schedule or lease supports, and don’t cherry-pick the highest one.
Submarkets That Pencil
Decatur has no public source ranking rent-to-value by submarket, so the profiles below are qualitative. The fit comes from housing type and proximity to the employer base, not from published neighborhood ratios.
Southwest Decatur and Glenmier are where the multi-unit stock shows up. Local property managers describe the area as a mix of townhomes and affordable single-family homes, and the fourplex listings cluster here. For a cash-out, this is the most natural fit: identical 2-bed/1-bath units are easy to document, easy to appraise against each other, and easy to rent.
Albany Historic District and Old Decatur are the older end. The district is walkable, near the Princess Theatre and Delano Park, and was listed on the National Register of Historic Places. It likely holds some older converted duplex stock, though that is an inference, not a sourced fact. Older housing adds file work. Expect the appraiser to adjust for condition, and expect the lender to want clear documentation of updates to systems.
Downtown Decatur and Almon Place show up as the most affordable rent zones by one source. Lower rents mean tighter coverage, so buy-basis discipline matters most in those pockets. Moulton Heights is described as affordable, quiet, and close to the main business areas, which suits workforce single-family rentals. The Point Mallard area is a park and recreation anchor, more amenity than rental thesis.
Then there’s the low-basis end. A three-bed, one-bath house in the 35601 ZIP sold for $118,500, 5% under list after 83 days on market. That is roughly half the city median. Rent covers the debt most easily at that price, but two problems follow. Some lenders won’t fund balances that small, and condition problems are common. Don’t pair that sale price with the city-wide three-bedroom rent, because the $1,880 Rentcast figure looks high for a house at that price and no verified rent exists for this submarket. Check the lender’s minimum loan amount before pitching a small-balance refinance. Smaller balances route through select lenders in the network, not through the standard programs. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
What a Clean File Looks Like
DSCR files in markets like this one typically look like a soft-appraisal, small-unit, workforce-tenant profile. Coverage pencils cleanly on multi-unit stock and gets tight on single-family. The files that move without rework have leases, rent roll, entity documents, title, and reserves statements assembled before submission, and the appraisal is ordered only after the investor has confirmed the lender’s declining-market overlay and minimum loan amount. The files that get kicked back usually assumed seasoning, rent, or value that the documents didn’t support.
Here is the order of operations on a Decatur cash-out:
1. Confirm seasoning from title. Pull the recorded deed and settlement statement. The six-month count starts at recording, not at closing or rehab completion.
2. Assemble the rent evidence. Current leases for every unit, plus a rent roll that matches them. On a fourplex, a missing lease for one unit gets the whole building underwritten on market rent instead.
3. Match the entity to title. If an LLC holds the property, the operating agreement, good standing, and title vesting should line up, subject to program terms.
4. Document reserves. About six months of the full payment, in statements titled to the borrower or entity. Larger balances need more.
5. Ask about overlays and loan minimums before the appraisal. A declining-market overlay or a balance below the standard-program range changes which lender the file goes to.
6. Prepare the reconsideration packet in advance. Recent in-neighborhood sales, condition notes, and a scope-of-work summary if you improved the property.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Decatur, AL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The cleanest file from a documentation standpoint has complete leases, entity docs, title, and property details ready for lender review. Clean documentation doesn’t guarantee an outcome, but it leaves fewer preventable gaps. If the coverage math is new to you, it helps to start by understanding how the qualification works. For a file-specific read, reach Lendmire at 828-256-2183 or see how the math pencils.
Where Do the Proceeds Go?
Cash-out proceeds in Decatur work best as a down payment on the next small multi-unit, not as a reserve against a market that may not lift. The thin 2-4 unit stock is the constraint, so the capital has to be ready when a fourplex lists.
Honestly, this one is a genuine toss-up. Pulling equity from a flat market means you’re recycling capital into an asset class where price growth is unlikely. Coverage on stacked-rent buildings is the reason to do it anyway: a fourplex that clears 1.4x or better has room to carry a vacancy. Investors who would rather hold cash-flowing single-family homes and skip the refinance aren’t wrong either, especially with coverage near or under 1.00 on the single-family side. Comparing DSCR loans with conventional financing is worth the time if you are weighing alternatives. The broader menu of investment property refinance options is also worth a look, and the state overview is at DSCR loans in Alabama.
One general reminder: verify current local rental rules, taxes, and insurance with qualified local professionals before you model a hold.
Frequently Asked Questions
How much equity can I pull from a Decatur rental?
The ceiling is 75% of appraised value, less the existing balance, and subject to lender guidelines. The actual amount depends on rent used for lender review, the full monthly obligation, reserves, and what the appraiser supports in a market where prices are flat to slightly soft. Treat 75% as the maximum, not the expected figure.
Does a soft Decatur market hurt a cash-out appraisal?
Yes, it can. Redfin’s data shows prices slipping year over year and homes taking longer to sell. Slower sales mean thinner comps, and appraisals tend to land conservatively. A reconsideration packet with recent in-neighborhood sales and condition adjustments often recovers value, but it can’t create equity the property doesn’t have.
Is a single-family rental enough to clear 1.00 in Decatur?
Often not at the city median. A house near $240,000 renting at the $1,195 all-type average models around 0.85x including taxes and insurance at 75% LTV. Lower-priced houses or lower leverage improve it. A lender may also review a sub-1.00 program or an interest-only structure, subject to credit approval and property review.
Why do fourplexes matter so much here?
Small 2-4 unit buildings are only 5.44% of Decatur’s housing units, so they’re scarce, and they’re where rent stacks. Four 2-bed units at a modeled $1,040 two-bedroom rent gross about $4,160 a month on a modeled basis. That’s enough to clear the benchmark with cushion on many value assumptions.
Which Decatur employers support the tenant base?
Decatur Morgan Hospital (1,900), Decatur City Schools (1,445), GE Appliances (1,400), Wayne-Sanderson Farms Prepared Foods (820), 3M (788), and Nucor Steel Decatur (767) lead the chamber’s list. United Launch Alliance builds rockets at its Decatur plant. The hospital operates four campuses.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) places investor financing across 41 markets, 40 states plus Washington, D.C. DSCR eligibility is generally reviewed by the lender on property cash flow instead of traditional personal-income documentation, subject to lender guidelines. Lendmire was named a 2026 Scotsman Guide Top Workplace and was a top-ranked workplace in 2025.
The investors who underwrite Decatur on today’s rent and today’s value, and buy their small multi-unit stock at a discount, will come out ahead.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. NeighborhoodScout — Decatur Real Estate
2. RentCafe — Average Rent Market Trends Decatur
3. Homes.com showed 11 multi-family homes for sale
4. Rentcast data via Prop-Metrics
6. Movoto
9. Decatur-Morgan County Chamber’s top employer list
10. Data USA
11. About page
13. NAIDA
14. Business Alabama
16. WHNT
17. Decatur Daily
18. hospital
19. a 2026 Scotsman Guide Top Workplace
20. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Decatur, AL · Investment Property Cash-Out Refinance in Alabama
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.