
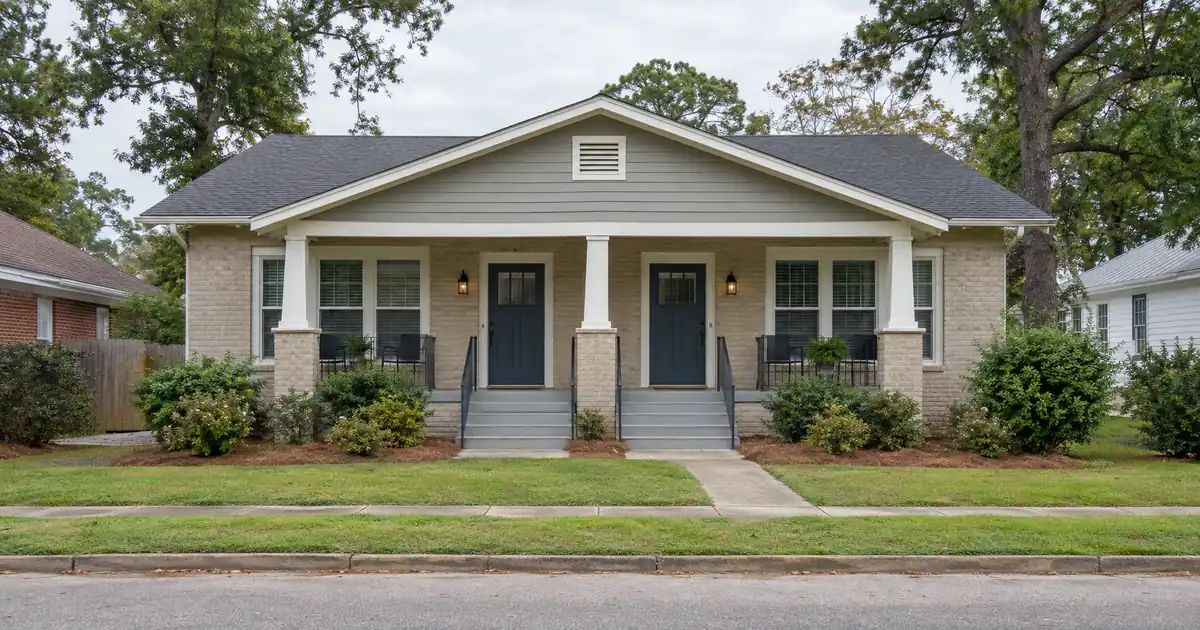
If you own a rental in Florence and plan to refinance on the assumption that the market has been building your equity, check that assumption first. Price readings for this city disagree with each other, and the cash-out amount follows the appraisal, not the headline.
TL;DR: A DSCR cash-out refinance in Florence, Alabama is underwritten primarily on the property’s rental income measured against its full monthly obligation. The file then runs through title seasoning, an appraisal, and a reserves check before any proceeds are available to redeploy into the next purchase.
DSCR Cash-Out Calculator
Run the cash-out numbers in Florence, AL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Redfin puts the median sale price at $242K, while Zillow’s value index reads $205,555.
- Cash-out LTV caps at 75 percent, with about six months of ownership from title recording.
- Single-family detached homes make up 64.28 percent of units, so duplex comps run thin.
- UNA’s record enrollment of about 10,730 students supports renter demand near campus.
- Citywide average rent near $975 puts typical purchases below 1.00 coverage at full leverage.
Florence Market Snapshot
A quick read on the Florence investor landscape. Figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | Median price $149,763 (NeighborhoodScout, North) |
| Typical rents | Rent $1,150 (NeighborhoodScout, North) |
| University enrollment | 10,000+ students (Shoals Chamber, UNA listing) |
| Employment | 269 jobs (Business Alabama, Lauderdale &) |
| Vacancy | 34.7% (NeighborhoodScout, Florence West) |
Why Florence Equity Needs a Different Playbook
Florence is a cash-flow market with flat-to-modest price growth. Treat it that way. Census Bureau QuickFacts puts the city at 41,701 residents with a median household income of $52,174 and a median age of 35.1. The Florence-Muscle Shoals metro holds 156,287 people. That is a regional hub, not a boom town.
The price signals conflict. Redfin’s October median sale price was $242K, up 10.0 percent year over year, but that is a single-month median and it swings. Zillow’s value index shows $205,555, up just 0.2 percent over the past year. The gap is partly method: Zillow indexes every home, while sale medians skew toward whatever happened to sell. Movoto lands near Redfin at $244,900.
The practical read: don’t build a refinance thesis on market lift. Equity in Florence comes from buying below the median, adding value through renovation, or adding a unit. Owners who got in that way have real cash-out room. Owners who bought at the median and waited usually don’t.
How the Cash-Out Math Is Built
The 75 percent LTV ceiling is a hard cap on cash-out. The 80 percent figure you see on purchase programs doesn’t apply here. Everything else on the file flows from that number.
Typical program guidelines look like this, subject to lender guidelines and the specific file:
- Seasoning: about six months of ownership, measured from title recording.
- Coverage: 1.00 is the common benchmark, with rent measured against full PITIA (principal, interest, taxes, insurance and any HOA dues).
- Credit: a 620 floor, with better terms at the 660, 680 and 700 tiers.
- Reserves: about six months of PITIA on most files.
- Loan size: up to $3,000,000 on standard programs, with smaller balances routed through select lenders in the network.
That last line matters in Florence. Much of the rental stock sits in the low six figures, so loan balances run small. Whether a lender takes a balance of that size is the first question on many Florence files, ahead of coverage. The cash-out refinance details page covers the program mechanics. Lendmire’s DSCR walkthrough explains how the ratio is built.
One property-type note. Manufactured homes, log homes and barndominiums fall outside these DSCR programs. Some rural-edge properties around the Shoals can be mistaken for conventional houses, so confirm construction type before the file goes in.
Where the Coverage Math Pencils and Where It Doesn’t
Citywide averages put typical purchases below the line. One roundup puts the December median sold price at $201,309 with average rent of $975, a secondary source worth attributing. That works out to under 0.5 percent monthly rent-to-price. At full 75 percent LTV, with taxes and insurance included, coverage on that pairing lands below 1.00.
A sub-1.00 file isn’t dead. A lender in the network may review a sub-1.00 program, an interest-only structure, or a lower LTV that brings the ratio back up. Each depends on credit, reserves and property review, and none is assured. Treat the sub-1.00 route as a structure to price, not a default.
Rent figures in Florence scatter by source, so name the source and underwrite from the actual lease:
| Source | Reading | Note |
|---|---|---|
| Real Estate Skills | $975 average rent | Citywide, secondary source |
| Apartments.com | $593 average, 2BR $802 | Apartment-weighted, up 3.2 percent |
| Rent.com | $510 to $800 range | Apartment listings only |
| NeighborhoodScout, North Florence | $1,150 average | Modeled estimate |
The apartment-weighted figures understate what a single-family house or duplex rents for. The $1,150 modeled figure for North Florence is the more useful anchor for a detached rental.
North Florence: The Modeled Sweet Spot
North Florence (ZIP 35630) is the submarket where the modeled numbers work. NeighborhoodScout shows a median price of $149,763 and average rent of $1,150. These are modeled estimates, not closed-sale data. The housing mix runs from three- and four-bedroom homes to smaller single-family houses plus apartment complexes, with workforce and budget renters as the likely tenant base.
Run the numbers on a hypothetical house valued near that modeled median, rented at the modeled figure. At 75 percent LTV, with taxes and insurance included in full PITIA, coverage lands around 1.2x. That is a modeled assumption, not a quote. Rent-to-value of roughly 0.77 percent is what clears 1.00 with room to spare here. The same asset at the citywide median rent does not.
The file risk is the appraisal. A modeled median is not a comp. The appraiser will pull recent closed sales, and Florence’s thin, mixed-vintage stock produces wide spreads.
Florence West: Low Price, Real Caution
Florence West is the lowest-price pocket in the research, and it carries a warning. NeighborhoodScout’s modeled figures show a median price of $105,088 and average rent of $736, with 34.7 percent of residential real estate vacant. The housing is small single-family and small apartment buildings, mostly renter-occupied.
Skip it for cash-out unless the numbers are property-specific. Rent is low in absolute terms, balances are small, and a 34.7 percent vacancy figure tells an appraiser and a lender to look hard at stabilization. A lender reviewing the file will want a signed lease and a payment history, not a neighborhood average.
Downtown and the Historic Districts Near UNA
The University of North Alabama is the demand anchor for the core. UNA set an enrollment record, with its president citing about 10,730 students and noting enrollment was under 7,000 when he started 11 years ago. That figure is a media statement, not a census-date report. He also described a target range of 10,000 to 12,000, per WAFF. Read it as steady renter demand near campus from students, staff and faculty, without open-ended growth.
Two pockets matter for small-unit investors. The Locust Street district holds over 85 Craftsman bungalows northwest of downtown. The Cherry Street district includes five apartment buildings originally built to house a worker influx, a rare pre-war small multifamily pocket. No sourced prices or rents exist for either, so don’t assign numbers. Downtown’s Court Street area, with Wilson Park and arts venues, draws young professionals and campus-adjacent renters.
Duplexes: The Better Cash-Out Candidate
Small multifamily is a real but minority niche. NeighborhoodScout’s housing mix shows single-family detached at 64.28 percent of units, large apartment complexes at 23.05 percent, and duplexes or small converted buildings at 10.34 percent. That is a modeled figure.
Here’s the tension. A second rent stream is the most reliable way to lift coverage in a market where single-family rent-to-price runs under 0.5 percent at the median. The same scarcity makes appraisal harder, because 2-4 unit comps are thin. The stronger play may be a duplex near the university over a detached house in the cheaper pockets, though investors who want lower entry prices could argue the other way. The unit-count benefit is inference from the housing mix and Cherry Street’s history, not from a rent dataset.
What Most Cash-Out Files Get Wrong Here
The failure mode on Florence files is the appraisal range, not the ratio. Owners price their equity off a portal estimate. Zillow’s index sits about $36K below Redfin’s sale median, so which number the owner used decides whether the file looks fine or short. Appraisers work from closed sales of comparable property type, and the median sale skews toward newer or larger homes than most rental stock.
On files from markets like this one, the common friction point is a mismatch between the owner’s expected value and the appraisal. The cleaner files from a documentation standpoint tend to carry a settlement statement proving title recording and seasoning, a signed lease with rent history, entity documents that match the vesting, and renovation receipts that support an improved value. When the appraisal lands light, a reconsideration packet with recent in-neighborhood sales and condition adjustments is a routine step, not an emergency one.
Hold entity paperwork to the same standard. If the property sits in an LLC, the operating agreement, EIN letter and vesting need to line up before submission, subject to lender program eligibility.
Turning Proceeds Into the Next Deal
Equity available is not a fixed number. It depends on rent used for lender review, PITIA, reserves and the 75 percent LTV ceiling, and it is never a guaranteed cash figure. An owner whose payoff already sits near 75 percent of appraised value gets little. An owner who bought at a discount and renovated may get meaningful proceeds.
The sequence that works: confirm seasoning from the recording date, order the appraisal, document reserves, and size the next purchase against the proceeds the lender actually indicates. Florence has employment support behind long-term rentals. The Shoals draws on manufacturing, health care and education. Data USA lists retail trade (3,503 residents), accommodation and food service (2,642) and manufacturing (2,635) as the most common resident sectors. Business Alabama reports AE Industrial Partners acquired a 638-acre, 2-million-square-foot former rail car plant for an aerospace center of excellence, and a $26M Lauderdale County Workforce Development Center. North Alabama Shoals Hospital employs over 300 people with more than 100 physicians on staff.
Those anchors support rental demand. They don’t create forced equity, so the refinance thesis should rest on the purchase discount or the value you added.
For a conventional comparison, see Lendmire’s guide comparing DSCR and conventional loans. Rate-term and other refinance paths sit on the investor refinance options page. For the state overview, see DSCR loan options for Alabama investors.
Verify current local rental rules, property taxes, insurance, flood zones and historic-district requirements with qualified local professionals before you renovate or close.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Florence, AL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
If you want to talk through a specific file, reach Lendmire at 828-256-2183 or connect with Lendmire.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Florence, Alabama?
Qualification centers on the property’s rent measured against its full PITIA, with 1.00 as the common benchmark. Lenders also review credit (a 620 floor, with tiers at 660, 680 and 700), reserves of about six months PITIA, and about six months of ownership from title recording. Exact eligibility depends on lender guidelines, the property and the borrower.
What are the requirements for an investment property loan in Florence, Alabama?
Expect a signed lease or market rent from the appraisal, entity documents if an LLC holds title, reserves documentation and a clean title. Cash-out is capped at 75 percent LTV. Manufactured homes, log homes and barndominiums fall outside these programs. Small balances may route to select lenders in the network.
Why does the appraisal matter so much on Florence files?
Value sources disagree by tens of thousands of dollars, and cash-out is sized off the appraisal. Zillow’s index reads $205,555 while Redfin’s median sale reads $242K. The appraiser works from closed comps of the same property type, so a duplex with few comparable sales can come in lighter than expected. A reconsideration packet with in-neighborhood sales is the standard response.
Do duplexes near UNA work better than single-family rentals for cash-out?
Often, because a second rent stream lifts coverage where single-family rent-to-price runs under 0.5 percent at the median. The tradeoff is thinner comps, since small multifamily is about one in ten units. Run both scenarios against actual leases before choosing.
Can Lendmire help structure DSCR financing for small multifamily investment properties in Florence?
Yes. Standard programs run up to $3,000,000, and smaller balances route through select lenders in the network, subject to lender guidelines.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a DSCR-focused mortgage brokerage, NMLS# 2371349, placing investor loans across 41 markets, including Washington, D.C. Lendmire is recognized as a 2026 Scotsman Guide Top Workplace and a 2025 Scotsman Guide Top Mortgage Workplace. DSCR eligibility is generally reviewed by the lender on a property’s rental income rather than personal income documentation, which fits LLC-held rentals, self-employed investors and portfolios scaling past conventional financed-property limits.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Florence housing market
2. NeighborhoodScout, North Florence
3. Shoals Chamber, UNA listing
4. Business Alabama, Lauderdale & Colbert economic engines
5. NeighborhoodScout, Florence West
6. U.S. Census Bureau QuickFacts, Florence city
7. Zillow, Florence home values
8. Movoto, Florence market trends
9. Real Estate Skills, best places to buy rental property in Alabama
10. Apartments.com, Florence rent trends
11. Rent.com, Florence rent trends
13. WAFF, UNA enrollment record
14. NeighborhoodScout, Florence real estate
16. Business Alabama, Colbert and Lauderdale economic engines
17. North Alabama Shoals Hospital
18. Scotsman Guide, 2026 Top Workplace
19. Scotsman Guide, 2025 Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Florence, AL · Investment Property Cash-Out Refinance in Alabama
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.