
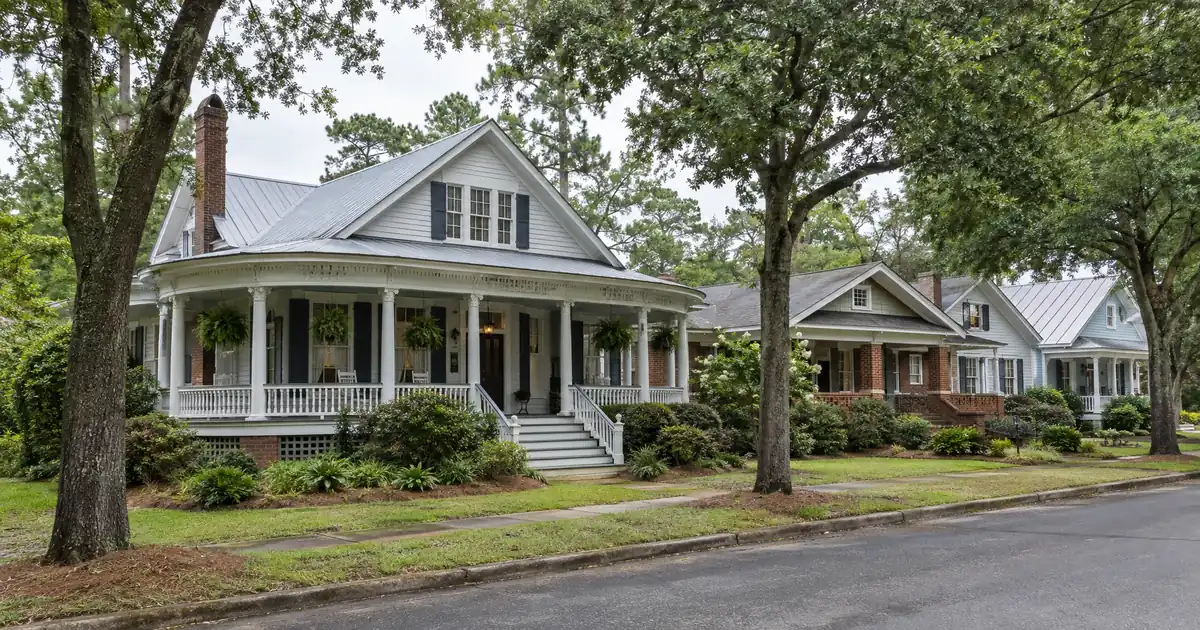
Can a Foley rental actually carry a cash-out refinance when a median-priced house barely rents for its own carrying cost? Sometimes, but the building type decides it, not the neighborhood. A DSCR cash out refinance in Foley, Alabama works best on small multifamily and newer, lower-priced single-family product, where stacked or efficient rent covers the full obligation with room to spare.
TL;DR: A DSCR cash-out refinance on a Foley, Alabama rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the path runs from confirming ownership seasoning, to documenting rent or a market rent opinion, to an appraisal that sets the 75% LTV ceiling, to lender review of reserves.
DSCR Cash-Out Calculator
Run the cash-out numbers in Foley, AL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Duplexes and small multifamily are only about 5% of Foley housing units, per NeighborhoodScout, so comps run thin.
- Modeled duplex coverage runs near 1.5x including taxes and insurance. Median-priced single-family sits just under 1.00.
- Cash-out is capped at 75% LTV after roughly six months of seasoning from title recording. Redfin shows a $328K median, but days on market stretched from 64 to 95.
- Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Foley Market Snapshot
A quick read on the Foley investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $329,000 median (Homes.com multi-family) |
| Population | 24,026 population (Census Reporter) |
| Employment | 800+ employees (City of Foley (SBRMC article)) |
Why Does Foley Punish the Typical Single-Family Rental?
Foley’s rent-to-value ratio on conventional single-family is thin. Prices sit in the low-$300Ks while rents cluster well below 1% of value, so a house at the median usually lands at or under 1.00 coverage once taxes and insurance are in the debt service.
Per Redfin, the median sale price is $328K, up 2.1% year over year, and homes took 95 days to sell versus 64 a year earlier. Single-family detached homes are 72.09% of housing units, large apartment complexes are 13.05%, and mobile homes are 6.00%, according to NeighborhoodScout. (Manufactured homes fall outside the network’s DSCR programs entirely, so that 6% is not your opportunity set.)
On the rent side, Apartments.com lists an average of $1,271 for newer apartments, ranging from $986 to $1,893. Redfin’s ZIP 36535 listings show new-build 3-to-5-bedroom homes asking from $1,799. Treat those as illustrative asking rents, not medians.
Run the numbers this way, as a modeled assumption: a house valued near the $328K median, a 75% cash-out LTV, and the $1,799 new-build rent. Coverage lands just under 1.00 once the full PITIA, taxes and insurance included, is counted. Against the $1,271 average rent it falls closer to 0.7. Not ideal. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Sub-1.00 files aren’t dead, but they get harder. A lender may look at lower leverage, a sub-1.00 program, or an interest-only structure, each subject to lender guidelines, credit approval, and property review. Stronger credit and added reserves usually come with them.
Duplexes and Small Multifamily: The Scarcity Play
Two-to-four-unit product is the best DSCR cash-out fit in Foley, because it stacks rent on one lot at a price near a single-family home. The catch is that comps are sparse, and that shows up at appraisal.
Apartments.com’s newer-apartment averages run $1,451 for a two-bedroom, and Apartment List shows listing averages of $1,632+. Two 2BR doors therefore gross roughly $2,900 to $3,260 a month. Against a price near the median, that is about 0.9% to 1.0% monthly rent-to-value, versus roughly 0.4% to 0.55% for a single-family rental. That’s the whole story of this market: doors drive coverage, not price. These are new-build asking averages and my modeled inputs, so older duplex rents may run lower.
Picture an investor holding a duplex appraised near the median, with both units modeled at the Apartments.com two-bedroom average. Full-PITIA coverage runs around 1.5x at the 75% ceiling. The binding constraint flips here. On the single-family house, the coverage ratio limits what you can pull. On the duplex, coverage clears with room, so the 75% LTV cap and the appraisal become the limit. That is a better problem to have. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Inventory supports the scarcity angle. Homes.com showed four multifamily listings with an entry price of $299,900 (the listing set includes a property outside Foley, so treat the range loosely). Redfin separately showed three multifamily units for sale against 65 homes sold. A building priced about like a house and carrying two or three rents is the whole thesis.
Past four units, you generally move into commercial or multifamily financing, and that’s a different article.
Newer Small-Lot Single-Family Near the Corridor
New-construction single-family in ZIP 36535 spans a wide band, per Zillow’s new-home listings: from $244,990+ for a 3-bed, 1,474 sq ft plan up to $422,490 for a 3-bed, 2,060 sq ft home. The low end of that band is where single-family rent-to-value starts to work.
Model a three-bedroom valued near $265K against the $1,799 asking rent: about 0.68% monthly, and coverage around 1.15 at a 75% cash-out LTV with taxes and insurance included. Clears 1.00, but without the cushion a duplex gives you. One more flag: builder incentives and competing new inventory can cap the resale comps your appraiser pulls, which limits proceeds. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
The build-to-rent segment sets the quality bar here. Allier Foley markets itself as a private build-to-rent community of one-, two-, and three-bedroom homes, so your older small-lot rental competes with purpose-built product.
Where Equity Comes From When Prices Sit Flat
With the median up just 2.1% and days on market lengthening, a Foley cash-out is a purchase-discount or forced-appreciation story, not a market-lift story. Size the refinance on the appraised value, never on rising comps.
That matters because seasoning clocks start at title recording, with about six months of ownership typical before cash-out. If you bought a dated duplex under value, renovated, and re-leased at stronger rents, the appraisal is where that work gets recognized. If you bought at the median and waited for the market to do the lifting, there may be little to extract.
The 75% LTV ceiling is a hard cap on cash-out, not a target, and available equity depends on rent used for lender review, PITIA, and reserves, typically about six months of PITIA. Reserve and credit guidelines vary by borrower and scenario, with a 620 credit floor on most files. Loans run up to $3,000,000 on standard programs. For the mechanics, see the equity-extraction mechanics and the refinance pathway for investor properties.
Lendmire’s deal desk sees a consistent pattern in thin-comp, mixed-stock markets like this one. The cleaner files tend to bring a signed lease or rent schedule up front and an appraisal request that anticipates sparse comps. The common friction point is a small-multifamily appraisal that comes back on single-family comps because nothing closer sold recently. Investors who gather lease evidence and nearby sales before the file goes to the lender usually avoid the re-work.
Submarkets: Where Rent Holds and Where Supply Is Landing
Prioritize the hospital area, the retail node, and the established downtown core. Treat the Beach Express corridor as the growth spine with the most new-build competition, so underwrite rents conservatively there.
Beach Express and Highway 98. This is the growth corridor. The Foley Sports Tourism Complex and OWA sit on it, and Business Alabama describes OWA as a joint venture between the Poarch Band, the city, and the sports complex, which has 16 soccer fields and a 90,000-square-foot indoor facility. The demand story rests on year-round event and hospitality jobs. Now the caution. The Grove at Foley Beach is an 180-unit workforce housing complex, 18 to 24 months from completion per Fox10, and the same report says rents will run around 30% below market. Gulf Coast Media puts the project at about $60 million. A 336-unit multifamily proposal on nearly 25 acres near the Beach Express is on a planning agenda, per OBA. Workforce rents near the corridor face real new-supply pressure.
Magnolia Walk. This subdivision covers 89.2 acres of newer master-planned housing (same OBA report). It’s a newer-stock rental pool, and no reliable neighborhood rent data exists, so pull comps yourself.
The McKenzie Street hospital area. This is the steadier workforce node, covered below.
Downtown Foley. Older stock in a walkable core with a recent renovation. I found no price or rent data, which makes it a duplex-hunting ground only if local comps back it up.
Tanger and the Highway 59 retail node. The Tanger Outlet Center has nearly 600,000 square feet of stores, per the City of Foley economic development page. That page is dated, so treat it as qualitative. It anchors retail employment, and retail workers rent.
Who Rents Here, and Why It Holds Up
Foley’s long-term demand comes from a mix of healthcare, hospitality, retail, and aerospace employment, not from beach seasonality alone. The city’s population is 24,026 across 35.3 square miles, per Census Bureau QuickFacts, and the City of Foley demographics page shows growth from 17,607 to 22,063 over several years.
Named employers on the economic development page include Collins Aerospace (formerly UTC Aerospace Systems), South Baldwin Regional Medical Center (now Baldwin Health), Vulcan Inc., Ascend Materials, and Riviera Utilities. The City of Foley describes the hospital as an 112-bed acute-care facility with more than 800 employees, expanding to 142 beds. The expansion figure has been cited at roughly $186 to $200 million. Expansion means clinical and construction staff, which supports renter demand and a stable-income story for the lender. The Poarch Band employs 6,000 people statewide, mostly in hospitality, per Gulf Coast Media.
WKRG reports the workforce project targets renters such as nurses, nursing assistants, welders, and construction workers. That is the same tenant pool your duplex competes for, only with a subsidized-rent competitor next door.
What to Watch Over the Next 6 to 24 Months
Five indicators decide whether Foley equity expands or stalls.
1. Days on market. Movement from 64 to 95 is a softening signal. If it keeps climbing, appraisers lean conservative.
2. The Grove’s delivery. Rents around 30% below market will pull on the low end of the rental pool once it opens.
3. The 336-unit proposal. If it advances, new-build competition near the corridor increases.
4. Hospital expansion progress. Added staffing supports demand in the McKenzie Street area.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Foley, AL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
5. Builder incentives. Rising incentives cap resale comps on the new-build single-family band.
The strong play is probably the older or small-multifamily asset where you can show rent evidence, not the newest unit near the corridor. Investors chasing appreciation could argue the other way, but flat pricing makes that a harder bet to defend.
Where does the cash go? Proceeds from a Foley refinance typically become the capital for the next acquisition, ideally another door-dense building. If holding in an LLC, eligibility is subject to lender program eligibility. For the baseline, see the guide “What Is a DSCR Loan”, which covers DSCR loans and DSCR versus conventional. Investors can reach Lendmire at 828-256-2183 or request a scenario quote. The state hub, Lendmire’s Alabama DSCR loan programs, covers broader program fit. One general reminder: verify current local rental rules, taxes, and insurance with qualified local professionals before committing.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Foley, Alabama?
Qualification centers on the property’s rent versus its full PITIA, with 1.00 as the common benchmark, though some lenders review lower ratios with compensating factors. Most files also need about six months of seasoning, credit at or above a 620 floor, and roughly six months of reserves. Eligibility depends on lender guidelines, credit approval, and property review.
What are the requirements for an investment property loan in Foley, Alabama?
Expect a 1-to-4-unit eligible property, documented or appraised rent, credit in the program’s tiers (620, 660, 680, 700), and reserves. Manufactured homes, log homes, and barndominiums fall outside the network’s programs. The 6% mobile-home share in Foley won’t qualify.
Are duplexes worth the hunt in Foley?
Yes, if you can verify local rent comps. Small multifamily is about 5% of stock, and a building near the $299,900 listing entry can carry more than one rent. The tradeoff is appraisal risk, since sparse comps can pull value toward single-family sales.
Will new workforce housing hurt Foley rents?
It can pressure the low end near the corridor. The Grove is 180 units with rents reported around 30% below market, and a 336-unit proposal is pending. Older or small-multifamily product away from the new supply tends to feel it less, though that depends on the specific building.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a DSCR-focused mortgage brokerage (NMLS# 2371349) that places investor loans across 41 markets, including Washington, D.C. Lenders generally review DSCR eligibility around a property’s rental income instead of personal income documentation, which suits LLC-held rentals, self-employed investors, and portfolios scaling past conventional financed-property limits. Lendmire has been recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a 2025 Scotsman Guide Top Workplace.
Before sizing any Foley refinance, pull three recent lease comps within a mile of the building and set them against the new-build asking averages; that gap decides how much equity this market will let you extract.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. NeighborhoodScout, Foley real estate
2. Redfin, Foley housing market
3. Homes.com
5. City of Foley, Baldwin Health article
6. Apartments.com, Foley recent builds
7. Redfin’s ZIP 36535 listings
9. Redfin
10. Zillow’s new-home listings
11. Business Alabama
12. Fox10, Grove at Foley Beach
13. gulfcoastmedia.com — Officials Break Ground on New Workforce Housing Complex in Foley
14. OBA, Foley Planning Commission
15. City of Foley economic development page
16. Census Reporter, Foley profile
17. City of Foley demographics page
18. Baldwin Health
19. Gulf Coast Media
20. a 2026 Scotsman Guide Top Mortgage Workplace
21. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Foley, AL · Investment Property Cash-Out Refinance in Alabama
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.