
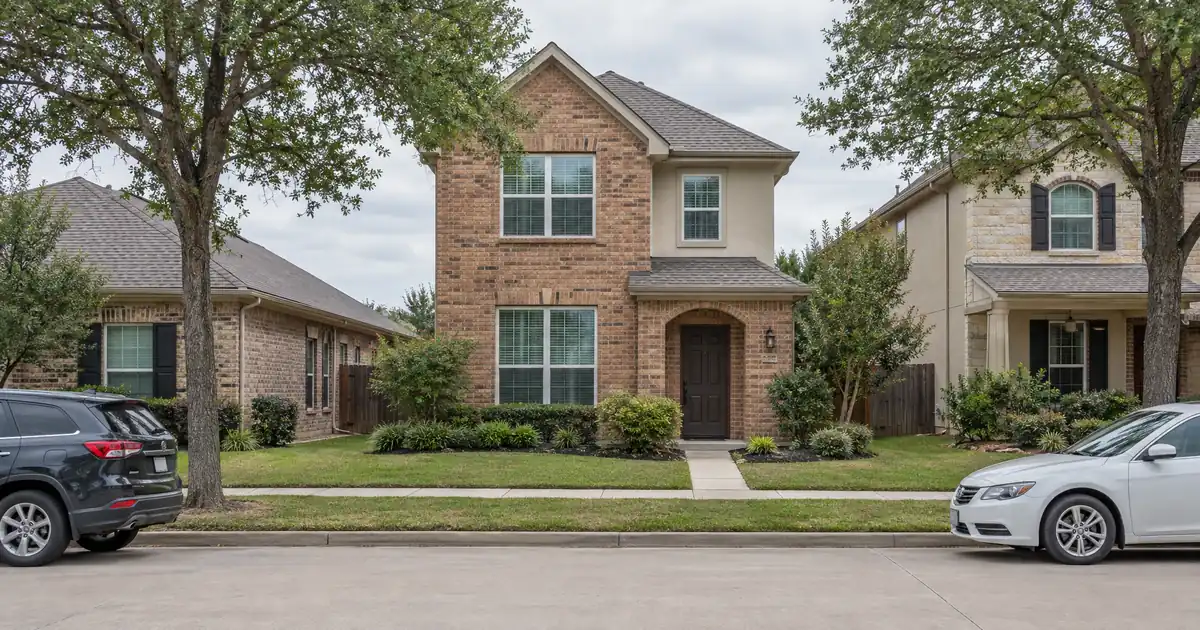
ZIP 75035, central and east Frisco, is one of the lower-priced pockets in a city where nothing is cheap. Redfin shows a $616K median there, down 2.2 percent year over year, with homes averaging 44 days on market versus 36 a year earlier. That is a market where sellers are negotiating, and it should change how you think about pulling equity out of a Frisco rental. Buyers are getting concessions, and appraisers see the same comps you do.
DSCR Cash-Out Calculator
Run the cash-out numbers in Frisco, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A cash-out refinance on a Frisco, Texas rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, including taxes and insurance, then capped by a 75 percent loan-to-value ceiling and reviewed subject to lender guidelines and appraisal.
- Sub-1.00 coverage is the normal starting point on Frisco houses at 75 percent leverage.
- Prices are down 6.0 percent year over year per Redfin, so run appraisal risk before you count on equity.
- Seasoning is about six months from title recording.
- Reserves of about six months of PITIA are typical.
- Townhomes and smaller houses fit better than large executive homes.
Frisco Market Snapshot
A quick read on the Frisco investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $1,496 average (CRE Daily (citing Transwestern)) |
| University enrollment | ~44,000 unt students (Collin College) |
| Employment | 3,100+ jobs (Frisco EDC via PR Newswire) |
| Vacancy | 12.2% (Matthews (CoStar data)) |
The Equity You Think You Have
Frisco is not appreciating right now, and any cash-out plan that assumes it is will get burned. Redfin puts the citywide median sale price at $655,066, down 6.0 percent year over year. Zillow’s home value index shows a typical value of $673,986, down 2.7 percent. The two sources measure different things, so treat the gap as a range rather than a conflict. Both point the same direction. A Redfin page from a few months earlier showed homes averaging 70 days on market versus 55 the year before.
That matters because the equity most Frisco owners feel comes from the 2021 to 2022 run-up. Frisco’s population grew from 44,592 in 2000 to an estimated 245,470, per the Frisco Economic Development Corporation. That is roughly 450 percent growth, and it slowed to about 3 percent a year in recent years. A city approaching build-out with cooling prices is a stability story, not a momentum story.
Picture an investor who bought a Frisco townhome before the peak and is sitting on a paper gain. The cash-out loan sizes off a fresh appraisal, not the number in the owner’s head. If comps have slid a few points, the 75 percent ceiling applies to a smaller base. Equity available depends on the appraised value, rent used for lender review, PITIA, reserves, and that ceiling. It is not a guaranteed cash figure. Investors who pulled cash at the top and used it to buy elsewhere did fine. Investors waiting for one more leg up are now waiting on a flat-to-soft market.
Where the Coverage Math Breaks
Frisco rent-to-price is thin, and the debt coverage ratio on a typical house starts below 1.00 at standard cash-out leverage. A local property manager, McCaw Property Management, pulled 499 single-family rentals and found 172 leased in the prior 30 days at a median rent of $2,990, in a median of 28 days, at 100 percent of asking. That is a manager’s sample, not an official dataset. Against the $655,066 Redfin median, it works out to about 0.46 percent of price per month, or roughly 5.5 percent gross annually. That figure mixes two sources and nets out no expenses.
Run the numbers this way, as a modeled illustration and not a market fact. Take a median-priced house at that median rent, a 75 percent cash-out, and full PITIA including taxes and insurance. Coverage lands around 0.65 to 0.70. Drop leverage to 50 percent and it improves toward the high 0.80s, still short of 1.00. Frisco houses at typical investor leverage don’t clear the standard 1.00 benchmark on long-term rent alone.
Rent sources also disagree, which is its own warning:
| Source | What it measures | Figure |
|---|---|---|
| McCaw | SFR leases, 30 days | $2,990 median |
| Zillow | All property types | $3,000 average |
| Zumper | All listings | $2,700 average |
| RentCafe | 50+ unit apartments | $1,788 average |
Zillow’s rental data rates the market “COOL.” Zumper shows rents up 6.9 percent year over year, while RentCafe shows apartment rents down 3.81 percent. Rent direction is contested. Call it mixed to flat and underwrite at in-place lease rent, not projected increases. The appraiser’s market rent schedule may also land below asking.
When coverage comes in under 1.00, the options are structural. You can reduce leverage and take less cash out. You can ask about interest-only structuring, which lowers the monthly obligation the ratio is measured against. You can ask whether a sub-1.00 program is available. Some lenders review those files, but expect stronger credit, more reserves, and tighter leverage. Every path is subject to lender guidelines, credit approval, and property review. Lendmire’s DSCR walkthrough covers the ratio mechanics if you want the formula.
Which Frisco Product Refinances Cleanly
Smaller single-family homes and townhomes are the workable DSCR products in Frisco, because a lower basis improves rent-to-price versus a large executive home. That is an inference, not a sourced neighborhood ranking, and no source I found ranks Frisco submarkets by cash flow. Treat everything below as directional and pull current MLS comps before deciding.
McCaw’s data hints at where tenant demand concentrates. Homes of 2,500 to 3,000 square feet leased at a median of 19 days, while homes over 3,500 square feet took a median of 36. Big houses carry the highest purchase prices and the thinnest coverage, and they sit longer between tenants. Skip them for cash-out plays.
Multi-unit stacking is not a Frisco strategy. Redfin listed only 3 condos, 78 townhouses, and 2 multi-family units for sale in one snapshot of the city, an undated page, so use it as a directional indicator. If you want duplex or fourplex math, that lives in other DFW submarkets, not here.
The submarkets that do have data are thin:
- ZIP 75035. The most useful data point, with the $616K median and softening days on market above. The refinance case is about stability here, not yield. – Richwoods. Redfin shows a $911K median, but only 4 homes sold that month. Use it as a high-end marker, not a comp set. – Stonebriar, Phillips Creek Ranch, Austin Ranch, Westridge, Sunset Pointe. Redfin’s rental table runs from $1,605 to $5,050 in median rent. That spread suggests apartments and houses are mixed together, and the data is a year old. Do not quote these as house rents. – Downtown Frisco, The Star, and the PGA district. These are demand anchors, not proven cash-flow areas. Buying near them is a lifestyle and tenant-quality thesis. It does not fix the rent-to-price ratio.
Silver Line rail stops come up in secondary sources as a possible pivot toward townhomes and condos. The timeline isn’t verified, so treat it as an upside narrative, not an underwriting input.
Will New Apartments Undercut Your Rent?
Frisco has a supply problem in apartments, and it presses on single-family rents. Transwestern data reported through CRE Daily showed Frisco leading the DFW metro with 8,314 apartment units under construction, while absorbing 2,381 units. Metro occupancy was 93.8 percent.
Compare that with Matthews, using CoStar data. It put DFW apartment vacancy at 12.2 percent and said suburban submarkets with heavy new supply, Frisco/Prosper among them, are under the most pressure. It projected vacancy peaking before gradually tightening. Those two sources use different definitions and aren’t directly comparable, but neither describes a landlord’s market. The Dallas Fed added that Texas apartment vacancy improvement came largely from increased concessions, flexible lease terms, and more pricing, and that some of the oversupply is luxury, high-priced product.
Here’s the practical read. Concessions on new apartments pull renters away from houses at the margin. Renters are only 34 percent of Frisco households, per RentCafe (26,330 renter-occupied versus 50,878 owner-occupied), so the tenant pool is smaller than in a typical urban market. Underwrite with a vacancy cushion, and don’t assume asking rents hold. One DFW lender guide claims Frisco sees multiple offers regularly. The cooling data above says otherwise.
Tenant Demand That Holds Up Anyway
Frisco’s tenant base rests on corporate offices, sports and entertainment, healthcare, and education. That supports re-leasing and retention, even though it doesn’t fix the coverage math. The Frisco EDC reports 14 corporate office relocations and expansions in its latest fiscal year, expected to create or retain more than 3,100 jobs. It also cites 10 master-planned mixed-use developments projected to add at least 10 million square feet of office space over 15 years. Those are promotional projections. Read them as direction, not as headcount you can bank.
The anchors are unusual for a city of about 245,000. The Frisco EDC calls it Sports City USA, home to the Dallas Cowboys, FC Dallas, the PGA of America, the Dallas Stars, and more than a dozen professional and collegiate sports organizations across five major stadiums. The PGA Frisco campus covers 600 acres and includes the 500-room Omni PGA Frisco Resort, per Visit Frisco. Keurig Dr Pepper moved its Texas headquarters to The Star, designed for roughly 1,100 employees. Frisco ISD is a major local employer, though no official headcount table exists, so no number is cited here.
Education adds a steady tenant layer. UNT at Frisco lists 3,330 current students, and Collin College’s Frisco campus has a Health Sciences Center under construction. Named healthcare facilities include Baylor Scott & White Medical Center – Centennial, Medical City Frisco, Texas Health Frisco, and a Baylor Scott & White sports medicine center at The Star. No official employee counts turned up for those.
Employment anchors like these help a lender narrative and tenant retention. They do not change the coverage ratio. Frisco is a stability and appreciation-optionality market, not a yield market. That contrasts with DFW submarkets like Garland and Mesquite, which one lender guide describes as having investment properties below $200,000 with strong coverage. Those are cash-flow plays, and they tend to be where extracted Frisco equity does more work.
Seasoning, Leverage, and Where the Proceeds Go
The cash-out mechanics are simple, and the constraints are firm. Lendmire’s programs generally look for about six months of ownership, measured from title recording, before a cash-out. The ceiling is 75 percent LTV, and a purchase-style 80 percent doesn’t apply to cash-out. The minimum coverage benchmark is 1.00 on rent used for lender review versus PITIA. Credit tiers run 620, 660, 680, and 700, with 620 as the floor. Reserves are about six months of PITIA, rising to about nine above $1,500,000. Loan amounts run up to $3,000,000 on standard programs, with smaller balances routed through select lenders in the network. All of this is guidance, subject to lender guidelines and program terms, and not a commitment to lend. The cash-out refinance walkthrough breaks the sequence down, and the refinance side covers rate-and-term alternatives.
Here’s the pattern from deal-desk work in markets structurally like this one: high-price, thin-rent suburbs. The cleaner files tend to be the ones where the borrower arrives with a signed lease at market rent, a fresh insurance quote, and a realistic view of the appraisal. The common friction point is the gap between what an owner assumes the house is worth and what a cooling market will support, plus a rent schedule that comes in under asking. Files that model leverage down to where coverage clears tend to move more smoothly than files built on optimistic value and rent.
Take the redeployment question seriously, because it’s the point of a cash-out. Cash pulled at 75 percent leverage on a sub-1.00 Frisco rental buys a property somewhere that has to carry itself and, ideally, carry the Frisco house too. If the new deal doesn’t cover comfortably, you’ve stacked thin coverage on thin coverage. The stronger play might be extracting less than the maximum and putting it into a higher-yield DFW submarket. Investors who want appreciation exposure in Frisco could argue for the opposite, leaving equity in place. This one is a genuine toss-up, and it depends on your other holdings.
One reminder, once: verify current local rental rules, property taxes, and insurance with qualified local professionals before you commit.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance on a Frisco rental?
The property’s rent used for lender review has to cover its full monthly obligation (principal, interest, taxes, insurance, and any HOA dues), with 1.00 as the standard benchmark. Typical guidance also includes about six months of seasoning, a credit score of at least 620, and about six months of reserves. Because Frisco rent-to-price runs around 0.46 percent, many houses need lower leverage to clear. All of it is subject to lender guidelines and appraisal.
DSCR vs. conventional financing
Two common ways to finance an investment property in Frisco, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan refinance in Frisco, Texas?
Expect a signed lease or market rent schedule, a fresh appraisal, proof of insurance, and reserves. Leverage tops out at 75 percent LTV on cash-out. Loan amounts run up to $3,000,000 on standard programs. The property must be an eligible type, so manufactured homes, log homes, and barndominiums fall outside these programs. Final eligibility rests with the lender.
Can I pull equity from Frisco if prices are falling?
Yes, but the amount depends on the new appraisal, not your purchase price or an old estimate. With Redfin showing a 6.0 percent year-over-year decline and Zillow showing 2.7 percent, value can come in below expectations. That shrinks the base the 75 percent cap applies to. Owners with a low basis or older purchases usually have the most cushion.
Do Frisco townhomes cover better than large single-family homes?
Generally, yes, though no source ranks Frisco properties by coverage. Lower purchase prices improve rent-to-price versus executive homes. McCaw’s data also shows homes of 2,500 to 3,000 square feet leasing at a median of 19 days versus 36 for homes over 3,500 square feet. Pull current comps for the specific product.
How does DSCR program review differ from a bank’s approach in Frisco?
Eligibility review centers on the property’s rent versus its obligations rather than traditional personal-income documentation, subject to program terms. Cash-out leverage tops out at 75 percent LTV.
Before You Pull the Cash
Frisco rewards patience more than it rewards leverage: a corporate-and-sports tenant base, prices in retreat, and rents that don’t quite carry the debt. So which is it for your Frisco property: is the equity worth more sitting in the house, or working in a market where the rent actually covers the payment?
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) arranges investor financing across 41 markets, spanning 40 states plus Washington, D.C. DSCR eligibility is generally reviewed by the lender on property cash flow rather than traditional personal-income documentation, subject to lender guidelines. Lendmire was named a 2026 Scotsman Guide Top Workplace and was recognized by Scotsman Guide in 2025.
For broader investor-financing rules and property-type coverage across the state, see Texas DSCR loans.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
3. CRE Daily (Transwestern data)
8. Frisco Economic Development Corporation – Demographics
9. McCaw Property Management – Frisco rental market
11. Zumper
12. RentCafe
13. Dallas Fed
14. Frisco EDC
15. Visit Frisco
16. UNT at Frisco
17. Collin College’s Frisco campus
18. a 2026 Scotsman Guide Top Workplace
19. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Frisco Texas · Investment Property Loans in Frisco, TX: Will Local Rents Cover the Mortgage? · Cash Out Refinance Investment Property Waco Texas
Guides: Investment Property Cash-Out Refinance in Frisco, TX · Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.