
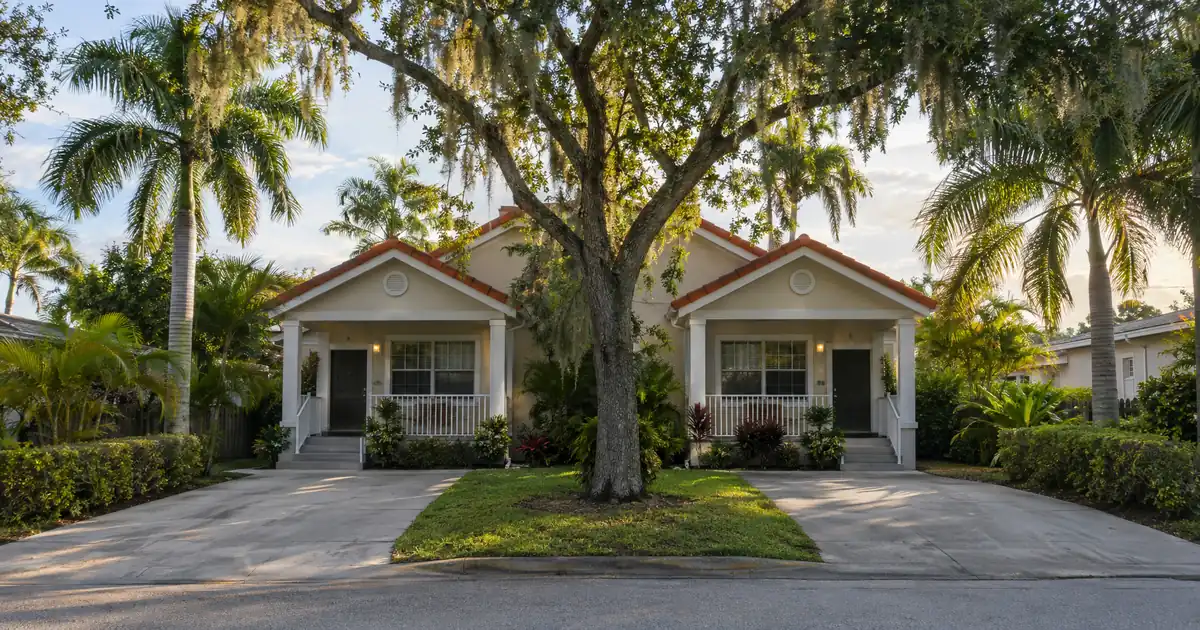
Two Hialeah investors own rentals bought around the same time. One holds a single-family house in Hialeah Acres, where Redfin puts the median sale price near $600K and Redfin’s rental data lists median rent at $2,600. The other holds a three-bedroom condo in Downtown Hialeah, where Redfin’s Downtown comps show recent sales at $317,000 and $330,000. The first owner has more equity on paper. The second has more cash flow. For a DSCR cash-out refinance, the math favors the second.
Lendmire (NMLS# 2371349) is a non-QM mortgage broker, and its DSCR program footprint covers Hialeah, Florida as part of a 41-market reach that includes Washington, D.C. This report focuses on the owner who already holds the property and wants to pull equity out. It skips purchase mechanics.
DSCR Cash-Out Calculator
Run the cash-out numbers in Hialeah, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
At a Glance: A DSCR cash-out refinance on a Hialeah rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with loan-to-value capped at 75% and roughly six months of ownership typically expected. Lender guidelines, credit review, and the appraisal determine how much equity, if any, is accessible.
- Downtown condo sales at $317K–$330K sit against citywide 3BR asking rents above $2,700.
- Hialeah Acres houses near $600K rent for about $2,600. Modeled coverage lands well under 1.00x.
- Citywide price data conflicts: Zillow’s $443,804 versus an MLS-based $535,000.
- Cash-out tops out at 75% LTV after about six months of ownership.
- Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Hialeah Market Snapshot
A quick read on the Hialeah investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $493,888 median sale (Broker One Hialeah trends) |
| University enrollment | 2,638 students (Florida National University) |
| Population | 235,384 population (Census Reporter (ACS) Hialeah) |
| Employment | 900+ employees (Hialeah Hospital) |
Hialeah Is Two Markets, Not One
Hialeah splits into equity-rich houses with thin rent coverage and low-basis condos with thick coverage. Investors who treat the city as a single market misjudge both. Appraisers, lenders, and rent comps all behave differently on each side of the split.
Start with the price data, which disagrees with itself. Zillow’s home value index puts the citywide figure at $443,804, down 3.0% year over year, and this report uses that number as its reference. Momentum’s MLS-based page shows a median sale of $535,000, down 2.8%, a gap that reflects different methods and different mixes of property types. Neither source shows a city in a hurry to appreciate.
The type spread matters more than the median. Broker One reports a median house list price of $669,800 against $264,990 for condos and co-ops. A $400K gap between the two tiers is where coverage gets made or lost.
Rent data disagrees too. Zumper reports a median of $2,350 for all property types and flags rents falling year over year, though that figure is a noisy listing median. RentCafe puts the apartment average at $2,185, down 1.54%. The census-based median gross rent sits lower, at $1,913 per city-data.com, because it captures older in-place leases. Underwrite to today’s rent, not the legacy number.
Where the Coverage Math Clears
Coverage is strongest where purchase basis is low and rent is citywide-average or better. Downtown condos and the west-central workforce pocket lead. The pricier single-family pockets trail.
Downtown Hialeah (ZIP 33010). Three-bedroom condos traded at $330,000 and $317,000 in the Redfin comps. Citywide 3BR asking rents run at least $2,714, per Apartments.com. That works out to roughly 0.85% monthly rent-to-price, about double Hialeah Acres. Modeled at 75% LTV on a 30-year amortizing structure, including taxes and insurance, coverage lands around 1.2x to 1.3x before HOA dues. That is an assumption-driven estimate, not a quote. The rent is also a citywide figure, not a condo-specific comp. Condo eligibility rules and HOA dues vary by lender and can shift the number in either direction.
ZIP 33012 (west-central, near Florida National University). This is workforce single-family and small multifamily territory. Momentum’s ZIP scorecard estimates a home value of $383,648 and a gross yield near 7.12%. The yield is model-based, so treat it as directional.
ZIP 33018 (northwest, near the Palmetto Expressway). Newer stock costs more. Momentum’s scorecard shows $530,640 and an estimated gross yield near 6.4%. Coverage is thinner than in 33012, but the collateral is newer.
Hialeah Acres. Skip it for standard-leverage cash-out. Rent of $2,600 against a $600K price is a 0.43% ratio. Modeled with taxes and insurance, coverage lands near 0.7x. That doesn’t clear the 1.00x benchmark most programs are built around. Options a lender may review include lower leverage, an interest-only structure, or a no-ratio product. Each typically carries tradeoffs in pricing or cash required, and eligibility depends on credit, reserves, and property review. Rent.com shows 1BR averages of $1,900 here versus $1,600 in East Hialeah, so the premium is real. The yield isn’t.
Other rent markers: Rent.com lists 1BR averages of $1,550 in Essex Village and $1,675 in Westhaven Heights. RentCafe’s averages for buildings of 50-plus units put Century Gardens at $2,589 and Villa Hialeah-Cerdas at $1,899. Large-building numbers are not a proxy for small-building rents.
The Duplex Question
The brief found no sourced duplex, triplex, or fourplex pricing or rents for Hialeah. Anyone who quotes you precise small-multifamily yields is guessing. The structural case still holds. Older concrete-block two-to-four-unit buildings dominate East and West Hialeah, and the city packs about 12,233 people per square mile, per city-data.com. Dense, transit-served, older stock is what small multifamily looks like.
Working DSCR brokers see a recurring pattern in dense, older-stock markets like this one: multi-unit files clear coverage more easily than single-family files at comparable prices, because several rents stack against one set of taxes and insurance. The friction moves to the unit count. Appraisers and lenders want to see legal, permitted units, and a rent roll that includes an unpermitted third unit tends to get discounted or excluded.
Run the numbers on a hypothetical. Picture an investor holding a paid-down older duplex in East Hialeah near the Metrorail station at Palm Avenue and E 21st Street. Both units rent at market. Stacked rents against a single mortgage payment typically produce stronger coverage than a single-family home at the same value. At a 75% LTV ceiling, coverage, not equity, is usually the binding constraint. Verify legal unit count, current local rental rules, taxes, and insurance with qualified local professionals.
What Keeps Tenants Paying
Rental demand in Hialeah is anchored by jobs and transit, not by a campus. That favors long-term workforce leases.
Healthcare is the clearest anchor. Hialeah Hospital is a 378-bed facility with more than 900 employees, and Palmetto General Hospital is the second in-city acute-care hospital. Ownership of both has changed hands; Tenet sold them to Steward in an August 2021 transaction. Retail, logistics, and manufacturing fill out the base. Florida National University runs its main campus here, with roughly 2,600 students, though it is too small to drive student-housing demand.
Transit widens the pool. Miami-Dade’s Metrorail serves Hialeah and Medley with connections to MIA and downtown Miami. Point2Homes reports that two-bedroom units make up 45% of rentals.
There is also a supply signal. According to the city’s annual financial report, the western annexation area, about 1,920 acres, had seen roughly 4,000 residential units, about 16,000 residents, and 8 million square feet of industrial space completed as of that report. Two multifamily projects sat in the pipeline, at 244 and 617 units. New supply at the western edge competes with older stock for renters. That is a vacancy risk. The brief found no reliable Hialeah rental vacancy rate.
Seasoning, Leverage, and the Appraisal Problem
The binding constraints on a Hialeah cash-out are the 75% LTV cap, about six months of seasoning, and an appraisal that may come in conservative. Equity is not cash until all three line up. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
The program basics, which vary by borrower, property, and lender guidelines: seasoning runs about six months from title recording, and the cash-out LTV ceiling is 75%. Coverage has a 1.00x baseline against the full payment, which includes taxes and insurance. Credit tiers start at a 620 floor. Reserves are typically about six months of PITIA. Standard programs go up to $3,000,000, and smaller balances route through select lenders in the network. For more detail, see the DSCR qualification mechanics and cash-out refinance details.
Appraisals are the softer risk. Per Redfin’s city data, days on market hit 75 versus 65 a year earlier, and sales fell to 73 homes from 79. Broker One counts 821 active listings, up 59% year over year. Few recent sales means few comps, and an appraiser working from thin data tends to value conservatively. Downtown condo sales closed as much as 18% under list, which does not help.
The stronger play may be a patient one. Wait for the seasoning window, pull a fresh rent estimate, and size the ask below the cap rather than at it. Investors expecting appreciation to fill the gap are betting against a flat-to-softening market. Price direction is ambiguous. Rent direction is not. Apartment List shows median rent of $1,699, down 1.2% year over year.
Where the Proceeds Go
Cash-out proceeds are acquisition capital. In Hialeah that usually means one of two moves: trade up into a stacked small multifamily, or recycle equity into a lower-basis condo where coverage clears easily.
Consider a scenario in which an investor owns a workforce single-family home in ZIP 33012 and refinances at a conservative fraction of the 75% ceiling. The equity then supplies the down payment on a Downtown condo that cash-flows at 1.2x or better. That sequence is self-funding, and each step lowers the portfolio’s average basis per dollar of rent. Keep the refinance decision separate from the purchase decision, because the refinance side has its own qualification logic. Compare the structure against the conventional alternative if traditional employment income is part of the picture.
Investors ready to size a specific file can pull a DSCR quote or call 828-256-2183. Broader program context lives on the Florida DSCR financing page.
Frequently Asked Questions
How much equity can I take out of a Hialeah duplex?
Up to 75% of the appraised value, less the existing balance, is the ceiling. The real number is lower when rent doesn’t cover the full payment at that leverage, or when reserves fall short. Stacked unit rents make duplexes likelier to reach the cap than single-family homes.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Hialeah, FL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Will a Hialeah Acres single-family home clear 1.00x coverage?
At a $600K price and $2,600 rent, modeled coverage lands near 0.7x including taxes and insurance. That falls short of the standard baseline. A lower LTV, an interest-only structure, or a no-ratio product may be reviewed, each with its own tradeoffs.
Do I need six months of ownership before a cash-out?
Yes, roughly. Seasoning typically runs about six months from title recording. Buyers who renovate and refinance should plan the timeline around that window, and lender guidelines control the exact requirement.
Do Hialeah condos work for a DSCR cash-out?
Often, on coverage. Low-basis three-bedroom condos near $320K against rents above $2,700 produce the city’s best rent-to-price ratios. Lender condo-eligibility rules and HOA dues decide whether a specific building works.
Which rent figure will the lender use?
Depending on the program, lenders typically rely on the lease or an appraiser’s market-rent estimate, not listing medians. Hialeah’s rent sources range from $1,699 to $2,350 citywide, so the appraisal’s rent schedule matters more than any aggregator number.
The Bottom Line
If you only take one thing from this piece, it’s this: in Hialeah, coverage rather than equity sets your cash-out, so the low-basis condo or stacked duplex that clears 1.00x will outperform the pricier house with more paper appreciation.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR financing for real estate investors in 41 markets, made up of 40 states plus Washington, D.C. Because deals are underwritten primarily on property cash flow rather than personal income documentation, the structure suits self-employed buyers and entity-owned portfolios. Lendmire places loans through wholesale investor lenders; it is not a direct lender. The firm was recognized by Scotsman Guide as a 2026 Top Workplace and is a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Hialeah Acres housing market
3. Redfin: Downtown Hialeah housing market
4. Zillow: Hialeah home values
5. Broker One
6. Florida National University
7. Census Reporter (ACS) Hialeah
10. Zumper
11. RentCafe: Hialeah rent trends
12. Apartments.com
16. Miami-Dade County Metrorail
17. Point2Homes: Hialeah average rent
18. Apartment List
19. recognized by Scotsman Guide as a 2026 Top Workplace
20. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Hialeah Gardens, Florida: Equity Recycling for Workforce Rentals · DSCR Cash Out Refinance in Hialeah Gardens, Florida: Pulling Equity From a Built-Out Market · Cash Out Refinance Investment Property in Pinecrest, Florida: Can the Rent Support a Cash-Out in Pinecrest?
Guides: Investment Property Cash-Out Refinance in Hialeah, FL · Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.