
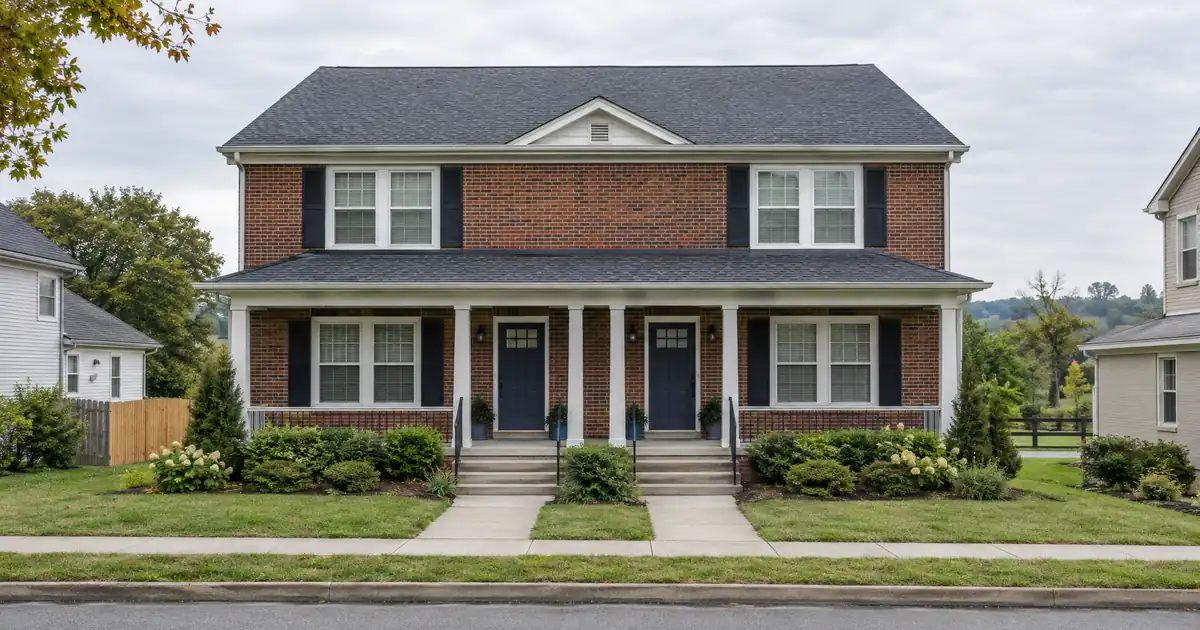
Picture two investors who each own a rental in Hopkinsville and each want cash out. One holds a three-bedroom house bought at the median. The other holds a brick duplex or fourplex bought on a low basis. The math favors the second investor, and it isn’t close. Single-family rent at the citywide median doesn’t carry a cash-out loan. Stacked doors on a cheap basis do.
At a Glance: A DSCR cash-out refinance in Hopkinsville, Kentucky is underwritten primarily on the property’s rental income measured against its full monthly obligation, then sized by appraised value, seasoning, and reserves. Property type drives the outcome more than any other variable.
DSCR Cash-Out Calculator
Run the cash-out numbers in Hopkinsville, KY
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Median rent is $937 per Homes.com, so median-rent single-family sits below 1.00.
- Cash-out loans cap at 75 percent LTV, with about six months of seasoning from title recording.
- Two-to-four-unit buildings on a low basis carry the best coverage.
- Thin sales volume makes the appraisal the file’s pressure point.
Investors in Hopkinsville, Kentucky work with Lendmire to place DSCR financing through wholesale lenders reaching 41 markets, including D.C. Lendmire is a mortgage broker (NMLS# 2371349), so it arranges the loan and the lender decides. Anyone comparing structures should read the guide “What Is a DSCR Loan” first, then come back for the local plumbing.
Hopkinsville Market Snapshot
A quick read on the Hopkinsville investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $235,000 median (Homes.com, Hopkinsville) |
| Employment | 2,500 jobs (Christian County Now) |
Why Single-Family at the Median Struggles
Median-rent single-family in Hopkinsville does not clear 1.00 on a cash-out. Homes.com reports a median rent of $937 and single-family rent of $1,150, against a median home price of $235,000. That works out to a gross yield near 4.8 percent, and it’s a writer-derived figure that mixes two sources.
Model the file the way a lender will, with rent divided by full PITIA, taxes and insurance included, at 75 percent LTV. A $937 rent on a $235,000 value lands around 0.65 to 0.70. Not close. Even the $1,150 single-family rent lands well short of 1.00.
The better single-family candidate is the 3BR/2BA. Redfin shows current asking rents of $1,350 and $1,499-plus for that product. Assume $1,350 on a $235,000 value and coverage runs just under 1.00. Assume $1,499 and it edges into the low 1.0s. Those are asking rents, not achieved rents, and the inputs here are modeled assumptions, not market facts.
That’s the honest read. A cash-out on median-stock single-family here is a sub-1.00 conversation. It usually means lower leverage, stronger credit, and a lender willing to look at sub-1.00 programs. Some select lenders may review those scenarios, but the file gets harder.
Where the Coverage Actually Lives (1-4 Unit Stock)
The strongest cash-out candidates are duplexes, triplexes, and fourplexes bought low. Homes.com’s multi-family page shows six multi-family listings priced from $109,900 to $1.3 million. One fully rented duplex produces $1,200 a month, each side a two-bed, one-bath. That’s roughly $600 a door. A four-unit building of two-bedroom units, all rented, is listed too.
Per-door rent is thin, so the stacking does the work. Run this modeled case: a duplex at $1,200 total rent, valued near the bottom of that price range, financed at 75 percent LTV. Including taxes and insurance, coverage runs comfortably above 1.5. Even if the appraisal comes in well above that low end, the ratio has real cushion. Compare that with a single-family house at the median. Same city, same loan program, very different file.
Skip anything with five or more units. A five-unit property or a 48-unit asset sits in commercial territory, outside the standard 1-4 unit DSCR box.
Balance size matters here too. Loans up to $3,000,000 fit standard programs, but Hopkinsville balances often run small, and smaller balances route through select lenders in the network. Ask about that early, before you’re attached to a structure.
Fort Campbell Is the Demand Story (and the Risk)
The renter pool here leans heavily on the Army post. A Kentucky Commission on Military Affairs briefing lists 27,100 active-duty personnel, 50,812 family members, and 6,429 civilians. That briefing is dated, so read it as scale, not a current headcount. A state-commissioned study, also dated, estimated that about 70 percent of soldiers and families live off the installation. Hopkinsville is the Kentucky-side entry point to that renter pool, generally at a lower price basis than Clarksville across the state line.
Now the caution, because a cash-out is a bet on the next several years, not the last several. TIP Strategies documents troop levels dropping from 31,092 to 26,500 in a two-year stretch. A force reduction hits occupancy first and appraised value second. Any investor pulling cash out on a Fort Campbell-corridor door should underwrite a soft patch, hold reserves, and avoid extracting to the last percent of the 75 percent cap.
Some balance exists. The South Western Kentucky Economic Development Council names Jennie Stuart Medical Center, the Wal-Mart Distribution Center, T.RAD North America, and Western State Psychiatric Hospital among its top employers. Jennie Stuart Health reports more than 100 physicians across more than 30 specialties. None of that offsets the post, but it spreads demand across health care, distribution, and manufacturing. The council’s 2030 plan targets 2,500 new jobs and over $3 billion in capital investment. That’s a target, not a forecast.
Housing-budget data adds one more angle. Area housing allowances for service members run well above Hopkinsville’s median rent, per a Fort Campbell housing blog. That suggests well-kept 3BR homes could plausibly price above the median. Still, Clarksville alternatives cap what Hopkinsville can charge, so underwrite conservatively. The lender’s rent schedule will.
What the Appraisal Sees
Hopkinsville has thin sales data, and that’s the friction point for equity extraction. Redfin showed a $259K median, up 10.2 percent year over year, but only 14 homes sold that month. Houzeo shows a median of $189,900 on 29 sales in a single month, with 102 days on market and a 4.2-month supply. Homes.com sits at $235,000. Three sources, a $70,000 spread.
Here’s what that means for a cash-out. Any appreciation figure for the city is a small-sample number, and a lender’s appraiser will pull comps from whatever closed nearby. This is a cash-flow-led, lower-basis market, so plan for modest cash-out equity rather than a big appreciation payout. Days on market shortened from 95 to 67 by Redfin’s count, which is a mildly encouraging read, still on a small sample.
The Cash-Out Mechanics (Plumbing, Mostly)
Cash-out here runs on four constraints, all subject to lender guidelines and property review:
- LTV ceiling: 75 percent on a cash-out. The 80 percent purchase figure doesn’t apply.
- Seasoning: about six months of ownership, measured from title recording. Buy on Friday and the clock still starts at recording.
- Coverage: a 1.00 baseline is common, since rent covers PITIA at that level. Some lenders may review lower or no-ratio scenarios, but those typically mean less leverage, stronger credit, or more cash in.
- Reserves and credit: about six months of PITIA in reserves, with a 620 credit floor and better positioning at 660, 680, and 700.
Run a scenario with percentages only. Say an investor owns a fourplex that appraises near the mid-$200,000s. The existing payoff sits at 60 percent of value. A 75 percent LTV ceiling leaves 15 points of value as the theoretical maximum before costs and reserves, and rent coverage may cut that further. That’s a ceiling, not a promised number. The calculator converts it to dollars, and the cash-out refinance walkthrough covers the sequence.
Working DSCR brokers see a recurring pattern in small, military-adjacent markets: the rent schedule and the appraisal drift in opposite directions. The lender’s appraiser pulls low-end comps for rent and thin comps for value, and the file gets short on both sides. Investors who show up with signed leases, a clean rent roll, and a payoff statement in hand tend to face fewer conditions than those who scramble after the appraisal lands.
Proceeds are capital for the next deal. Many investors here recycle them into another low-basis duplex, which is why the entry price matters more than the exit price. Compare the investment property refinance options and the guide “Where DSCR and Conventional Diverge” from conventional cash-out before deciding on structure.
Where the Files Pencil, by Submarket
Neighborhood-level price and rent data doesn’t exist in any source worth trusting here, so this is qualitative. Take it as direction, not data.
Fort Campbell Boulevard and South Hopkinsville. This is the retail spine toward the base, and the multi-unit listings marketed as minutes from post cluster around it. It’s the strongest submarket for the duplex and fourplex play, and it carries the most Fort Campbell exposure. Both facts cut the same way.
Downtown and the historic core. Older multi-unit stock lives here, including small multi-unit buildings near East 7th Street. The basis can be attractive, but older buildings raise condition-related appraisal risk, and lenders may add conditions. Not ideal for a first cash-out. Housing stock citywide skews old, with about 34 percent built between 1940 and 1969. Budget for property review.
South Christian and the I-169 area. This is newer single-family, roughly 15 miles from Gate 7 by a secondary guide’s measure. Newer construction appraises cleaner. Single-family coverage still needs a 3BR/2BA at the upper end of the asking-rent range to work.
Named rental pockets. Homes.com lists Plantation Estates, Avalon, Tylertown, Ringgold, and Bluegrass Downs as popular rental areas. Beyond the names, there’s no sourced data on any of them.
Rural fringe properties are their own problem. Acreage, or two homes on one deed, complicates eligibility, and lender rural policies vary. Manufactured homes, log homes, and barndominiums fall outside these programs entirely.
Rent Numbers That Don’t Agree
Nobody can hand you one Hopkinsville rent, and the lender’s number may be the low one. Homes.com says $937. Realtor.com data, as summarized by Haus Realty, shows a $1,050 median with 78 listings, down from a year earlier, in a market Haus calls active but not overheated. A third portal shows $843, but its dates conflict.
Underwrite to the lowest credible figure when estimating proceeds. Shrinking listing counts point away from oversupply, though no reliable vacancy rate exists for the city. Population is 30,906, with median household income of $49,139 versus $68,967 for the Clarksville metro. This is a workforce tenant base. Hopkinsville Community College enrolled 2,319 in fall, up from 2,028 three years earlier, but this isn’t a student-renter market.
DSCR vs. conventional financing
Two common ways to finance an investment property in Hopkinsville, KY. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Verify current local rental rules, taxes, and insurance with qualified local professionals before committing to any structure.
What Slows a File Down
(Rarely the loan program itself.) Delays in a market like this come from the plumbing: a rent schedule that doesn’t match the leases, a payoff statement with a stale figure, a title issue on a deed carrying two dwellings, an appraisal that needs additional comps because few homes sold nearby. Entity paperwork adds a step for LLC borrowers, subject to lender program eligibility.
Small-balance files add a wrinkle. Lender minimums can push a file toward a select lender rather than the standard program. That’s routing, not rejection. Coverage below 1.00 on a single-family door reshapes the file, and interest-only structuring or reduced leverage may come up in review. Qualification stays subject to lender guidelines, credit approval, and property review.
Investors who want the numbers on a specific building can see how the math pencils, or reach the Lendmire team at 828-256-2183. Lendmire’s Kentucky DSCR platform covers state-level program detail.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Hopkinsville, Kentucky?
Qualification centers on the property’s rent against its full PITIA, with a 1.00 baseline common and a 620 credit floor. Expect about six months of seasoning, about six months of reserves, and a 75 percent LTV ceiling. Lenders weigh the appraisal heavily here because local sales volume is thin.
What are the requirements for an investment property loan in Hopkinsville, Kentucky on a duplex or fourplex?
One-to-four-unit properties fit standard DSCR programs, while five-plus-unit buildings move into commercial territory. Lenders typically want a lease or market rent schedule, an appraisal, proof of reserves, and clean title. Smaller balances may route through select lenders in the network, subject to program terms.
How much cash can I pull out of a Hopkinsville rental?
It depends on appraised value, existing payoff, rent used for lender review, and reserves, capped at 75 percent LTV. Because Hopkinsville is a lower-basis, cash-flow-led market rather than an appreciation market, equity may be modest. It’s a ceiling, not a guaranteed figure.
Does Fort Campbell’s troop level affect a Hopkinsville cash-out?
Indirectly, yes. Lenders underwrite the property’s rent and appraised value, not the post. But troop reductions have hit local rental demand before, so investors should hold extra reserves and avoid extracting to the cap.
What can slow down a Hopkinsville DSCR cash-out refinance?
Thin comps, mismatched rent schedules, and title complications on multi-dwelling deeds are the usual culprits. Lendmire arranges DSCR investor loans and its programs qualify on rental income, subject to lender guidelines. A complete rent roll and payoff statement up front reduces lender conditions.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C., through wholesale and investor-lending channels. The lender evaluates DSCR loans on rental income rather than personal income, subject to lender guidelines, which suits LLC-owned portfolios, self-employed investors, and operators scaling past conventional loan caps. The firm was recognized by Scotsman Guide as a 2026 Top Workplace and named a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Homes.com, Hopkinsville rentals
2. Homes.com, Hopkinsville multi-family
4. Redfin
5. Kentucky Commission on Military Affairs, State of Fort Campbell
6. TIP Strategies, Fort Campbell growth plan
7. South Western Kentucky Economic Development Council, top employers
9. Redfin
10. Houzeo
11. pcspayitforward.com — Buying a Home Near Fort Campbell 2026 VA Loan Guide
12. Haus Realty
13. Census Reporter — Hopkinsville KY
14. Hopkinsville Community College
15. recognized by Scotsman Guide as a 2026 Top Workplace
16. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Kentucky
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.