
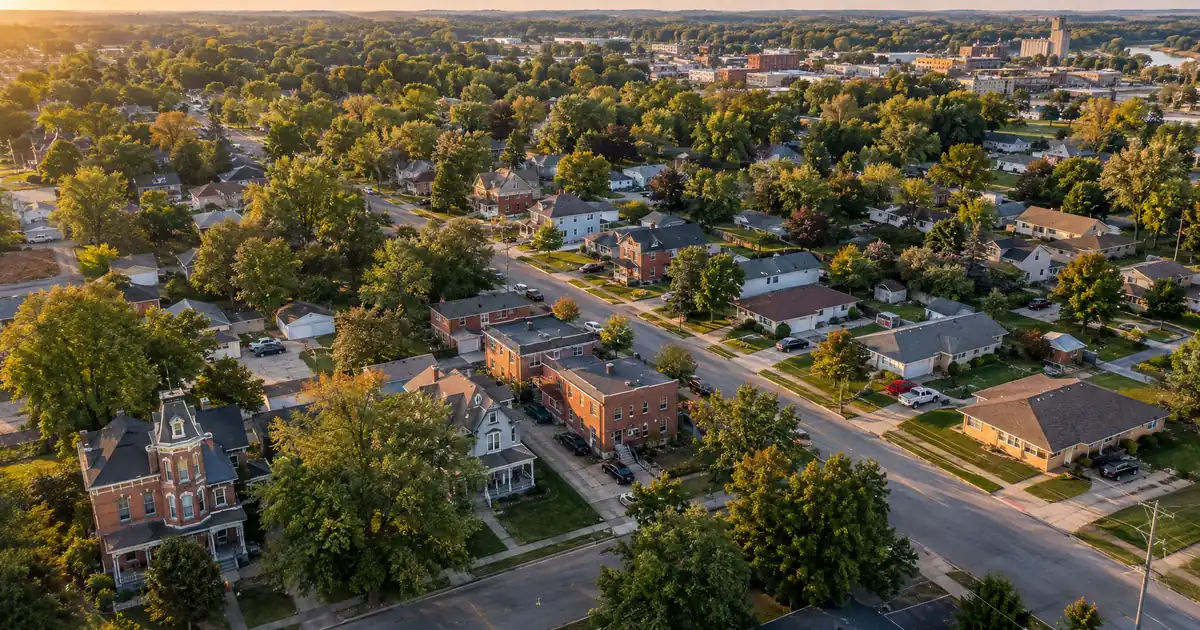
An out-of-state investor scanning Kokomo sees a $175K median price and rents that look strong next to it. Redfin puts the median at $175K, up 5.9% year over year. What that investor usually misses is that one industry cluster sets the tenant base. The other thing to ask is how much equity a house actually holds after the purchase. Appreciation is steady but modest here, so cash-out proceeds depend mostly on what the owner paid and what it cost to improve the property.
TL;DR: A DSCR cash-out refinance in Kokomo, Indiana is underwritten primarily on the property’s rental income measured against its full monthly obligation. Ownership seasoning, appraised value, and the LTV ceiling then determine how much equity can be returned as capital for the next deal.
DSCR Cash-Out Calculator
Run the cash-out numbers in Kokomo, IN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Typical guidance caps cash-out leverage at 75% LTV, with about six months of ownership seasoning.
- East Kokomo’s $90,690 median price against $1,142 average rent gives the widest coverage margin found (NeighborhoodScout).
- Houses near the citywide median land around 1.05-1.25 coverage, including taxes and insurance.
- Stellantis anchors demand, and StarPlus hiring is running well below its projection. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Kokomo Market Snapshot
A quick read on the Kokomo investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $90,690 median price (NeighborhoodScout) |
| Typical rents | $1,142 avg (NeighborhoodScout) |
| Employment | 3,200 construction jobs (U.S. Dept. of Energy) |
Where Does Coverage Clear 1.00 in Kokomo?
Coverage clears 1.00 comfortably on lower-priced houses and gets thin on houses priced above the citywide median. The math is simple. A DSCR lender divides monthly rent by the full monthly obligation (principal, interest, taxes, insurance, and any HOA dues). Most standard programs treat 1.00 as the baseline, though exact eligibility varies by lender, borrower, and property.
The modeled figures below assume a 30-year term at 75% LTV with taxes and insurance included. They are illustrations, not market data. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
| Scenario (modeled) | Rent input | Coverage read |
|---|---|---|
| East Kokomo house near $90,690 | $1,142 | Well above 1.5 |
| House near the $175K median | $1,377 (3BR) | Roughly 1.2 |
| Same house, lower rent survey | $1,095 | Roughly 1.05 |
| House near $245K | $1,377 (3BR) | Just under 1.00 |
Rents disagree by source, and investors should plan around the range. Rentometer shows 3-bedroom rents averaging $1,377, 2-bedroom at $1,015, and 4+ bedroom at $1,791. Zumper puts the median house rent at $1,095 against $850 for apartments. A local brokerage, T&H Realty Services, claims 3-bedroom homes rent for $1,150 to $1,300 against prices of $140,000 to $160,000. That is marketing copy, so treat it as a directional claim. Its implied rent-to-price ratio of 0.8% to 0.9% is tighter than the 1% the brokerage itself advertises.
The takeaway: the cheaper the house, the more forgiving the DSCR. A $245K house at market rent is a different file from a $100K one. Lendmire, a DSCR-focused mortgage broker, structures Kokomo files with that spread in mind. Lendmire (NMLS# 2371349) works with Kokomo, Indiana investors through a DSCR program footprint spanning 40 states plus Washington, D.C., and arranges the placement through wholesale lending channels. Lenders, not the brokerage, review eligibility and approve.
Equity Extraction, Not Appreciation Chasing
Kokomo’s appreciation is positive but not dramatic, so equity comes from basis. Buy below market or add value, then refinance at appraised value.
Prices are climbing at a measured pace. Zillow shows an average home value of $185,794, up 4.8% over the past year. The Indiana Business Research Center reported Howard County’s Zillow average at $174,900, up 52.1% over five years. Sources disagree on the level, so this article uses Redfin’s $175K median as the single citywide anchor and cites others only for trend.
Consider a scenario with modeled percentages only. An investor rehabs a house to a total cost basis near 65% of its appraised value. A refinance at the 75% LTV ceiling would then return all the invested capital and leave roughly 10% of value as surplus. Flip it around. An investor who paid full retail in a flat stretch may find the new loan barely clears the existing payoff. That’s a thin refi. Skip it until value moves. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Program guidance typically looks like this, subject to lender guidelines:
- Seasoning: about six months of ownership, measured from title recording.
- Reserves: about six months of PITIA in most cases.
- Credit: tiers generally vary by scenario, with pricing and leverage improving at 660, 680, and 700.
- Coverage: a 1.00 DSCR is the common baseline. Lower or no-ratio scenarios exist with some lenders but usually require lower leverage, more cash, or stronger compensating factors.
Equity available depends on rent used for lender review, PITIA, reserves, and that 75% ceiling. It’s not a guaranteed cash figure. For the mechanics, see the refi options and the refinance side of Lendmire’s coverage. Investors new to the product can start with Lendmire’s primer on DSCR loans.
The Appraisal Problem Hiding in the Comps
Comp depth is fine, but the price spread is wide. That’s where cash-out files get trimmed.
Resideline reports a deep pool of closed sales over recent months, with a wide spread between the low and high ends of the range. Most of those sales were houses. Plenty of comps, then. But an appraiser can pull low-end sales for a low-end house, and a result well below what the owner modeled shrinks proceeds fast.
Movoto shows 387 homes sold in the latest month against 312 a year earlier, while days on market rose to 47 from 39. More volume, slightly less pricing power. The two sources use different methods, so read the direction rather than the decimals. The practical move is to bring tight, same-neighborhood, same-condition comps and to size the cash-out with a cushion. Appraisers reward documentation, and appraisal gaps are the most common reason a cash-out comes in smaller than modeled.
Which Kokomo Neighborhoods Fit Cash-Out Math?
Three pockets stand out, and the data quality differs for each. East Kokomo has the only dependable neighborhood-level numbers. The rest are qualitative.
East Kokomo (Darrough Chapel, ZIP 46901). NeighborhoodScout reports a median real estate price of $90,690, cheaper than 92.5% of Indiana neighborhoods, with average rent of $1,142. Housing is mostly small to medium single-family homes plus apartment complexes. Homes.com describes pre-1950 one-story homes with commuting routes to local employers. Rent-to-value is the strongest in the data. The catch is condition. Older stock means capital expenses, and small balances route through select lenders in the network rather than standard programs. Condition and tenant quality need on-the-ground verification.
Indian Heights (south and southeast). Homes.com describes a planned suburban neighborhood from the late 1950s, with ranch-style houses, looping streets, and noticeable uniformity. That uniformity is useful for appraisals, since comparable ranches make cleaner comps. Three- and four-bedroom layouts suit workforce households. No reliable price or rent figure exists for it, so model from the citywide numbers above.
Downtown, Old Silk Stocking, and the historic core. Homes.com calls downtown primarily commercial, with a pocket of historic houses and newly developed townhomes. Rentometer notes apartments dominate the corridor, with studios and one-bedrooms near shops. The 110-acre Old Silk Stocking district has Victorian, Queen Anne, Bungalow, and Tudor Revival homes. Large historic houses could be candidates for small multi-unit use. That’s inference, not sourced fact, and no price or rent data exists for it.
Two areas get less attention. Terrace Meadows and Cedar Crest, in the south near the Markland Mall corridor, are mid-century brick ranch areas close to major employers and retail. College Heights near Indiana University Kokomo is a supplementary tenant pool only. A regional college reports 2,752 undergraduates, so student demand is modest.
Who Actually Rents Here?
Tenant income is concentrated in manufacturing, with health care as a meaningful second leg. Data USA lists resident employment at 6,136 in manufacturing, 4,086 in health care and social assistance, and 3,197 in retail. The Greater Kokomo Economic Development Alliance lists Stellantis at 6,614 employees, Community Howard Regional Health at 1,300, Ascension St. Vincent Kokomo at 1,179, Kokomo School Corporation at 916, Haynes International at 726, Indiana University Kokomo at 689, and BorgWarner at 600. Those counts are from an older update, so treat them as approximate.
The city’s population is about 59,999 per STATS Indiana, with a median household income of $55,360 against $71,957 statewide per Census Bureau QuickFacts. Renters make up 37% of households, according to RentCafe. The rental pool is modest. Fine for a few well-chosen houses. Not a market for a fifty-door bet.
The hospitals help. Two health systems sit beside the auto and alloy plants, so tenants tied to hospitals and clinics are less exposed to the auto cycle. Workforce single-family rentals and small multi-unit buildings are the natural fit. Nobody has published duplex, triplex, or fourplex rent or price data for Kokomo, though small multifamily is professionally managed locally. Underwrite those deals with a rent survey or appraisal rent schedule rather than assumptions.
One more point, this time from the deal desk. On files from single-employer-cluster markets like this one, the common friction is the rent figure. Lenders want an appraisal rent schedule or lease that matches the neighborhood. Cleaner files from a documentation standpoint tend to arrive with signed leases, a recent rent survey, and an insurance quote already in hand. Gaps there hold up cash-out files more often than credit does.
Stellantis, StarPlus, and the Demand Story a Lender Will Hear
The demand story is real, and it needs discounting. This is Kokomo says Stellantis operates three transmission plants and one casting plant in Howard County, making Kokomo the largest automotive transmission-producing community in the world. That’s unusual for a city of about 60,000.
The second anchor is StarPlus Energy, the battery campus. The U.S. Department of Energy reports a $7.54 billion loan, with the project expected to create about 3,200 peak construction jobs and up to 2,800 operations jobs. Those were projections at finalization.
Actual headcount is running behind. WRTV reported 59 salaried job cuts out of 318 salaried employees, with 414 hourly production employees on top of that. That’s roughly 730 workers against a 2,800-job projection. Temporary tariff-related layoffs also hit the Stellantis transmission and casting plants.
The Indiana Business Research Center adds that Howard County has a higher manufacturing concentration than the region and state, and is sensitive to manufacturing swings. It also noted the county had the highest unemployment rate in its region in that report.
The practical rule: underwrite rent on today’s tenant base, not on full battery-plant hiring. A DSCR appraisal or rent assumption that depends on the ramp is a weak file.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Kokomo, Indiana?
Qualification centers on the property’s rent against its full PITIA, with 1.00 as the usual baseline. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Cash-out leverage is capped at 75% LTV, all subject to lender guidelines, credit approval, and property review. Compare DSCR options to see how programs differ.
DSCR vs. conventional financing
Two common ways to finance an investment property in Kokomo, IN. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Kokomo, Indiana?
Expect a rent-based coverage test, a credit tier, reserves, and an appraisal. Standard programs typically go up to $3,000,000, while smaller Kokomo balances route through select lenders in the network. Manufactured homes, log homes, and barndominiums fall outside these programs. Details vary by borrower, property, and loan scenario.
What property types work best for DSCR cash-out in Kokomo?
Workforce single-family houses (3-bedroom ranches and bungalows) and professionally managed small multifamily fit best. Lendmire arranges DSCR investor loans. A key program feature is that rental income, rather than traditional personal-income documentation, is central to lender review.
Does East Kokomo’s low price make cash-out easier?
It makes coverage easier, not proceeds. At a $90,690 median price, even a modest rent clears 1.00 by a wide margin. But a low appraised value limits the dollars available at 75% LTV after payoff. Small balances also route through select lenders. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Should StarPlus hiring figure into a Kokomo refinance?
No. Underwrite to existing rents. Actual battery-plant headcount sits well below the projected 2,800 operations jobs, so any rent assumption that relies on hiring ramp-up adds risk to the file. Verify current local rental rules, taxes, and insurance with qualified local professionals.
The Blind Spot: One Industry Sets the Tenant Base
The biggest blind spot for DSCR-financed investors in Kokomo is concentration. Transmission plants, a casting plant, and a battery campus all answer to the same auto industry, and the tariff layoffs showed how fast that can flip. The hospitals and Haynes International offer some balance, but the lack of any reliable vacancy source means investors can’t see stress building in the data. Until Kokomo has a neutral vacancy series, a cash-out should be sized with enough coverage cushion to survive one slow year in the plants.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire — NMLS# 2371349 — connects investors with wholesale lending channels across 41 markets, including Washington, D.C. The property’s rental income, not the borrower’s traditional personal-income documentation, is central to lender review, an approach that suits self-employed operators and portfolios beyond four financed properties. Lendmire is a top-ranked workplace in 2026 and a 2025 Scotsman Guide Top Mortgage Workplace. To talk through a Kokomo file, call 828-256-2183.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Kokomo Housing Market
2. NeighborhoodScout, Kokomo East
3. U.S. Department of Energy, StarPlus
7. Indiana Business Research Center, Kokomo Outlook
8. Resideline, Kokomo Housing Market
9. Movoto, Kokomo Market Trends
10. Homes.com
11. Homes.com
12. Data USA, Kokomo
13. Greater Kokomo Economic Development Alliance, Major Employers
14. STATS Indiana
16. RentCafe
17. This is Kokomo
19. Scotsman Guide — Top Workplaces 2026
20. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Kokomo, IN · Investment Property Cash-Out Refinance in Indiana
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.