
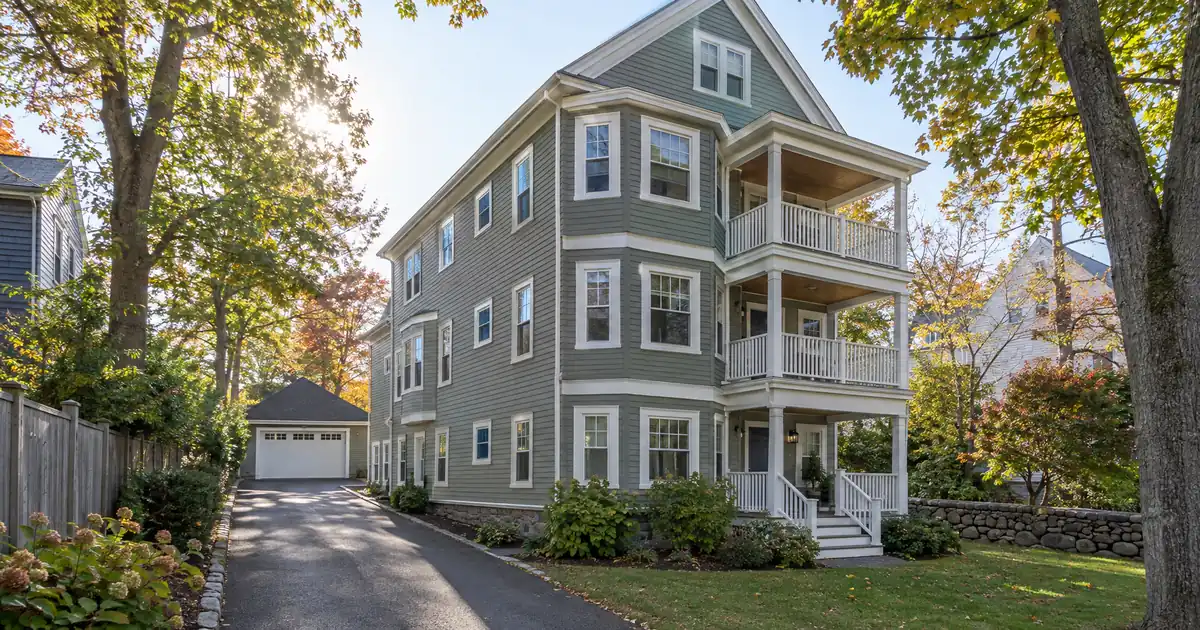
Back Central has a split personality. Zillow’s typical home value there is $347,949, yet the six multi-family buildings currently listed run from $739,900 to $1,400,000 on Homes.com. That gap explains most of what matters about equity extraction in Lowell. The city average describes condos and single-family homes. The buildings investors actually pull cash out of, the three-deckers and small multis, live in a different price universe, and coverage math has to be run on that universe.
For Lowell, Massachusetts rental property financing, Lendmire helps arrange DSCR loans through lenders operating in 41 markets, including Washington, D.C. Lendmire is a non-QM mortgage broker (NMLS# 2371349), so it places the file with a lender that reviews eligibility. This article assumes you already own the building and want to know what a cash-out refinance can and can’t do here.
DSCR Cash-Out Calculator
Run the cash-out numbers in Lowell, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version:
A DSCR cash-out refinance in Lowell, Massachusetts is underwritten primarily on the property’s rental income measured against its full monthly obligation, and the local twist is basis: Zillow’s typical value of $425,330 sits far below the $729K median asking price of multi-family listings, so your building type, not the city average, drives the coverage number.
- Back Central’s typical value is $347,949, while listed multi-families start near $739,900.
- Cash-out typically tops out at 75 percent LTV, with about six months of seasoning from title recording. Tufts Medicine lists 3,655 employees at Lowell General Hospital, a steady tenant pool for northern neighborhoods.
- UMass Lowell reported more than 3,330 new students, supporting demand near campus.
- Downtown’s median sale price is down 3.5 percent year over year, so don’t bank on appreciation.
Lowell Market Snapshot
A quick read on the Lowell investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | Median value $429,200 (Data USA Lowell) |
| Typical rents | $112K annual gross rents (Belvidere 4-unit) (Homes.com Lowell multi-family) |
| Employment | 3,655 employees (Tufts Medicine careers) |
Where Lowell’s Rent-to-Value Sits Best
The lowest-basis neighborhoods, Downtown, the Acre, and Back Central, offer the strongest rent-to-value relationship in the city. Zillow puts Downtown at $331,761, the Acre at $350,178, and Back Central at $347,949, while Zumper shows rents of $1,950 in the Acre and $2,225 in Back Central. Rent aggregators disagree with each other, so treat those as directional.
Downtown is the historic mill core. The National Park Service describes Lowell National Historical Park as covering the entire downtown area, and the City of Lowell points to Middlesex Community College’s Carol Cowan Building and UMass Lowell’s Inn and Conference Center at the Lower Locks site. Employers and campuses sit right there, which supports leasing depth. But Redfin shows a Downtown median sale price of $332K, down 3.5 percent year over year, with an average of 43 days on market. That’s not an appreciation story. If you bought here hoping a rising appraisal would hand you a big cash-out, this is where that plan gets tested.
Back Central is where the listing data gets interesting. One listed three-family there brings in $5,700 a month, about $1,900 per unit, per the same Homes.com page. That sits below Zumper’s $2,225 neighborhood average. Either the units are under-rented or the average is inflated. Honestly, it could be either, and that matters because DSCR lenders often work from the lower of in-place leases and the appraiser’s market-rent schedule. Homes.com also shows a Back Central median home price of $399,900 against an average sale price of $349,836. A $50K spread points to a thin, uneven comp set, which means appraisal variance. Size your refinance off recent sales of the same building type, not neighborhood medians.
The Campus Ring: Pawtucketville and South Lowell
Pawtucketville and South Lowell suit investors who want three-bedroom-per-floor stock near UMass Lowell. Zillow’s typical value in Pawtucketville is $440,425, and Zumper’s neighborhood rent is $2,500. RentHop shows a two-bedroom median of $2,050 and a three-bedroom of $2,400 there, though the two-bedroom figure was down 12.08 percent year over year as of its most recent reading and the three-bedroom down 4.00 percent. Soft, not collapsing. Still worth pricing into your rent assumption.
Enrollment supports the demand story. U.S. News lists 12,294 undergraduates for the most recent fall, and the university’s own convocation release reports more than 3,330 new students. Graduate students and staff tend to sign longer than undergraduates, so an investor near University Avenue might underwrite twelve-month leases rather than pure turnover. Underwrite to the lease, not to the semester.
South Lowell is a thinner data set. Redfin shows a $500K median, up 14.3 percent year over year, but that’s a single month with 24 sales. One month of sales doesn’t make a trend, and a lender’s appraiser won’t treat it like one. Rent.com’s one-bedroom average in South Lowell is $1,950, and the local stock includes three-unit buildings with three 3BR/1BA apartments per Redfin listing descriptions. Those are anecdotes, but they show the layout you’d be refinancing.
Higher Basis, Thinner Cushion: Highlands, Centralville, Belvidere
Highlands runs the priciest of the listed neighborhoods, with Zillow at $476,056 against Zumper rents of $2,100. Centralville sits at $393,546 with $2,025 rents, and Lower Belvidere at $407,690, with Zumper’s Belvidere at $2,150. The pattern is simple: entry prices climb faster than rents as you move away from the core.
Here’s where the single-family trap shows up. Zumper puts average house rent at $2,750 citywide. Run a Pawtucketville house at Zillow’s $440,425 typical value, 75 percent LTV, and full taxes and insurance, and the coverage lands right around the 1.00 line. That’s modeled, not sourced. It means a single-family rental in a higher-priced pocket may not carry much cash-out once the lender applies the 1.00 benchmark and the 75 percent LTV cap together. The stronger play is usually the multi-unit building, where stacked rents do the work. Buyers chasing appreciation in the Highlands could argue the other way, though the mixed appreciation signals across sources make that a harder bet than the rent math.
A Belvidere four-unit advertised with over $112,000 in annual gross rents on Homes.com works out to roughly $2,300 per one-bedroom unit, well above Rent.com’s $1,650 Belvidere one-bedroom average. Maybe the listing is right. Verify against leases before anyone relies on it.
The Appreciation Math
Lowell price signals conflict, so appreciation should be treated as flat to modest and uneven. Zillow shows the citywide typical value up 1.3 percent over the past year. Houzeo shows a median sale price of $409,000, down 16.1 percent, with 47 days on market and 1.01 months of supply. Redfin’s citywide figure is higher, at $519,950 and up 4.0 percent. Those differences reflect methodology: all homes versus single-family, rolling versus monthly figures. Zillow’s typical value is the canonical citywide figure here, and the rest are context.
So what does that mean for a cash-out? Say you bought a triple-decker with 80 percent financing. If the appraised value rises 10 percent, your original balance is roughly 73 percent of the new value. The 75 percent LTV ceiling then leaves about two points of value in extractable equity, before costs and reserves. If value rises 20 percent, the same balance drops to about 67 percent of value, leaving about eight points. Those are modeled illustrations, not Lowell forecasts. The point is that with appreciation this uneven, forced equity through rent growth and paydown matters as much as market movement. A building that’s been re-leased to market rents will appraise differently than one still running legacy leases.
Program guidance points the same direction. Cash-out generally requires about six months of ownership measured from title recording. The LTV ceiling is 75 percent, a different cap than a purchase. Standard programs typically look for a 1.00 DSCR as the baseline, and some lenders review lower ratios with stronger compensating factors, lower leverage, or different pricing. Reserves of about six months of full housing payment are common, and credit tiers generally start at a 620 floor. All of it is subject to lender guidelines, and equity available is never a guaranteed figure. A separate breakdown of investor refinancing covers the details.
Running the Coverage Number on a Lowell Three-Family
Three-family math in Lowell can clear 1.00 with room to spare, but the answer depends entirely on which rents you use. Take the $729K median multi-family asking price as a modeled value and 75 percent LTV. Three 3BR units at RentHop’s $2,400 Pawtucketville figure would produce $7,200 a month. Including taxes and insurance, that shakes out to roughly 1.5x. Swap in the $5,700 in-place Back Central rent instead, and it drops to about 1.2x, again including taxes and insurance and rounded down. The rent divided by full monthly obligation is the whole game, and the $1,500 monthly gap between those two rent assumptions moves the ratio by about a quarter of a point.
Investors underwriting to the neighborhood average get burned when the appraiser’s rent schedule comes in lower. Underwrite each unit’s actual lease.
What if the number lands under 1.00? Then there are structures a lender might review: interest-only payment structures, lower leverage, a program with sub-1.00 provisions, or a longer seasoning period to let rents catch up. None of those is assured. Eligibility review depends on credit approval, property review, and lender guidelines.
Lendmire’s deal desk sees a pattern on files from gateway-city markets like this one: the cleaner files, from a documentation standpoint, tend to have a signed lease on every unit and a rent roll that matches the appraiser’s market-rent schedule. The common friction point is a building where leases sit well below or above what the appraisal supports, which forces a recalculation late in the file. Separately metered utilities per unit, common in Lowell’s three-deckers, tend to make per-unit rents easier to document.
For a value-add example, one local listing is a Victorian gutted to the studs and approved for a three-family with an attached ADU. A DSCR cash-out only works after the units are built, leased, and appraised as income property. A renovation-stage asset needs bridge or rehab financing first, and cash-out comes later.
Demand That Doesn’t Move With the Semester
Health care and universities give Lowell tenant demand that isn’t tied to one employer. Data USA shows 11,604 residents employed in health care and social assistance, 9,435 in manufacturing, and 5,773 in retail trade. The homeownership rate is 43.2 percent, so this is a renter-heavy city. Census Bureau QuickFacts counts 120,418 residents across 13.6 square miles, with a median household income of $82,956.
Lowell General Hospital, part of Circle Health and Tufts Medicine, lists 3,655 employees. Nurses and technicians are a non-student renter pool, and the main campus sits in the Pawtucketville and Centralville area, which supports underwriting 2-3BR units in the northern neighborhoods at full-year occupancy. The City of Lowell’s own workforce page notes UMass Lowell runs more than $50 million in yearly budgeted research, an older figure, but a signal of university-linked employment. There’s no reliable citywide vacancy rate, rent-growth figure, or cap-rate data in the research behind this article, so none is offered here. Ask your appraiser and property manager for current comps.
Investors should verify current local rental rules, taxes, and insurance with qualified local professionals.
Turning Proceeds Into the Next Building
The cash from a Lowell refinance is only useful if it has somewhere to go. The most common use is a down payment on another small multi-family, so the lender’s view of the cash-out property matters twice: it has to appraise well and carry its own debt. Holding the buildings in an LLC works for many investors, subject to lender program eligibility. Loan amounts up to $3,000,000 fit standard programs, with smaller balances routed through select lenders in the network. The equity recycle pathway walks through that sequence, and the guide “Where DSCR and Conventional Diverge” against conventional financing explains why self-employed investors often go this route. For basics, see Lendmire’s DSCR guide, and for state-specific context, Lendmire’s Massachusetts DSCR platform.
To talk through a specific building, call 828-256-2183 or start your quote.
Frequently Asked Questions
Which Lowell neighborhoods offer the strongest rent-to-value for a cash-out?
Downtown, the Acre, and Back Central, based on Zillow values between roughly $332K and $350K against Zumper rents of $1,950 to $2,225. Still, no source gives 2-4 unit price-to-rent ratios, so verify with actual leases and an appraiser’s rent schedule before assuming the numbers carry over to a multi-family.
DSCR vs. conventional financing
Two common ways to finance an investment property in Lowell, MA. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Is a single-family rental in Pawtucketville or the Highlands a good cash-out candidate?
Usually thinner than a multi-unit. Zillow values run $440,425 in Pawtucketville and $476,056 in the Highlands, while Zumper’s average house rent is $2,750. Modeled with full taxes and insurance, coverage can land near 1.00, which leaves little room once the 75 percent LTV cap applies.
How long do I have to own a Lowell property before pulling cash out?
About six months, measured from the title recording date, is the typical seasoning guideline. Some lenders review shorter timelines with different terms. If you’ve renovated and re-leased the building, an appraiser will look at the income-producing condition, so timing the appraisal after leases are signed can help.
Can I refinance a renovation project into a DSCR cash-out?
Not until it’s built, leased, and appraised as income property. A gutted Victorian with approved plans for a three-family and an ADU would generally need bridge or rehab financing first, and the DSCR cash-out follows once rents are in place.
How much cash will a Lowell cash-out actually return?
It depends on rent used for lender review, the full monthly obligation, reserves, and the 75 percent LTV ceiling, so no figure is guaranteed. Investors who bought near 80 percent leverage and saw only modest appreciation may find little extractable equity yet, which is why Lowell’s flat-to-modest price trend matters.
What to Watch Next Quarter
Three indicators tell you whether to move on a Lowell refinance now or wait:
- Downtown and Back Central comps. If the Downtown median sale price stops sliding from its 3.5 percent year-over-year decline and multi-family days on market shorten from Back Central’s 54, appraisals become easier to defend.
- Pawtucketville two- and three-bedroom rents. Another drop from RentHop’s $2,050 and $2,400 readings would pressure coverage on the campus-ring buildings.
- UMass Lowell’s next new-student count against last year’s 3,330-plus. A steady or rising figure supports twelve-month leasing near University Avenue.
Lowell’s mill-era three-deckers were built for a workforce that never stopped arriving, and the investors who do best with them are the ones who let signed leases, not neighborhood averages, set the appraisal.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, which suits self-employed investors and LLC-owned portfolios. Lendmire was recognized by Scotsman Guide as a 2026 Top Workplace and named a 2025 Scotsman Guide Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Homes.com, Back Central Multi-Family
3. Redfin, Lowell Multi-Family Listings
4. Tufts Medicine Careers, Locations
6. Homes.com
7. Zumper, Lowell Rent Research
8. National Park Service, Lowell National Historical Park
10. Redfin
11. RentHop
12. $500K median
13. Houzeo
14. Census Reporter, Lowell City
15. Circle Health and Tufts Medicine
16. lowellma.gov — Workforce Development
17. recognized by Scotsman Guide as a 2026 Top Workplace
18. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Lowell, MA · Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.