
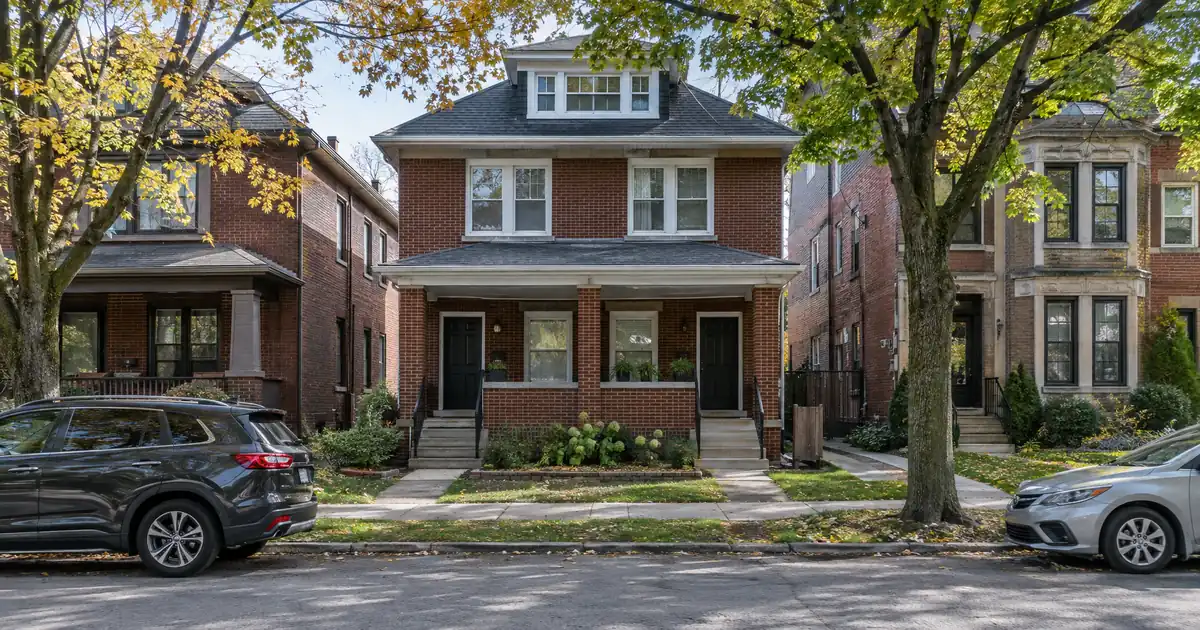
If you own a duplex or fourplex in Newark that you bought a few years back, the appraisal may now be telling a very different story than your closing statement did. Here’s what most brokers skip: in this market the cash-out amount and the coverage ratio are two separate questions, and the second one usually decides the file.
For real estate investors in Newark, Ohio, Lendmire helps structure and place DSCR financing through wholesale lenders operating in 41 markets, including D.C. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. It arranges these loans; lenders review and approve them.
DSCR Cash-Out Calculator
Run the cash-out numbers in Newark, OH
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
At a Glance: A DSCR cash-out refinance in Newark, Ohio fits owners of small multifamily and workforce rentals who want equity redeployed, because the loan is underwritten primarily on the property’s rental income measured against its full monthly obligation, not on traditional personal-income documentation.
- Newark’s Data USA profile shows a $192,300 median property value, well below listing-side prices.
- Cash-out leverage is capped at 75% LTV, with about 6 months of ownership seasoning.
- Two 2BR units gross roughly $2,360 to $2,470 monthly on sourced rents.
- In-place legacy rents can sit far below market and pull coverage under 1.00. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
The Campus Grid: Where Stacked Rents Do the Work
The strongest cash-out candidates in Newark are 2–4 unit buildings near downtown and the shared Ohio State Newark and Central Ohio Technical College campus. Stacked unit rents lift the numerator in a way a single-family house cannot, and the neighborhood has employment anchors within a short drive.
The Ohio State University at Newark and Central Ohio Technical College share one campus. COTC enrolls roughly 3,000 students by IPEDS-based figures, and its Newark campus page describes 12 buildings including three residence halls. The campus sits close to Courthouse Square, where county workers and service employees form the likely tenant base. That’s inference, not a sourced tenant survey. No verified per-neighborhood price or rent series exists for Newark, and this article won’t pretend otherwise.
Here’s what the rent data does support. Rentometer, which covers houses along with apartments, shows 2BR rents at $1,234 and 3BR at $1,567. RentCafe puts the 2BR at $1,182 and the 3BR at $1,377, with average rent at $1,136, up 3.09% year over year. RentCafe’s basis is buildings with 50+ units, so it understates small-building rents. Two 2BR units gross about $2,360 to $2,470 a month. One 3BR house grosses about $1,377 to $1,567. That’s the gap that makes duplexes the better DSCR vehicle here.
Renter demand is real. RentCafe counts 8,964 renter-occupied households, 44% of the total, so the tenant pool for small buildings is deep for a city of this size.
What the Appraiser Sees Versus What the Leases Say
Newark’s listing-side prices have run ahead of its survey-based values, and that gap is what makes a cash-out refinance interesting now. Homes.com reports a 12-month median sale price of $259,900, up 6% on the prior 12 months. Data USA’s $192,300 median property value measures owner-reported values, a different yardstick. Cite them as a range, not one number.
Recent appreciation supports a higher appraised value on the building you already own. But it cuts both ways. Higher value compresses rent-to-value on anything bought recently, and property tax and insurance scale with value inside the payment the lender tests.
Then there’s the rent-roll problem. Active duplex and triplex listings on Homes.com show in-place rents of $500 and $550 per unit on one building, and an efficiency at $650 with a Section 8 unit totaling $894 on another. Those sit far below the $1,182 to $1,377 unit averages. A lender’s appraisal typically supplies a market-rent figure, which can lift rent used for lender review above what the leases pay. Underwrite each building from its own rent roll and the appraiser’s rent schedule, not from a city average.
Running the Numbers (Modeled, Not Sourced)
On identical value, a duplex clears 1.00 comfortably while a single-family 3BR falls short. These are modeled assumptions, not market facts. Take a property appraising near $260,000, in line with the Homes.com sale median, financed at 75% LTV. Coverage here means rent divided by full PITIA, with taxes and insurance at Ohio-average loadings included. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
- Duplex, two 2BR units at $1,234 each: modeled coverage lands around 1.4x including taxes and insurance.
- Single-family 3BR at $1,377 to $1,567: coverage lands roughly 0.8x to 0.9x on the same basis.
- The same duplex on in-place rents of $500 and $550: coverage drops to roughly 0.6x.
Most standard programs are built around a 1.00x benchmark because the rent covers the payment at that level. Below it, some lenders may review sub-1.00 or no-ratio structures, but those typically come with lower leverage, different pricing or more reserves. An owner of that 3BR house could explore a sub-1.00 program, a lower-LTV cash-out, or an interest-only structure, all subject to lender guidelines, credit approval and property review. Cash-out proceeds depend on rent used for lender review, PITIA, reserves and the 75% ceiling. They are not a guaranteed figure.
DSCR files in markets like this one typically look like a tale of two rent rolls. The purchase-era pro forma used market rent, the current leases lag it, and the appraisal’s rent schedule decides which number the lender trusts. The files that go smoothly usually bring the lease copies, a recent rent comp set and a clear reserve picture up front. Files with mixed legacy leases tend to need the most explanation.
Seasoning and Leverage
Seasoning runs about 6 months of ownership, measured from title recording. The 75% LTV ceiling is the outer limit, and 2–4 unit files often sit below it depending on the lender, since these terms vary and change. Credit tiers typically start with a 620 floor, with better positioning at 660, 680 and 700. Reserves generally run about 6 months of PITIA. Loan sizes reach up to $3,000,000 on standard programs, with smaller balances routed through select lenders in the network. Review details are subject to lender overlays.
One wrinkle: buildings with 5+ units may fall into commercial underwriting, which changes the structure entirely. Newark’s inventory skews small, so most owners won’t hit that line.
Comps Are Thin (Plan for It)
Appraisal risk in Newark is a comp-count problem. Redfin’s Licking County page showed 24 multi-family units for sale against 168 homes sold in the period captured. Those are undated county-wide snapshots, so read them directionally. Fewer recent 2–4 unit sales means the appraiser has less to lean on, which can cap value and the cash-out amount on a duplex or fourplex. Liquidity itself looks adequate: Homes.com shows multi-family homes averaging 29 days on the market.
Small buildings also carry a low price floor. Homes.com lists 9 multi-family properties from $119,900 upward, including a four-unit building of one-bedroom lofts near 21st Street. A one-bedroom-heavy fourplex carries lower per-unit rents than a 2–3BR duplex, so compare total gross rent to value, not per-unit rent.
Who Rents in Newark?
Nobody here is renting on a tech-hub wage, and that’s the point. Census Bureau QuickFacts shows a population of 50,783, a $61,670 median household income and a median age of 38.8. Data USA shows resident employment led by retail (3,735), manufacturing (3,302) and health care (3,110), with a 55.8% homeownership rate.
Licking Memorial Health Systems, a not-for-profit system based in Newark, is a core health anchor, and Licking County government reports approximately 1,200 employees. Columbus Region lists an Owens Corning manufacturing operation in Newark. Diversified, workforce-driven employment tends to support steady long-term occupancy, which is what a cash-out lender wants to see in the rent history.
The Intel Question (Treat as Upside, Not Underwriting)
Local reporting from ABC6 placed Newark, Heath and Hebron within a 20-minute commute of the Intel site, and noted central Ohio added 240,000 residents in a decade but only 80,000 homes. Columbus CEO quoted planners calling duplexes and triplexes “the missing middle of housing.” That reporting predates the project’s contested timeline, so it’s a potential driver, not a certainty. Never build coverage on it. The regional shortage is the sturdier point: small 2–4 unit buildings are under-supplied, which supports exit liquidity for the very property type a DSCR refinance targets.
Where the Proceeds Go
Cash-out only pays if the next deal earns more than the leverage costs. In a market with a $192,300 to $259,900 value range, proceeds from one duplex can plausibly fund the down payment on another small building. The stronger play is usually the second duplex over a single-family house, because the coverage math above favors stacking units. Investors chasing appreciation alone could argue for the reverse, though the single-family exit is simpler.
Compare paths before committing. Lendmire’s DSCR walkthrough covers the mechanics, the guide “Where DSCR and Conventional Diverge” explain why DSCR files don’t lean on personal income, and refinancing options lay out rate-and-term versus cash-out. For structure specifics, see pulling equity with a DSCR cash-out and the state’s Ohio DSCR investor loans hub. To talk through a specific building, reach the team at 828-256-2183. Verify current local rental rules, taxes and insurance with qualified local professionals before you close on anything.
Frequently Asked Questions
Does a Newark duplex cash out better than a single-family rental?
On modeled numbers, yes. At the same appraised value, two 2BR units produce coverage near 1.4x including taxes and insurance, while a 3BR house lands under 1.00. Lender guidelines and the appraisal decide the actual result.
DSCR vs. conventional financing
Two common ways to finance an investment property in Newark, OH. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What if my Newark leases are below market rent?
Legacy rents of $500 to $650 per unit can leave a building well short of the 1.00 benchmark on lease income alone. Appraisers may use a market-rent schedule instead, so bring the rent roll and a fresh comp set. Qualification stays subject to lender review.
How long do I have to own the property first?
About 6 months, measured from title recording. After that, the 75% LTV ceiling and your coverage ratio set the ceiling on proceeds. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Will the Intel project raise my appraisal?
Don’t count on it. Reporting placed Newark within a 20-minute commute, but the timeline has been contested. Treat it as possible upside, not a valuation input.
Do 2–4 unit buildings get the same leverage as single-family?
Often lower. The 75% ceiling is the outer limit, and multi-unit cash-outs commonly sit under it depending on the lender.
Newark’s small-building market rewards the owner who knows the rent roll cold: appraisers here work with a shallow comp pool, so a clean lease file and a defensible rent schedule will do more for a cash-out than any headline about appreciation.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) places investor financing across 41 markets, 40 states plus Washington, D.C. DSCR eligibility is generally reviewed by the lender on property cash flow rather than traditional personal-income documentation, subject to lender guidelines. Lendmire was recognized by Scotsman Guide as a 2026 Top Workplace and is also a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. The Ohio State University at Newark
3. Central Ohio Technical College
5. Rentometer, Newark average rent
6. RentCafe, Newark rent trends
7. Homes.com, Newark multi-family listings
8. Redfin’s Licking County page
11. Columbus Region
12. ABC6
13. recognized by Scotsman Guide as a 2026 Top Workplace
14. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Newark Ohio · DSCR Cash Out Refinance Columbus Ohio · Cash Out Refinance Investment Property Cincinnati Ohio
Guides: Investment Property Cash-Out Refinance in Newark, OH · Investment Property Cash-Out Refinance in Ohio
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.