
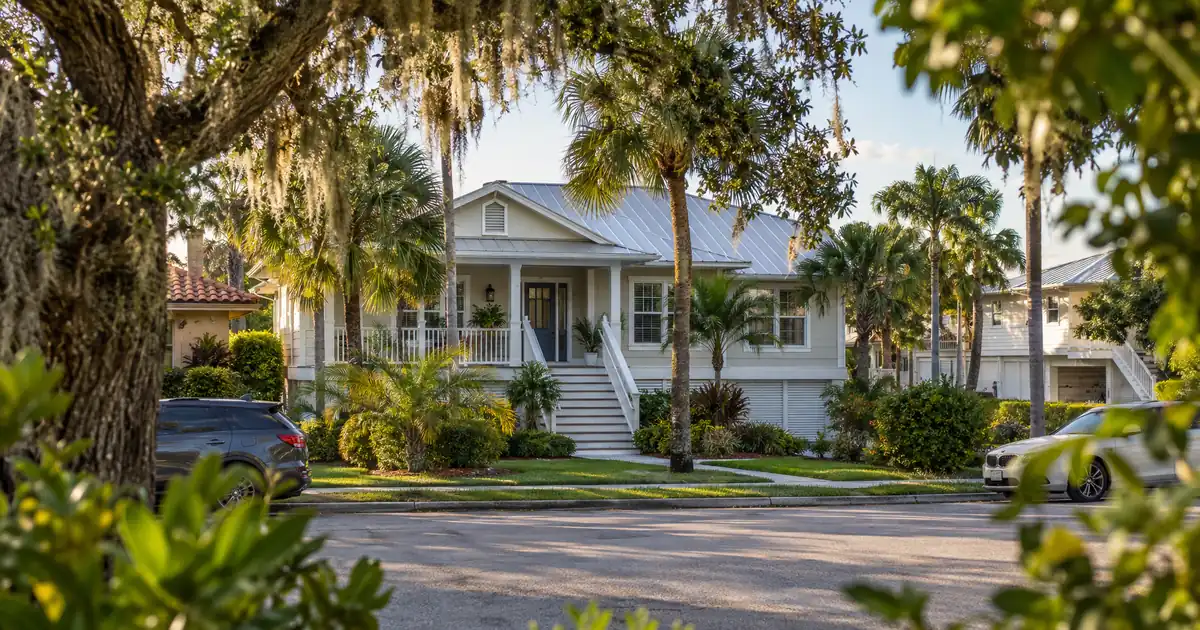
Picture an investor holding a Sebastian Highlands single-family rental purchased a few years ago, now sitting in a neighborhood where, per NeighborhoodScout, home values have climbed above what the investor originally paid. The tenant is in place and the lease is current. The investor wants the appreciation working on the next deal rather than sitting idle in drywall. That is the cash-out refinance question in Sebastian, and the answer depends less on the value than on whether the rent can carry the new balance.
At a Glance: A DSCR cash-out refinance in Sebastian, Florida is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the workforce single-family stock in the 32958 ZIP, which Momentum Realty puts at a gross rent yield near 7.15%, is where the structure fits best.
DSCR Cash-Out Calculator
Run the cash-out numbers in Sebastian, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out LTV tops out at 75%, with about 6 months of seasoning from title recording.
- Sebastian Highlands rents cluster in the $2,300s to $2,500s, which decides how much leverage the rent supports.
- Rental vacancy runs 5.9% per Census-sourced data, so build in a lease-up buffer.
- Only 3 multifamily listings were active citywide, so single-family comps carry most files.
Sebastian Market Snapshot
A quick read on the Sebastian investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $365K median (Redfin Sebastian Housing Market) |
| Typical rents | $2,562 avg (NeighborhoodScout) |
| Population | 26,262 population (Census Reporter) |
| Employment | ~1,500 employees (Digital Towns) |
What the Sebastian Numbers Say Right Now
Sebastian’s median sale price is $360,000 across 309 closed sales, per Resideline, with the middle half of sales landing between $295,000 and $430,000. Values are flat to slightly softer year over year. Redfin’s data shows longer days on market than a year earlier. That is a cooling market, not a broken one.
The appreciation story sits underneath. Momentum Realty’s 32958 scorecard shows values up roughly 5.6% a year over five years, with a typical home value of $344,877. Hold a rental through that stretch and you probably have equity to pull. Recent price movement is the smaller issue, because the appraiser will price your property off closed sales rather than your purchase date.
Seasoning matters here. Most cash-out programs want about 6 months of ownership measured from title recording, so an investor who closed recently should check the recording date before ordering anything. Subject to lender guidelines, of course.
The Math at 75%
The 75% LTV ceiling is a limit, not a target, and Sebastian rents explain why. Rent divided by the full monthly obligation (principal, interest, taxes, and insurance) is the coverage number, and 1.00 is the standard baseline most programs are built around.
Run the numbers on a Sebastian Highlands rental valued near the $388,662 neighborhood median, using modeled assumptions for financing costs. Redfin’s rental data puts the neighborhood median rent at $2,347, while NeighborhoodScout shows an average of $2,562. At the full 75% ceiling and including taxes and insurance, coverage lands around 0.95 to 1.05. That is borderline. Pull leverage back toward 65% and the same rents move into roughly 1.05 to 1.15 territory.
Underwrite to the lower rent. Redfin’s figure is the more conservative one, and the gap between the two sources changes how much cash-out the property supports at the margin.
If a property lands below 1.00 on long-term rent, several paths may apply for a lender to review: lower leverage, a sub-1.00 program, or an interest-only structure. Each carries different pricing and reserve expectations, and eligibility depends on credit, reserves, and property review. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Reserves generally run about 6 months of the full monthly obligation.
DSCR files in markets like this one typically look the same. The rent is fine, but the insurance and tax lines move the ratio more than the purchase price does. Lendmire, a DSCR-focused mortgage broker (NMLS# 2371349), arranges investor loans in 40 states plus Washington, D.C., 41 markets in total, and the pattern holds across those files. The stronger applications lead with a current lease, a fresh insurance quote, and a conservative rent figure. Borrowers who lead with an optimistic ARV tend to get re-traded. Lendmire’s DSCR guide covers how the ratio is built.
Where Sebastian Rentals Refinance Best
Sebastian Highlands is the volume market. It is the city’s largest subdivision, with three- and four-bedroom single-family homes making up most of the stock. The 32958 ZIP has the highest number of recently sold homes in the city, which means the deepest bench of appraisal comps. For a cash-out, comp depth is worth more than headline yield. A property with ten defensible sold comps gets a cleaner value than a nicer property with two.
Wabasso and Roseland are the quieter northern pockets, with older Florida homes on larger lots and lower density. Rent data there is thin. The brief found no reliable per-neighborhood rent breakdown beyond Sebastian Highlands, so investors should use city-level figures as a starting point only and lean on actual lease documentation. Thin data means the appraiser may reach further for comps.
The western CR 512 corridor is the newer-growth side. It offers more new-construction workforce housing with interstate access, which appeals to commuting households. Newer stock tends to mean less deferred maintenance in the appraisal, though a recently built home has less appreciation history for a seasoning-based equity story.
Skip the barrier island for this strategy. It skews toward second-home and vacation use rather than workforce leasing, and a cash-out underwritten on long-term rent needs a lease-driven tenant profile.
Multifamily is the odd one out. Homes.com shows just 3 multifamily listings citywide, priced between $574,000 and $2,299,000, averaging 76 days listed. An investor who already owns a duplex or triplex along the US-1 corridor near the hospital holds a scarce asset. The catch is that scarcity cuts both ways: appraisers have few multifamily comps, so value support can be harder to document than for a single-family home.
Who Fills the Leases
Healthcare anchors the tenant base. Orlando Health received bankruptcy court approval to buy Sebastian River Medical Center and two other Steward Health Care hospitals for $439.42 million in cash, per Sebastian Daily. The hospital moved to Orlando Health ownership in October, and the system said it had no plans to lay off current staff. It is a 178-bed facility that has also added capacity through recent expansions.
For a refinance, that matters as continuity. A rental near a major regional health system draws nurses, technicians, and support staff whose demand doesn’t track beach-season swings. Health Care and Social Assistance is also the largest employment sector among residents, at 1,258 people.
Manufacturing supplies the second leg. Piper Aircraft, headquartered in Vero Beach, is the largest private employer in Indian River County per Piper. A digital industry profile puts its Vero Beach workforce near 1,500, though headcount sources conflict on scope, so treat that as an approximate anchor. Triton Submarines, based in Sebastian, adds a small skilled-fabrication payroll. None of these employers is a single point of failure. Together they support workforce rentals in the western and CR 512 side of the city.
Where the Appraisal Can Bite
Vacancy is the number to respect. Of Sebastian’s 12,192 housing units, 8.3% were vacant and the rental vacancy rate was 5.9%, per Census-sourced data. That is not a tight market. Stress the file with a realistic gap between tenants rather than assuming instant lease-up.
Price behavior adds a second flag. About 28.1% of listings in 32958 have cut their asking price, while the citywide typical home goes pending in about 23 days on Zillow’s data. Sellers are chasing the market down, yet homes are still moving. The practical risk is an appraiser leaning on list prices instead of closed sales. Ask for sold-comp support, and be ready to hand over the recent closings yourself.
Investors who underwrite to sold comps and the $2,300s rent figure rarely get surprised. Investors who underwrite to asking prices and the Zillow-style $2,800 median often do. Zillow’s page mixes dated data, so it reads better as a ceiling than a baseline. Verify current local rules, taxes, and insurance with qualified local professionals before you commit.
Recycling the Proceeds
Cash from a refinance only earns its keep if the next deal works. The equity recycle pathway walks through how proceeds move into the next acquisition, and the investor refinance breakdown compares refinance types. Loan sizes on standard programs go up to $3,000,000, though smaller balances route through select lenders in the network.
Consider an investor with a Sebastian Highlands rental who reserves part of the proceeds for the 6-month reserve requirement on the next property. That reserve is the piece most owners forget. Available equity depends on rent used for lender review, the full monthly obligation, reserves, and the 75% cap, so it is never a guaranteed figure. Borrowers who hold the property in an LLC should confirm entity eligibility, subject to lender program eligibility. To compare structures, see how the math pencils or call 828-256-2183. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Tax and legal consequences of pulling equity sit outside this analysis. Confirm them with a qualified professional.
DSCR vs. conventional financing
Two common ways to finance an investment property in Sebastian, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR loan in Sebastian?
Qualification centers on the property’s rent against its full monthly obligation, with 1.00 the common baseline. Credit score, reserves, and property review also matter, and typical guidance sets a 620 floor. Sebastian’s Redfin rent figure of $2,347 for Sebastian Highlands is a sensible conservative input. Final eligibility rests with the lender.
What are the requirements for an investment property loan in Sebastian, Florida?
Most files call for a seasoned property (about 6 months from title recording), a 75% maximum LTV on cash-out, and roughly 6 months of reserves. Loan amounts on standard programs reach $3,000,000. Manufactured homes, log homes, and barndominiums fall outside these programs. Details vary by lender and borrower.
How does rental income affect DSCR refinance eligibility in Sebastian?
Rent sets the coverage ratio, and the ratio caps how much cash-out the property supports. Lendmire arranges DSCR refinance loans through its wholesale network, with qualification built primarily on property income instead of personal income documentation, depending on the program.
Does the Orlando Health hospital deal change Sebastian rental demand?
It supports continuity rather than creating a new wave. The $439.42 million acquisition kept the hospital inside a large regional system, and there were no announced layoffs. That steadies demand from healthcare workers in nearby workforce housing.
Why is 32958 the ZIP most cash-out files start with?
It leads in recent sales volume, so appraisers find more comparable closings. Momentum Realty shows a gross rent yield near 7.15% and about 5.6% annual appreciation over five years. The ZIP still has price-cut pressure, so sold comps matter.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a non-QM mortgage broker (NMLS# 2371349), Lendmire facilitates DSCR investor loans across 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income instead of personal income documentation, subject to lender guidelines, serving LLC-structured portfolios and self-employed borrowers who don’t fit conventional boxes. Lendmire is a two-time Scotsman Guide Top Mortgage Workplace (2025, 2026).
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Momentum Realty: 32958 housing scorecard
3. Redfin Sebastian Housing Market
6. Resideline: Sebastian housing market
7. Homes.com: Sebastian multifamily listings
8. Sebastian Daily: Orlando Health acquisition
9. Piper
11. Scotsman Guide 2025 Top Mortgage Workplace
12. Scotsman Guide 2026 Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Sebastian, Florida · DSCR Cash Out Refinance Jupiter Florida: Access Equity Without Income Docs · Cash Out Refinance Investment Property Tamarac Florida
Guides: Investment Property Cash-Out Refinance in Sebastian, FL · Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.