
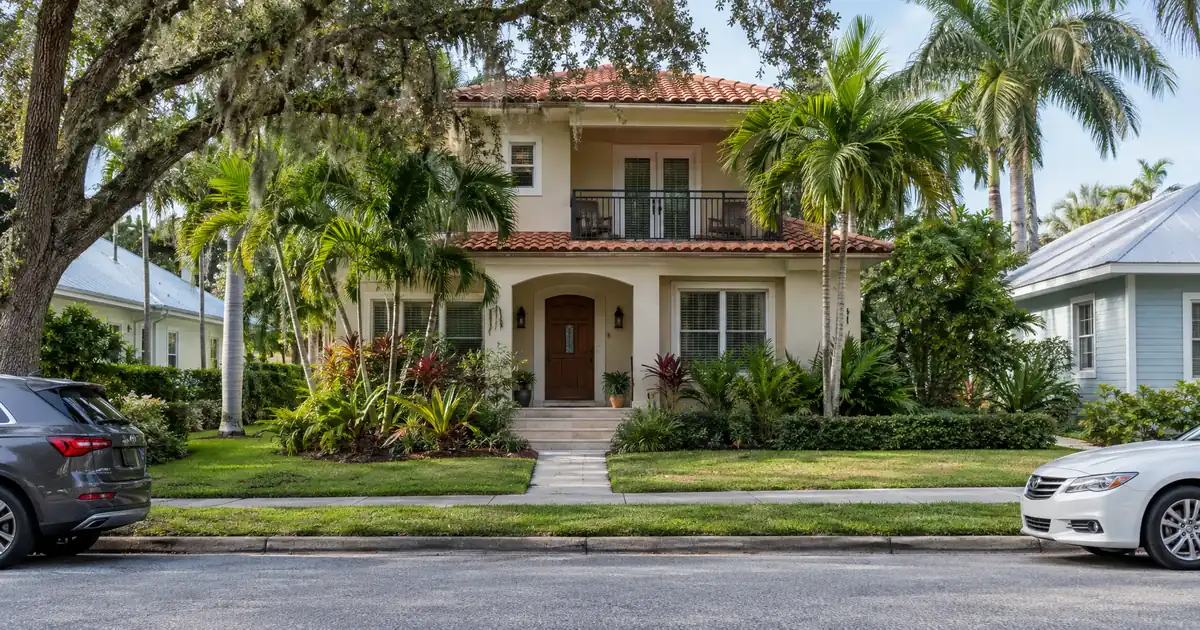
The City of Weston has ten city employees and buys its municipal services from contract providers. That is a strange profile for a city of roughly 68,000 people, and it fits the housing stock: a planned, owner-occupied enclave where the rentable product is mostly single-family homes, townhomes, and villas, not duplexes. For an investor who already owns here and wants to pull equity out, a DSCR cash out refinance in Weston comes down to which side of a sharp price-to-rent line the property sits on.
The Short Version: A DSCR cash-out refinance in Weston, Florida is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the file needs a seasoned title, a lease or market-rent opinion that clears the 1.00 baseline, and enough appraised value to sit under a 75% loan-to-value ceiling.
DSCR Cash-Out Calculator
Run the cash-out numbers in Weston, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Small multifamily is only 3.63% of Weston’s housing units, per NeighborhoodScout. – Redfin shows an $800K median sale price, down 2.3% year over year. – Zumper puts median rent at $4,500, down 8% over the year.
- Townhomes and older single-family homes start in the mid-$400Ks, per a local agent blog. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Weston Market Snapshot
A quick read on the Weston investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Employment | 10 city employees (City of Weston) |
| Vacancy | 9.7% Broward market-rate/luxury (The Real Deal, South Florida) |
Why Weston Is a Single-Family and Attached-Home Story
Weston’s rental stock is not what most cash-out borrowers expect. NeighborhoodScout reports single-family detached homes at 63% of units, large apartment complexes at 21.03%, row houses and other attached homes at 11.97%, and duplexes or small apartment buildings at just 3.63%. Anyone hoping to stack four doors on one deed is shopping the wrong city.
Tenure tells the same story. RentCafe’s Census-based figures show 5,839 renter-occupied households (27%) against 15,570 owner-occupied (73%). Within rentals, RentCafe’s stock breakdown puts 25% in single-family rentals and 69% in small-scale complexes under 50 units. The average apartment building is about 31 years old, and none went up after 2000.
Lendmire (NMLS# 2371349) is a mortgage broker specializing in DSCR loans. Lendmire helps arrange DSCR financing for Weston, Florida investors as part of a broader non-QM footprint reaching 41 markets, including D.C. For state-level context, see the Florida DSCR financing hub.
Where the Coverage Math Holds and Where It Breaks
Rent-to-value separates Weston’s communities more than any other variable. Redfin’s neighborhood rent table (last updated September 2025) lists median rents of $2,650 in Bonaventure, $3,500 in The Ridges, $3,950 in Country Isles, and $7,200 in Weston Hills. Treat these as small-sample listing medians. Month-over-month swings such as North Lakes at +37% show how thin the samples are.
Prices spread even wider. The local agent blog puts townhomes and older single-family homes in The Meadows and Heron Lakes in the mid-$400Ks. Weston Hills Country Club runs $900K to well over $1.5M, and Botaniko’s new construction pushes past $2M. The same blog says single-family rentals commonly reach $3,500 to $4,500.
Run the numbers on two modeled cases. These are illustrative assumptions, not sourced market data, and both include taxes and insurance in the monthly obligation.
- Entry-priced attached home: a $450K townhome renting for $3,500 to $4,500, financed at 75% LTV, lands roughly between 1.2x and 1.5x.
- Weston Hills-tier home: at the bottom of the $900K band with a rent near the $7,200 median, coverage stays comfortable. Move toward $1.5M with the same rent and the ratio falls below 1.00. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Bigger house, bigger rent, worse ratio. The tier above $1.5M also carries a longer reserve requirement, about 9 months of PITIA instead of the usual 6. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
For files that land under 1.00 on long-term rent, a lender may review a lower-leverage structure, an interest-only option, or a program built for sub-1.00 coverage. Eligibility stays subject to lender guidelines, credit approval, and property review.
Zip-code rents point to the same product type. Prop:Metrics shows 33326 at $2,590 for a 2-BR and $3,780 for a 3-BR, with 2- and 3-bedrooms making up 58% and 26.4% of rentals. That skews toward townhomes and villas. In 33327, a 3-BR runs $4,350 and a 4-BR $5,180. Those are aggregator figures from RentCast data, so use them directionally.
The Appreciation Problem Nobody Wants to Price
Weston is a value-held market, not a rent-growth market. Recent Redfin data shows the three-month median sale price slipping modestly year over year, even as price per square foot has edged higher, which points to a shift in the mix of homes selling rather than a broad repricing. Average days on market has stayed close to where it was a year earlier. Zumper’s median rent has softened over the last year, and because that median covers all bedroom counts and property types, it skews toward larger homes. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
That mix matters for a cash-out file. Equity comes from the appraised value, and the 75% LTV ceiling does not bend for a soft comp set. An owner who bought at a peak and hasn’t held long may find that 75% of today’s appraisal barely clears the existing payoff. Owners with long holds and low balances are the ones who extract meaningful proceeds. Underwrite on in-place rent or a conservative market rent, and assume no growth. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
The rent aggregators also disagree, which shapes how the appraiser’s rent schedule gets read. RentCafe’s $2,773 average covers only buildings with 50+ units. City-data.com’s Census-based median gross rent is $3,013. Zumper sits at $4,500. Different property mixes produce those gaps, so the lender’s own rent opinion is the number that counts.
What Actually Happens on a Weston File
Cash-out files in a master-planned community like this one usually hold up or stall on paperwork, not on the deal thesis. Lendmire’s deal desk tends to see the same friction points in HOA-governed suburbs. Association dues belong in the monthly obligation, so the dues letter needs to be current. The lease has to match the rent used for coverage. And title recording dates decide whether the roughly 6-month seasoning clock has run, which matters most for owners who closed with cash and are refinancing right after. The cleaner files show up with a signed lease, current insurance declarations, and a clear ownership history already assembled.
Vesting is another checkpoint. If the property sits in an LLC, the entity documents and vesting language get reviewed, subject to lender program eligibility.
Program guidance for this file type is fairly narrow. Most borrowers see a 620 credit floor, with pricing tiers at 660, 680, and 700. Reserves run about 6 months of PITIA, and loan amounts go up to $3,000,000 on standard programs, subject to lender guidelines. Smaller balances route through select lenders in the network. See the guide “What Is a DSCR Loan” and the cash-out refinance details for the mechanics. For the broader refinance menu, there’s a separate page on rate-and-term and cash-out refi details. The comparison to conventional is worth a read if a W-2 or tax-return file is also on the table.
The Tenant Base Behind the Rents
Demand here is bedroom-community demand. Data USA shows resident employment by sector led by Professional, Scientific and Technical Services (5,026), Health Care and Social Assistance (3,509), and Manufacturing (3,382). Resident employment grew 2.95% in the latest year, from 32.9K to 33.9K. Residents may work outside the city, so tenant demand tracks South Florida’s wider job corridor more than Weston-only payrolls.
The health-care anchor is the most visible. Cleveland Clinic Weston Hospital reports 250 physicians across 55 specialties and describes itself as South Florida’s largest non-university, physician-graduate training center. Residents, fellows, clinicians, and support staff create steady demand for 3- and 4-bedroom homes and townhomes. Headcount and renter share for the campus weren’t available, so the link between that pool and specific Weston rents is a reasonable inference, not a measured one.
Broward’s apartment supply is the market-rate threat. The Real Deal cites Broward market-rate and luxury vacancy at 9.7%, while affordable, workforce, and older properties at attainable rents tend to lease faster. Weston’s own apartment stock is old, so the pressure arrives from neighboring cities’ new deliveries, and it lands hardest on high-end rentals. Older townhomes and villas at workforce rents face less of it.
Why Duplex Hunters Should Look Elsewhere
Small multifamily inventory in Weston is thin enough to skip as a strategy. If a duplex or fourplex shows up, it likely trades at a premium. Investors who want multi-unit stacking on a DSCR file will probably find that product in adjacent Broward submarkets, though this research did not gather sourced pricing on it. The more practical move for a current Weston owner is the reverse: extract equity from the townhome or villa already owned, then deploy it where the unit count is higher. It’s a genuine toss-up whether that second purchase belongs in Broward or farther out, and the answer depends on rent-to-price ratios that shift month to month.
Reminder: verify current local rental rules, taxes, and insurance with qualified local professionals before committing proceeds anywhere.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Weston, Florida?
The property’s rent has to cover its full monthly obligation, with 1.00x as the common baseline, and the loan must fit under a 75% LTV cap. Lenders also look at credit (620 is the usual floor), about 6 months of reserves, and roughly 6 months of ownership from title recording. Final eligibility depends on lender guidelines, credit approval, and property review.
DSCR vs. conventional financing
Two common ways to finance an investment property in Weston, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Weston, Florida when the home is in an HOA community?
Expect the standard DSCR items plus association paperwork: a current dues statement, the lease or a market-rent opinion, and insurance declarations. Dues get counted in the monthly obligation, which can pull coverage down on amenity-heavy communities. Requirements vary by lender and property, so confirm the specifics before ordering an appraisal.
Does Weston have enough duplexes and fourplexes for a small-multifamily cash-out play?
No. NeighborhoodScout puts duplexes and small apartment buildings at 3.63% of units, and the city is dominated by detached homes and large complexes. Weston cash-out files are mostly single-family, townhome, and villa deals. Investors wanting more doors per deed usually have to look at neighboring submarkets.
With Weston prices flat to softer, how much equity can I actually pull out?
It depends on the appraisal, the existing payoff, and the 75% LTV ceiling, and it isn’t a guaranteed figure. With the median sale price down 2.3% year over year, recent buyers may find little room. Long-term holders with low balances are the likeliest to see meaningful proceeds, subject to DSCR and reserves.
The Appraiser’s Read on Weston
Weston shares a zip code with both a $450K townhome and a $1.5M golf-community estate, but they don’t share a rent-to-value profile. The lower-priced attached homes carry the loan on rent, while the estates carry it on appreciation and reserves. In this market, the comp set the appraiser picks and the rent the lender accepts decide the cash-out number, so the property’s tier matters more than the city’s headline median.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349), a non-QM mortgage broker serving investors in 41 markets including Washington, D.C., helps structure DSCR scenarios commonly evaluated around a property’s rental income rather than personal income paperwork, subject to lender guidelines. Recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2025, Lendmire places loans through wholesale investor lenders and is not a direct lender.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. NeighborhoodScout, Weston Real Estate
3. Redfin, Weston Housing Market
4. Zumper, Weston Rent Research
5. soflohomelistings.com — Cost of Living in Weston FL What to Budget in 2026
6. The Real Deal, South Florida Rental Market
7. RentCafe’s Census-based figures
8. RentCafe — Apartments for Rent Weston FL
9. Redfin, Weston Rental Market
10. Prop:Metrics
11. 33327
13. Cleveland Clinic Weston Hospital
14. a 2026 Scotsman Guide Top Mortgage Workplace
15. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Weston Florida · Luxury Rental DSCR Loans In Weston: How STR Rents Are Read · DSCR Cash Out Refinance St. Petersburg Florida
Guides: Investment Property Cash-Out Refinance in Weston, FL · Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.