
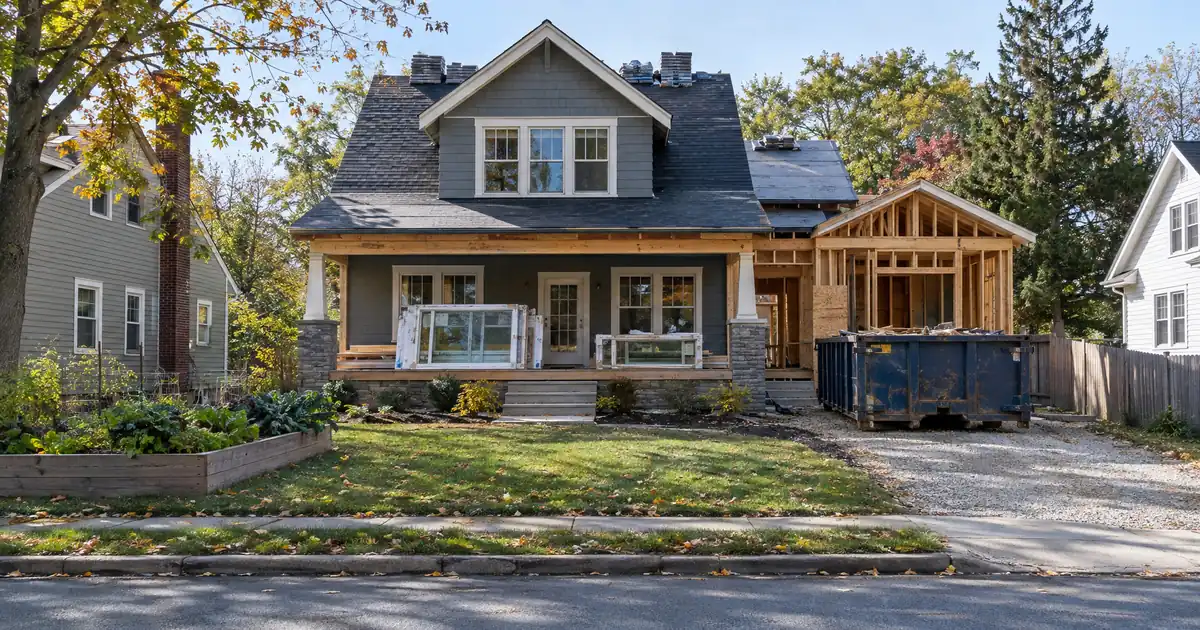
The Quick Read: Yes. Most hard money rehab loans fund a renovation in stages: the lender approves the rehab budget at closing, holds it back, and releases it in draws as each phase of work is finished and verified. You front early costs and get reimbursed, so cash on hand matters as much as the loan terms.
- Up to 100% of the rehab budget can fund in draws against completed work. That is a rehab-budget figure, never a purchase leverage figure.
- Fix-and-flip leverage runs 85%, 90% or 93% of project cost depending on completed projects, always capped at 75% of after-repair value.
- Terms run 6-18 months, interest-only, with no prepayment penalty.
- A DSCR loan is normally one lump sum on a rentable property. It is usually the exit, not the rehab fund.
- All figures vary by lender, property, and experience, and nothing here is a commitment to lend.
How Does a Rehab Loan Fund Work If the Money Isn’t Released at Once?
The loan splits in two at closing. The acquisition portion funds the purchase. The rehab portion goes into a lender-controlled holdback, which is simply a pot of approved money the lender keeps until work is proven done.
A fix-and-flip draw schedule explainer from Yieldstack describes the same pattern: the budget is approved up front but released against completed, inspected work. No federal regulator writes hard money draw rules. Your loan agreement is the rulebook, so read it before you sign.
That is why “100% rehab financing” needs a second look. The budget can be covered in full, yet the cash still arrives after the work, not before it. Budget coverage and release timing are separate questions.
What Does the Draw Cycle Look Like?
Every stage follows the same loop: you pay for the work, request a draw against finished line items, someone verifies it, and funds arrive less any retained holdback. Then you repeat.
1. Scope and budget. You submit a line-item budget, contractor bids and a timeline. A contractor-prepared scope beats a rough guess, because the lender builds the draw milestones from it.
2. Closing. The purchase portion funds. The rehab portion sits in the holdback.
3. First phase. You typically start with your own cash. Some lenders advance a portion up front, but that is the exception.
4. Draw request. You list the finished line items with invoices, photos and lien waivers. Lien waivers are signed statements from contractors that they have been paid and will not file a claim on the property.
5. Verification. A third-party inspector visits, or the lender reviews photos or video.
6. Release. Funds go out less any retained holdback, which is paid at final completion once liens are clear.
Lenders differ on partial credit. Some pay a percentage of a half-finished line item. Others want the item fully installed. Either way, slicing your budget into smaller line items (plumbing rough-in separate from plumbing fixtures, for example) gets you reimbursed sooner.
For a public reference point, the federal FHA 203(k) program publishes its rules. It is an owner-occupant product, not a hard money or DSCR loan, so treat it as a template only. HUD’s 203(k) Borrower’s Acknowledgement states a 10 percent holdback on every draw to protect against liens and unfinished work. Private hard money lenders vary, so read 10% as a reference point, not a norm.
What Do the Stages Look Like?
A stage map shows where your cash is exposed. The exact milestones come from your own budget, but a typical flip runs like this.
| Stage | Typical work | What releases | Your cash exposure |
|---|---|---|---|
| Pre-close | Scope, bids, budget | Nothing yet | Fees, deposits |
| Closing | Purchase | Acquisition portion | Down payment |
| Early work | Demo, structural, permits | First draw | Highest |
| Mid-project | Rough mechanicals, drywall | Second and third draws | Moderate |
| Finishes | Flooring, kitchens, paint | Later draws | Moderate |
| Punch-out | Final fixes, cleanup | Final draw, holdback | Falling |
| Exit | Sale or refinance | Payoff | Closed out |
Your gap is widest early. You have paid for the first phase and the lender has not yet reimbursed you. That is the number to plan around.
How Does Project Scope Change the Stages?
Bigger jobs mean more draws and a longer cash gap. Smaller jobs may need only one or two.
| Scope | Typical draw pattern | Main risk |
|---|---|---|
| Cosmetic (paint, floors, fixtures) | One or two draws | Small budget, little room for overruns |
| Mid-level (kitchens, baths, systems) | Several draws by trade | Inspection scheduling |
| Heavy or structural | Many draws, permit-linked | Hidden conditions, change orders |
A heavy rehab can also push you toward a different product. Ground-up construction runs on its own structure, with up to 90% of cost and 75% of completed value at 3+ completed projects, and draws on a monthly pay-application cycle with lien waivers and a title update. If the house is too far gone to inspect in phases, ask about construction financing instead.
What If a Stage Doesn’t Go to Plan?
Most problems come from paperwork and surprises. Here is how the common ones play out.
| Problem | What usually happens | What you do |
|---|---|---|
| Failed inspection | Draw is held | Fix the item, schedule re-inspection |
| Partial completion | Some lenders pay by percentage, some wait | Split line items finer |
| Early overrun | Later draws can’t absorb it | Use contingency or your own cash |
| Scope change | Budget needs lender approval | Ask before the work starts |
| Permit delay | Release may depend on sign-off | Pull permits early |
On the HUD template, no draw is approved for work that is not complete, and that includes materials not yet installed. HUD Handbook 4240.4 says so directly. Many private lenders follow the same logic, so don’t count on getting paid for a pallet of tile sitting in the garage.
How Much Cash Do You Need Between Draws?
Plan for the down payment, the first phase of work, and the carrying costs while you wait. Run a rough picture. Say a flip is financed at the 90% of project cost tier, with the rehab budget funded in draws. You still cover the remaining 10% of project cost, plus whatever the first phase costs before the first reimbursement lands.
Two things change your carry cost. First, whether interest accrues on undrawn funds or only on money already disbursed. Loan agreements differ, so check the note. Second, how quickly the lender processes draws and schedules inspections. Slow draws mean contractor delays, and delays mean more holding cost. Ask about draw turnaround as carefully as you ask about leverage.
One structuring trick: negotiate the draw schedule so you only fund up to the first or second draw yourself. Contractor payment terms matter too. A contractor who accepts payment on draw receipt shrinks your gap.
Per-draw and inspection fees exist on some loans. Investors sometimes find them buried in the paperwork, so ask for the full fee list up front.
Where Does the Experience of First-Time Investors Differ?
The top leverage tier is reserved for experienced investors. First-time investors qualify at the lower leverage tiers, so the fewer completed projects you have, the more of your own cash goes in. Credit matters too: the minimum score is 620, with additional conditions below 660. Underwriting stays asset-based, meaning the property, the plan, and the exit carry the file. Everything varies by lender, property, and experience.
Across a wholesale network, the pattern is consistent. Files with a contractor-prepared budget, a realistic timeline, and cash set aside for the first phase move through underwriting with fewer questions. Files with a rough estimate and thin reserves get picked apart.
How Does Hard Money Compare to a DSCR Loan for Rehab?
Different tools, different jobs. A DSCR loan, which measures whether a property’s rent covers its monthly payment, is normally a single funding on a property that is already rentable. Staged rehab money belongs to the hard money or construction layer.
| Factor | Hard money rehab loan | DSCR loan |
|---|---|---|
| Funding | Acquisition plus staged rehab draws | Single lump sum |
| Property condition | Can be unfinished | Rentable |
| Term | 6-18 months, interest-only | Long-term, 30-year fixed spine |
| Role | Bridge | Long-term hold |
Many investors refinance out of hard money into long-term DSCR financing once the property is finished, leased and seasoned, and Lendmire brokers that path. The new lender sizes the loan on its own appraisal and rent figure, not your after-repair estimate. Seasoning, the waiting period a lender wants after you take title, is lender policy, not law, and the clock runs from when the deed records. It does not restart when the rehab ends. Cash-out refinances tend to top out around 75% LTV across most of the network, with about 6 months of seasoning common. Qualification stays subject to lender guidelines.
Remember that clearing 1.00 coverage is not the same as positive cash flow. DSCR compares rent to the monthly payment only, so repairs, vacancy and management sit outside it. Lendmire’s complete DSCR loans guide covers the mechanics.
What Happens After the Final Stage?
Exit comes next, and your bridge must outlast the rehab, lease-up, seasoning and underwriting. With a 6-18 month term, that is tight on a heavy project. Build buffers.
Two exits dominate. You sell, or you rent and refinance. If you refinance, the old hard money lien generally rules out the agency delayed-financing exception, but DSCR lenders set their own seasoning, so that exception doesn’t matter for this path.
For a flip, compare the structure against other short-term capital in Lendmire’s piece HELOC vs Hard Money for a Flip: Which Wins at Different Deal Sizes.
Tax treatment varies; consult a qualified professional.
Key Terms Defined
- Draw: a release of rehab money after a phase of work is finished and verified.
- Holdback: the portion of the loan the lender keeps until work is done or liens are cleared.
- Lien waiver: a contractor’s signed statement that they have been paid and won’t claim against the property.
- Loan-to-cost: the loan as a percentage of purchase price plus rehab budget.
- After-repair value (ARV): the estimated value once the work is finished.
- Seasoning: the waiting period a lender wants between buying a property and refinancing it.
Is This Loan Right for Your Project?
Run this checklist before you apply.
- Do you have a line-item budget and contractor bids?
- Can you cover the down payment plus the first phase of work?
- Does your timeline fit inside 6-18 months with buffer for lease-up and refinance?
- Is the property a non-owner-occupied 1-4 unit residential (up to 10 units for ground-up construction)?
- Do you know the lender’s draw turnaround and fee structure?
- Do you have an exit, sale or refinance, that doesn’t depend on optimistic numbers?
If you can answer yes to most of these, a staged hard money loan fits.
Frequently Asked Questions
Do I get the renovation money up front?
Not usually. The rehab budget is approved at closing but held back and released as verified work is completed. Some lenders advance a small portion for long-lead items, but that is uncommon, and you should plan to front early costs.
Can hard money cover 100% of a rehab?
Up to 100% of the rehab budget can fund in draws against completed work, but that is reimbursement, not cash in hand. There is no true 100% purchase program. Purchase leverage is measured as a share of project cost, with every tier capped at 75% of after-repair value.
Who gets paid, me or the contractor?
It depends on the lender. Typically the borrower is reimbursed after paying the contractor, though some lenders pay contractors directly. Lien waivers protect you either way.
Does interest accrue on money I haven’t drawn?
It varies by loan agreement. Some loans charge interest only on disbursed funds, others on the full balance. Check the note before you sign.
Can a DSCR loan fund my rehab in stages?
No. A DSCR loan is typically a single funding on a rentable property. Staged funding belongs to the bridge or hard money layer, and DSCR enters as the long-term takeout.
If you are buying, rehabbing or refinancing an investment property on a short timeline and want to see how the numbers work, Lendmire can help you compare hard money options based on the project, the exit plan, leverage, and your goals.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor financing, helping arrange programs through wholesale and investor-lending channels in 41 markets, including Washington, D.C. DSCR loans are evaluated by the lender on property cash flow rather than personal income, subject to lender guidelines, supporting LLC closings and accommodating investors with four or more financed properties. Scotsman Guide Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Yieldstack: Fix and Flip Draw Schedules
2. HUD 203(k). Borrower’s Acknowledgement
3. HUD Handbook 4240.4 Rev-2, Chapter 5
This article is part of Lendmire’s hard money loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How a DSCR Lender Handles a Release on a Maturing Loan · How Much a DSCR Loan Returns on Rehabs With New Leases · How to Consolidate 5 to 20 Rentals Into a Non-Recourse DSCR Loan
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.