
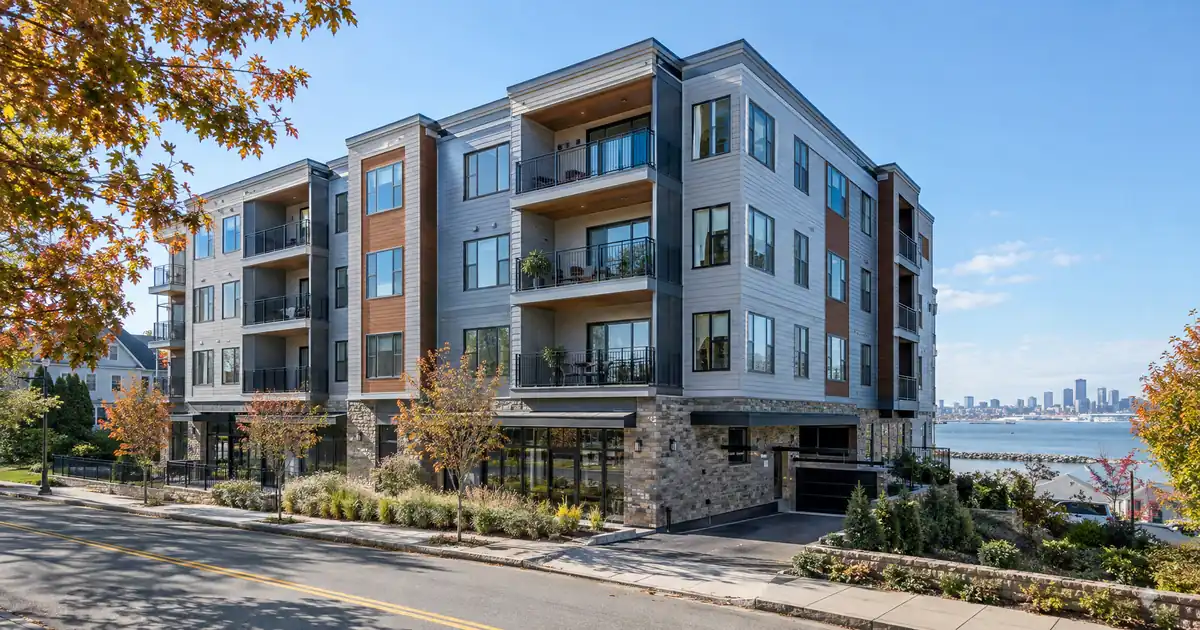
You own a two-family in Revere and want the equity out. Three things usually get in the way: the appraisal, the six-month seasoning clock, and a city median that depends on which website you read. Zillow shows a flat market, Redfin shows a double-digit jump, and Homes.com shows a decline. Cash-out sizing sits on the appraised value of your specific building, so the headline number matters less than the comps behind it.
Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker, helps arrange DSCR financing for Revere, Massachusetts investors as part of a broader non-QM footprint reaching 41 markets, including D.C. This report covers where the coverage math holds in Revere, where appraisal risk sits, and how to think about what you pull out.
DSCR Cash-Out Calculator
Run the cash-out numbers in Revere, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A DSCR cash-out refinance in Revere, Massachusetts suits owners of one-to-four unit rentals, especially two- and three-families, because the loan is underwritten primarily on the property’s rental income measured against its full monthly obligation, with Zillow’s average rent of $2,800 anchoring the demand picture.
- Cash-out leverage tops out at 75 percent LTV, with about six months of seasoning.
- Two- and three-family buildings near Blue Line stations carry the strongest rent stacking.
- Appraisal variance is the main risk, because public price trackers disagree sharply.
- Coverage bands here run near 1.0x to 1.1x on modeled two-family math.
- New Suffolk Downs supply could cap rent growth on older stock nearby.
Revere Market Snapshot
A quick read on the Revere investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $900K median (Redfin West Revere multi-family) |
| Recent appreciation | +0.8% (Zillow Home Values) |
Beachmont Is Where the Equity Story Starts
Beachmont is the strongest submarket for a long-term-rental cash-out thesis in Revere. It is a Blue Line stop with heavy new construction, and tenant demand comes from commuters working in downtown Boston. Two independent local sources, Ascend Property Management and a local broker’s Blue Line analysis, tie station access to durable rental demand. Both are opinion-based, so treat them as directional.
The institutional money is real. Per the Boston Globe, Portico will add 473 apartments and 33,000 square feet of retail at Beachmont Square, and the 475-unit Amaya building has already opened. The City of Revere says 51 of Suffolk Downs’ 161 acres sit in Revere.
This cuts both ways. The redevelopment supports long-run values around the station, which helps appraisals. But hundreds of new units will chase the same renters, and they set a ceiling on what older buildings can ask. Underwrite Beachmont rents conservatively and treat any rent growth as upside, not as the base case.
The Two-Family Math
Two- and three-family buildings are the best fit for a DSCR cash-out in Revere, and the price data explains why. According to a market source, Census-derived mean values run $651,959 for two-unit structures and $579,321 for three-to-four unit structures. Those means lag current listings. Redfin shows a $900K median list price for multi-family homes in West Revere, and Homes.com shows West Revere listings from $855,000 to $1,499,900.
Run the numbers on a two-family valued near that $900K listing median. Assume a modeled rent of $3,100 per unit (a planning input, not a sourced figure) and a refinance at 75 percent LTV. Dividing total rent by the full monthly obligation, including taxes and insurance, produces coverage around 1.0x to 1.1x. That clears the 1.00 baseline common to DSCR programs, but not by much. Eligibility still depends on lender guidelines, credit profile, reserves and property review.
Now the sensitivity. Coverage falls below 1.00 if the units rent closer to the low end of the local range, or if the appraisal forces a larger loan relative to rents. In that case the paths a lender may review include lower leverage, a sub-1.00 program, or an interest-only structure. None is assured, and all depend on the file.
Which rent belongs in the model? Not the average. ApartmentHomeLiving puts average asking rent at $3,344 for two-bedrooms, but the range runs from $2,000 to $7,531. New and luxury buildings pull that average up. Rentometer estimates $3,326 for two-bedrooms and $3,731 for three-bedrooms across all property types. A DSCR appraiser uses rents from comparable properties, so underwrite older triple-decker-style units near the lower end of the spread.
DSCR files in markets like this one typically look like a high-value, low-unit-count building where rent stacking does all the work. The coverage number is usually tight rather than comfortable. The files that go smoothly tend to start with a rent schedule backed by real leases and comps of the same property type, and leverage gets sized around the appraisal instead of the owner’s target. Owners who lead with the cash figure they want, rather than the coverage ratio the rents support, tend to hit surprises.
What Does the Appraisal Do to Your Cash-Out?
The appraisal decides how much equity is available. The 75 percent LTV ceiling applies to appraised value, and Revere’s price data is noisy enough that the same building could be valued very differently depending on the comps chosen.
Zillow puts Revere’s average home value roughly flat over the past year, with only a slight gain. Homes.com shows a 12-month median that has moved down, and Data USA reports a Census-based median property value that sits in the same general range as the other sources. Zillow’s figure is the anchor here, and the others are listed to show how wide the spread can be. The Redfin sale-price series is best treated with caution, since the sample behind it is small and the mix of homes sold can swing the result.
Movoto adds a timing signal, with average days on market at 50 versus 34 a year earlier. Expect slower sales and some appraisal variance.
The practical takeaway: base the refinance on same-type, same-neighborhood comps, not a city median. Leave cushion below the 75 percent ceiling. Equity available is never a guaranteed cash figure. It depends on rent used for lender review, the full monthly obligation, reserves of about six months, and that LTV cap.
The seasoning clock matters too. Cash-out generally requires about six months of ownership measured from title recording. An owner who bought recently and renovated can be inside that window and still wait. Investors comparing paths can read the DSCR cash-out refi mechanics before deciding on timing.
Revere Beach, Wonderland and Cliftondale
Revere Beach and Wonderland share the station-access thesis with Beachmont, with a different tenant mix. The City of Revere describes Waterfront Square as running from Revere Street to Wonderland Station along the beach and largely high-end residential. The MGH Revere Community Health Center sits at Broadway, directly opposite the Revere Beach Blue Line station. Wonderland to Government Center takes about 22 minutes on the Blue Line, which is what makes the commute case work for tenants.
For owners here, rent and price data at the neighborhood level is thin. Homes.com’s Revere Beach sample is small and mixes property types. Treat this area as a demand story, then let the appraisal and a rent schedule do the talking.
Cliftondale and the Broadway corridor are the inland play. The corridor has bus routes, MGH primary care and older two- and three-family stock. Point2Homes reports that about 25 percent of Revere’s rental units, 2,669 of them, were built in 1939 or earlier. That age profile is the triple-decker story. Older buildings can offer the rent stacking the math needs, but they also carry more deferred-maintenance risk, which shows up in appraisals and reserves. The stronger play might be Cliftondale over the beachfront for cash flow. Owners chasing appreciation near the stations could argue the other way.
Orient Heights, Oak Island, Crescent Beach, Prattville and Florida Shores are named Revere neighborhoods, but the research found no reliable price or rent data for them. Skip assumptions and use local comps.
Why Tenant Demand Holds
Revere is a commuter city, and that is the cash-out thesis in one line. Per Census Bureau QuickFacts, the population is 60,012. A market source shows 5,932 workers, or 18.3 percent, live and work in Revere, so most residents work elsewhere in Greater Boston. Data USA reports an average commute of 34.2 minutes.
Resident jobs skew toward Accommodation and Food Services (4,694 people), Health Care and Social Assistance (4,097) and Construction (3,184). Nearby hospitality, outpatient health care and Boston-area employment feed the tenant pool. The City of Revere’s Next Stop Revere data page notes that the city has a larger share of skilled blue-collar workers than the region.
On the rent side, RentCafe reports an average rent of $2,849, up 1.74 percent from $2,800 a year earlier, with two-bedrooms at $3,295. That sample covers buildings with 50 or more units, so it skews toward larger complexes. Renters make up 54 percent of households there. No reliable vacancy figure turned up in the research. Modest rent growth and a “warm” Zillow rating suggest stable demand, but confirm building-level occupancy rather than assuming it.
Skip the Single-Family
Single-family is the weakest DSCR cash-out product in Revere at current prices. Ownership costs run roughly $600,000 or more, while a single rent stream has to cover the whole obligation. A duplex or triplex spreads the same cost across two or three units. That is why the multi-unit math above clears and a single-family at a similar price generally does not.
DSCR programs also generally focus on one-to-four unit properties, so five-plus unit buildings fall outside the standard path. Manufactured homes, log homes and barndominiums fall outside these programs entirely. The loan amount range on standard programs reaches up to $3,000,000, with smaller balances routed through select lenders in the network. Credit tiers generally run from 620 to 700 or higher, with pricing and leverage improving at the upper tiers.
Owners holding title in an entity can often structure the loan through an LLC, subject to lender program eligibility. The DSCR guide explains how the ratio is built, and the guide “Where DSCR and Conventional Diverge” is worth a read for investors weighing traditional personal-income review against property-income underwriting. Massachusetts investors can also review DSCR loans in Massachusetts for state-level context.
Where the Mispricing Sits
The asymmetric opportunity is the older two- and three-family near a Blue Line station, priced against conservative comps rather than new-build asking rents. The market is sending conflicting signals on value, with one tracker showing gains and another showing declines. That leaves room for owners with well-documented rents and clean same-type comps to extract equity at a sensible LTV.
Meanwhile, Suffolk Downs is repricing the area around Beachmont in the long run. Investors who hold older buildings near the station and pull equity at a disciplined leverage level can redeploy capital while the new supply works through. Verify current local rental rules, taxes and insurance with qualified local professionals before you commit.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Revere?
Qualification centers on the property’s rent versus its full monthly obligation, with 1.00 a common baseline. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Leverage tops out at 75 percent on cash-out. Final eligibility depends on lender guidelines, credit profile and property review. You can start your quote to see how a specific Revere building reviews.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Revere, MA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Revere, Massachusetts?
Standard programs generally cover one-to-four unit rentals, with loan amounts up to $3,000,000. Lenders review the rent schedule, appraisal, credit tier and reserves. Manufactured homes, log homes and barndominiums are outside the programs. Requirements vary by lender, borrower and property.
How much equity can you pull from a Revere two-family?
The ceiling is 75 percent of appraised value, less the existing balance. The actual figure shrinks if rent used for lender review, reserves or the appraisal fall short. With public price trackers disagreeing so widely, leave a cushion below the cap instead of planning around the maximum.
Will the new Suffolk Downs supply hurt my Beachmont rents?
It could cap rent growth. The 473-unit Portico project and the 475-unit Amaya building compete for the same commuter renters. Older two- and three-family units usually compete on price and space, but underwrite them at the lower end of local rent ranges.
What credit score ranges may DSCR lenders review for a Revere rental property?
Lendmire arranges DSCR investor loans. Sourced credit tiers are 620, 660, 680 and 700, with 620 the floor. Higher tiers may improve leverage and pricing, subject to lender guidelines.
About Lendmire
Lendmire, NMLS# 2371349, is a DSCR and non-QM mortgage brokerage with investor loan programs in 41 markets, including Washington, D.C. Lenders commonly review DSCR eligibility around property-level rent rather than personal income documentation, subject to lender guidelines. The brokerage helps arrange financing for LLC-owned portfolios beyond conventional financed-property limits. Recognized as a 2025 Scotsman Guide Top Workplace and a 2026 Scotsman Guide Top Mortgage Workplace. Reach the team at 828-256-2183.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow’s average rent of $2,800
2. Redfin
5. local broker’s Blue Line analysis
6. Boston Globe: Suffolk Downs Housing
7. City of Revere: Projects and Initiatives
8. Homes.com
10. Rentometer
11. Homes.com
13. Redfin
14. Movoto
15. MGH Revere Community Health Center
16. Point2Homes
18. City of Revere: Next Stop Revere Data
19. RentCafe: Revere Rent Trends
20. a 2025 Scotsman Guide Top Workplace
21. a 2026 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Revere, MA · Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.