
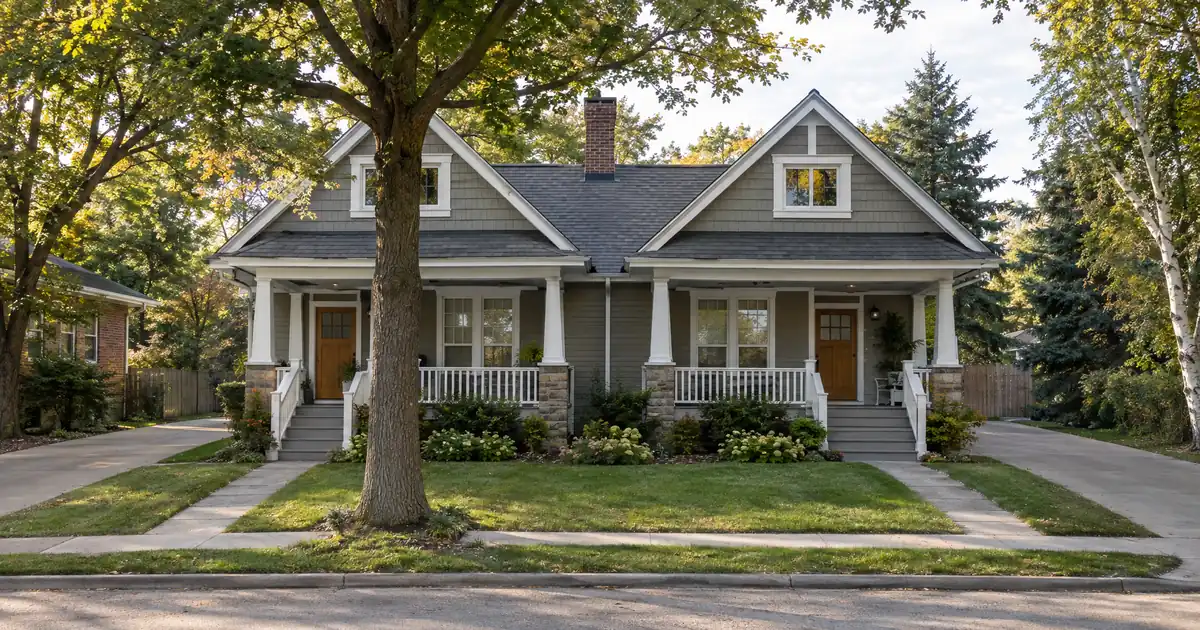
Mequon’s median gross rent runs about $2,426 against a median house or condo value near $557,519, per City-Data’s profile of the city. That ratio decides almost everything about a DSCR cash-out refinance on an investment property here. Single-family coverage is thin, and extracting equity takes structure, not optimism.
Lendmire (NMLS# 2371349) places DSCR investor financing for Mequon, Wisconsin through non-QM wholesale channels that cover 41 markets, including Washington, D.C. This piece is for investors who already own in Mequon and want to pull equity out, not for buyers still shopping. It covers which property types carry a cash-out, where coverage breaks, and how to size a refinance when the comps are thin.
DSCR Cash-Out Calculator
Run the cash-out numbers in Mequon, WI
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
TL;DR: A DSCR cash-out refinance on a Mequon investment property is underwritten primarily on the rental income the property can document against its full monthly obligation, so the property type you hold matters more than the headline equity number.
- Single-family rentals at Mequon values sit near 0.43 percent gross rent-to-value, per City-Data.
- Duplexes and small buildings are the strongest coverage candidates because small multifamily is only 3.31 percent of housing.
- Cash-out caps at 75 percent LTV with about six months of seasoning.
- Roughly 30 sales a month means appraisals can swing hard.
- Only 14 percent of households rent, so the tenant pool is narrow.
Mequon Market Snapshot
A quick read on the Mequon investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $501,600 median (City of Mequon) |
| Typical rents | $1,393 avg asking (Matthews (CoStar data)) |
| University enrollment | 4,577 total (Wikipedia) |
| Employment | 14,039 jobs (UW-Extension Ozaukee) |
| Vacancy | Under 1% claim (Performance Asset Management) |
The Math Starts With a Thin Ratio
A typical single-family rental in Mequon will not clear 1.0x at 75 percent LTV. The gross monthly rent-to-value is about 0.43 percent, which is my own arithmetic on two City-Data figures, not a published metric. A second pass using RentCafe’s average of $2,300 against Zillow’s $567,203 average home value lands around 0.41 percent. Investors usually want something closer to 0.7 to 1.0 percent before the number clears at high leverage.
Run it as a modeled example, not a sourced one. Assume a house at the city’s typical value renting for the City-Data median of $2,426. Divide that rent by a full monthly obligation that includes principal, interest, taxes, and insurance at 75 percent LTV, and coverage lands somewhere around 0.6x. That’s well under the 1.00x benchmark most standard DSCR programs are built around. Rounded down, with taxes and insurance counted. Not close.
So the question for a Mequon owner isn’t “how much can I pull out?” It’s “which of my properties produces rent that supports the loan?” Equity available depends on rent used for lender review, the full monthly obligation, reserves, and the 75 percent ceiling. It is never a guaranteed cash figure. Lendmire’s primer on DSCR loans covers the mechanics if you need the ratio refresher.
What Does a Duplex Actually Clear?
Duplexes and small buildings are where Mequon cash-outs pencil, because two rents sit against one balance. Supply is scarce: NeighborhoodScout puts duplexes, converted homes, and small apartment buildings at only 3.31 percent of housing units, against 73.49 percent single-family detached.
City-Data lists a mean two-unit price of $491,882. Treat that as directional, since the sample is small. (The same source shows a 3-to-4-unit mean of $264,829, which looks like a sample-size quirk, so don’t underwrite off it.)
Model it. Say a duplex is valued near that mean, with each unit renting for $2,000. That sits inside the band where, per RentCafe, 58 percent of Mequon rentals fall between $2,001 and $2,500. Against a full obligation at 75 percent LTV that counts taxes and insurance, coverage comes out around 1.2x. If both units slip to $1,700, it compresses to just above 1.00x. It works, but “barely” is a fair word for the downside case, and a thin cushion deserves a stress test before you commit.
Those are modeled inputs, not market quotes. RentCafe’s rent data also covers only buildings with 50 or more units, so it skews toward newer complexes and says little about small-building rents. Pull your actual leases and let those drive the file.
Lendmire’s page on “The Refi Options” walks through the proceeds-to-coverage tradeoff in more detail.
Appraisal Risk in a 30-Sale Market
Mequon is a small, high-end market, and one or two big sales move the median. Redfin showed a median sale price of $564K in August, down 6.2 percent year over year, with only 28 homes sold that month and 44 days on market against 41 a year earlier. The Census-based figure on the City of Mequon’s housing page is lower, at $501,600, reflecting a different method and vintage. Zillow’s smoothed index shows a mild +2.3 percent over the past year.
Those numbers don’t agree, and that’s the point. An appraiser working from a handful of closed sales can land above or below any headline figure.
Size the refinance on conservative comps, not on the best month you’ve seen. The stronger play may be to order the appraisal assuming a value near the low end of that range, then treat any upside as cushion. Investors who size to a peak comp are the ones who get a lower value, a lower cash-out, and a re-cut file.
Skip the Lakefront Estates
The lakefront and east side carry older estate-style homes at premium rents from a narrow, well-qualified tenant pool, according to a local property manager’s description of Mequon’s three submarkets. That description is marketing copy and gives no price bands, but the logic holds: very high values against a thin rental pool means poor coverage. For DSCR purposes, skip it. If you own an estate and rent it, you’re holding for appreciation, and the cash-out math will not carry a high-leverage refinance.
The central corridors are different. The same manager says they hold newer subdivisions plus duplex and small multifamily stock, which makes them the only submarket where a small-building thesis is plausible. The rural west means larger lots and lower density, which is nice to live in and awkward to underwrite.
Where the Coverage Actually Lives
A few pockets matter for cash-out candidates.
The Port Washington Road corridor is the multifamily and townhome belt. Listings show Apple Orchard Townhomes two-bedrooms from $1,950 on Apartments.com, and Mequon Trail Townhomes from $1,945-plus on Redfin’s Ozaukee rentals page. Those are single-snapshot asking rents, illustrative only. An attached townhome rented in that band at a mid-market value is a better coverage story than a detached house, though still not a slam dunk.
The Cedarburg Road–Mequon Road core surrounds the Mequon Town Center, a mixed-use project of about 28 to 29 luxury apartments next to City Hall, per Shaffer Development. The city also tracks Town Center TID work in its community development objectives. That is new product, not a cash-out candidate for most investors, but it shows where renter demand is being served and sets a ceiling on nearby asking rents.
Concordia’s lakefront campus is a demand anchor for faculty and staff. GM Today describes 200 acres on a 130-foot bluff above Lake Michigan. Don’t oversell it as a student-rental play, though. Concordia University Wisconsin shows 4,577 students in the most recent fall term per Wikipedia, down from 7,751 on the Wisconsin campus in 2012. Enrollment is shrinking. Underwrite the tenant, not the campus.
Thiensville sits next door but is a separate village, so don’t mix its numbers into a Mequon file. A two-bedroom townhome there lists from $1,695-plus on Redfin, and the Mequon-Thiensville Chamber profile notes a roughly 15-acre TIF redevelopment area called Thiensville Crossing.
Tenant Demand: Narrow but Steady
Only 1,320 households (14 percent) rent in Mequon, against 8,124 owner-occupied. That’s a tight niche, and it cuts both ways. Competing rental supply is limited, which helps a well-located duplex. The pool is small, so a single vacancy hurts more.
Point2Homes data shows two-bedroom units are the largest share of rentals, at 34 percent of 490 counted, so underwrite 2- to 3-bedroom product over studios. On the employment side, the City of Mequon cites more than 1,000 businesses across two business parks. Its major employers page names Rockwell Automation, Ascension Columbia St. Mary’s Hospital Ozaukee, HB Performance Systems, and Aurora Advanced Healthcare. Historically, a county profile put several of those at 500 to 999 employees, so treat headcounts as a decade old. Manufacturing, health care, and education have long been the largest job categories. Many residents also commute to corporate jobs in Milwaukee. That mix points to long-term, multi-year leases more than churn.
For vacancy, there’s no neutral Mequon figure. A local manager claims under 1 percent, but that’s a marketing claim. The neutral regional benchmark from Matthews, using CoStar data, shows Southern Wisconsin multifamily vacancy at 5.2 percent in the fourth quarter, with 3,562 units under construction against 1,057 delivered, and rent growth of 2.0 percent. That covers Milwaukee, Waukesha, and Kenosha too, not Mequon alone. Use it as a sanity check. Lenders and appraisers will underwrite a vacancy factor regardless of what the local anecdote says.
Seasoning, Leverage, and Where the Proceeds Go
Cash-out on these programs typically caps at 75 percent LTV, with about six months of ownership measured from title recording. The standard benchmark is 1.00x coverage, and the file generally needs about six months of reserves. Credit tiers run 620, 660, 680, and 700, with 620 as the floor. Those are guideline ranges, not commitments, and they move with the lender, the property, and the borrower. Title held in an LLC is common, subject to lender program eligibility.
Mequon’s story is appreciation and hold, not rent growth lifting the number. Rent trends differ by source: RentCafe shows average rent up 3.01 percent, while Apartments.com showed a 2.1 percent decline over the year to December 2024. Both are aggregator snapshots with different building samples. So size the loan off in-place rent and plan for a modest cushion rather than counting on growth to rescue coverage.
Think about the proceeds as capital with a job. The usual play is to pull equity from a performing duplex and redeploy it into the next small building or a coverage-friendlier market. Pulling it from an estate that barely covers, then parking it, rarely works. Lendmire’s investor refinance options page lays out the rate-and-term versus cash-out distinction, and the comparison of DSCR against conventional is worth a read if you’re weighing a bank refinance first.
What the Deal Desk Sees in Markets Like This
In high-value, low-density suburbs, the common friction point is not documentation. It’s the gap between a strong appraised value and weak in-place rent. The cleaner files from a documentation standpoint tend to arrive with complete leases, entity documents, title, and full property details ready for lender review. In markets like Mequon, the files that stall are usually the ones where the owner assumed the house value would carry the loan, and the coverage ratio said otherwise. A quick coverage check before ordering an appraisal saves a lot of back-and-forth.
Frequently Asked Questions
Can a Mequon single-family rental clear 1.00x on a cash-out?
Usually not at 75 percent LTV. At roughly 0.43 percent gross rent-to-value, a house at typical Mequon pricing lands well under the standard benchmark once taxes and insurance are counted. Lower leverage, a rent well above the city median, or a property bought below market value can change the picture, subject to lender guidelines.
How long do I need to own before I can cash out?
About six months of ownership, measured from title recording, is the typical seasoning guideline on these programs. Lenders vary, so confirm current terms for your specific file before planning the next acquisition around that date.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Mequon, WI, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Will Mequon’s falling median hurt my appraisal?
It can, but the median is a poor guide. With about 28 sales in a recent month and a 6.2 percent year-over-year decline on Redfin, one or two high-end closings can move the number sharply. Plan on conservative comps and treat anything above that as cushion.
Is Concordia a reliable source of tenants?
It’s a demand anchor, not a guarantee. The Wisconsin campus enrolled 4,577 students in the most recent fall term, down from 7,751 in 2012. Underwrite to faculty, staff, and working renters on multi-year leases, not to a student-housing thesis.
Why do I see different rent figures for Mequon online?
The aggregators use different methods, so their figures rarely match. Each source measures rent a little differently, and the numbers you see reflect those choices. Treat the published figures as a rough working range rather than a fixed benchmark, because a lender will typically qualify the loan on your actual leases or a market rent appraisal for the specific unit, subject to lender guidelines.
Next Step
If you own a Mequon duplex or townhome and want to see where coverage lands, reach Lendmire at 828-256-2183 or talk to Lendmire. Investors with holdings elsewhere in the state can also review DSCR loan options for Wisconsin investors. Verify current local rental rules, taxes, and insurance with qualified local professionals before sizing any refinance.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349), a non-QM mortgage broker serving investors in 41 markets including Washington, D.C., helps structure DSCR scenarios commonly evaluated around a property’s rental income rather than personal income paperwork, subject to lender guidelines. A 2026 Scotsman Guide Top Mortgage Workplace and recognized by Scotsman Guide in 2025, Lendmire places loans through wholesale investor lenders and is not a direct lender.
Mequon is a place to hold equity, not hunt coverage. If cash flow is the goal, Milwaukee-area workforce stock has the better rent-to-price math right now, and Mequon’s duplexes are the one corner where the two markets meet.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. City-Data — City Mequon Wisconsin
2. City of Mequon’s housing page
4. Wikipedia
6. Pammke.com — Service Areas Mequon Property Management
8. RentCafe
9. Redfin
10. Apartments.com
11. Redfin’s Ozaukee rentals page
13. cityofmequonwi.gov — Commdev Community Development Fy 2026 Objectives
14. GM Today
15. Concordia University Wisconsin
16. Mequon-Thiensville Chamber profile
17. City of Mequon
18. cityofmequonwi.gov — Econdev Major Employers
19. Apartments.com
20. 2026 Scotsman Guide Top Mortgage Workplace
21. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Mequon, Wisconsin: Equity Math on Thin Rent-to-Value · DSCR Cash Out Refinance in Pewaukee, Wisconsin: Lakefront Equity Versus Townhome Coverage · Cash Out Refinance Investment Property in Fitchburg, Wisconsin: What It Takes to Clear 1.0 Coverage
Guides: Investment Property Cash-Out Refinance in Wisconsin
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.