
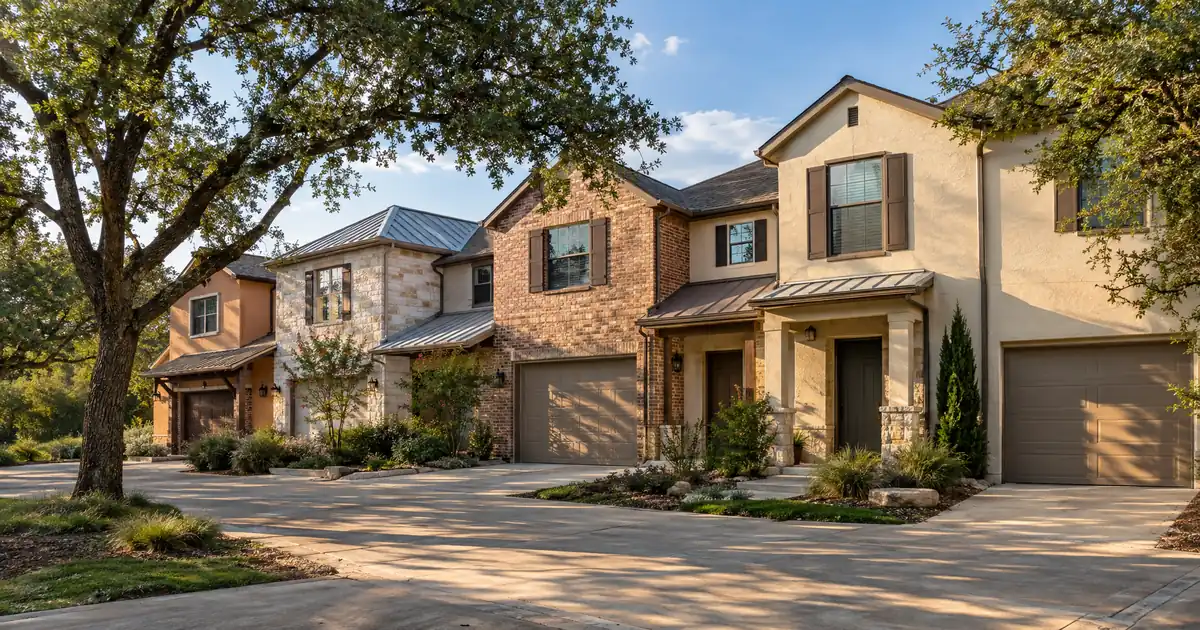
A rental in Whispering Hollow shows how the DSCR math can tighten: NeighborhoodScout puts the neighborhood’s median real estate price and average rent at levels where rent covers only part of the full monthly obligation. Size a cash-out at the 75% LTV ceiling and count principal, interest, taxes, insurance, and HOA dues, and coverage across a plausible range of rate environments lands well below 1.00x, roughly in the 0.8x range, with Texas property taxes and insurance carrying much of the weight. Buda is a market where the LTV cap is rarely the binding constraint. The rent line is. A smaller cash-out, a lower leverage tier, or a property with stronger rent relative to value can move that coverage figure, though a sub-1.00x result would still sit outside most programs’ guidelines. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
TL;DR: A DSCR cash-out refinance in Buda, Texas, is an investor loan sized against the appraised value of a rental already owned and underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds capped by a 75% LTV ceiling and a roughly six-month seasoning requirement, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Buda, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Zumper shows a $2,189 median house rent, the anchor for coverage math.
- Modeled coverage at 75% LTV runs below 1.00x on median Buda price and rent figures.
- Whispering Hollow’s mandatory HOA dues count in the debt-service line.
- Prices are flat to down on two of three sources, so equity must come from basis.
- These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Buda Market Snapshot
A quick read on the Buda investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | 11-unit listing with $20K+/mo projected (Homes.com multi-family listings) |
| University enrollment | 25,049 students (Texas Tribune Schools Hays CISD) |
| Employment | 13,904 employees (Zip-Codes.com Buda) |
The Coverage Math at 75% LTV
Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Coverage on a Buda cash-out is mostly a function of how far below the 75% cap the loan sits. Rent against full PITIA, with taxes and insurance included, clears 1.00x only when LTV comes down well below the ceiling. The sources disagree on value, so the metric has to be named each time.
Redfin shows a median sale price of $411K. Zillow’s home value index reads $352,147. Different measures, not a contradiction. The rent side is steadier: Zumper’s house median is $2,189 and Apartments.com shows an average asking rent of $2,288. Dividing rent by value gives gross rent-to-price near 0.53% on the Redfin figure and 0.62% on Zillow’s. Those are the brief’s own calculations from two cited sources.
Run the numbers this way. The table below is modeled, assuming $2,189 monthly rent, a 30-year fixed structure, and full PITIA built from standard Texas tax and insurance assumptions. It is not market data.
| Cash-out LTV | Coverage at $411K value | Coverage at $352K value |
|---|---|---|
| 75% | about 0.8x | about 0.9x |
| 65% | about 0.85x | about 1.0x |
| 50% | about 1.0x | about 1.2x |
The takeaway: at the cap, median Buda rents don’t cover median Buda debt service. That doesn’t end the file. A lender may review a sub-1.00 program, an interest-only structure, or a lower LTV that pulls the ratio over the benchmark. Most standard programs are built around 1.00x because rent covers the obligation at that level. Eligibility depends on lender guidelines, credit, reserves, and property review, and lower coverage usually means less leverage or more cash left in the deal.
(Texas tax and insurance loads do most of the damage here. Rent growth won’t fix it.)
Equity in a Flat Market: Basis Does the Work
Buda cash-outs are built on equity the investor already holds, not on appraisal lift. Appreciation data is mixed to soft, so the usable equity usually comes from a low original basis, principal paydown, or documented improvements.
Redfin shows median sale price down 1.1% year over year, and Zillow’s index is down 5.8%. Orchard reads up 3.8% on a 30-day sample, but only 56 homes sold in that window, so treat it as secondary. The same report shows 595 homes for sale, up 17.4%, with 48.21% of listings carrying a price drop. Listing-portal data from Movoto points the same way, with price per square foot down about 4%.
Honestly, this is a genuine toss-up for investors weighing a hold against a cash-out. The seasoning clock is simple: about six months of ownership, measured from title recording, before cash-out is available. But a rising-inventory market punishes anyone who assumes the appraisal will come in above purchase price. Underwrite the new value at or near the original basis. Newer-build rentals carry extra risk, since builder inventory sets the comp ceiling.
An appraisal reconsideration request is the normal recovery step when comps come in light. In Buda it works best with closed sales from the same subdivision and the same builder generation, not citywide medians.
Whispering Hollow, Sunfield, and Original Town
Only Whispering Hollow has neighborhood-level price and rent data. It also shows the clearest version of the tension: higher rents don’t fix coverage when price rises in step.
Whispering Hollow. Using NeighborhoodScout’s $541,626 median price and $2,959 rent, gross rent-to-price is about 0.55%, my own calculation. At 75% LTV, modeled coverage including taxes and insurance is about 0.8x before HOA dues. NeighborhoodScout describes medium to large single-family homes, mostly owner-occupied and largely built in 2000 or later, and shows 5.4% real estate vacancy (all housing, not rentals). The Buda EDC notes mandatory monthly HOA dues here. Those dues sit inside the debt-service line, and HOA questionnaire completeness is a common reason a file stalls. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Sunfield. The Buda EDC describes a 2,400-acre master-planned community outside the city limits with about 4,000 homes from seven builders. No price or rent source exists, so this is qualitative: newer single-family stock, a deep builder resale pool, and an appraisal that will compare against active builder inventory.
Original Town. The historic core has no usable price or rent source. Older stock means condition adjustments in the appraisal and a wider spread between comps. Ruby Ranch, Cimarron, and Leisurewoods are also on the EDC’s community list. Nothing sourced supports numbers for them.
Property Type: Single-Family Carries the Math
Single-family rentals are where Buda’s rent evidence is deepest, and the thin multifamily supply means a small comp set on anything bigger. RentCafe shows 26% of Buda households renting. Its apartment survey covers only buildings with 50 or more units, with an average rent of $1,409, down 4.62%. That says little about a small investor’s house.
Duplex-through-fourplex “income stacking” is realistic in only a few deals at a time. Homes.com showed 8 multi-family listings priced from $299,000 to $2.5 million, averaging about 62 days listed. One was a mixed-type portfolio with three single-family homes and eight manufactured homes. Manufactured homes fall outside these DSCR programs. Mixed-type assets also value less cleanly at appraisal, so a cash-out on one needs a separate property-by-property review.
What Could Pressure the Rent Line
Regional apartment supply is the main threat to the rent schedule used at refinance. The Dallas Fed reports Texas multifamily oversupply still weighing on vacancy, with rents declining in most metros, Austin included. Fort Worth Inc. reports landlords leaning on six to eight weeks of free rent. Nearby, a $48.5 million multifamily project called Caroline at Marketplace is slated in Kyle, per Community Impact. Concessions at new buildings compete with Buda houses at the margin. Underwrite to in-place rent, not peak asking rent.
On the demand side, the same Community Impact report says US Foods is investing $65 million in expanding its Buda distribution and warehouse facility, a workforce-rental profile. Zip-Codes.com, citing Census data, lists 1,004 business establishments and about 13,904 employees across Buda ZIP codes, with average household income of $110,417. Texas State University in San Marcos reported a record 47,513 students, up 7%. Community Impact notes much of that growth is online or co-enrolled and the freshman class is the smallest in several years. San Marcos and Kyle are the closer student markets. Buda gets spillover at best.
File Mechanics That Keep a Buda Cash-Out Clean
The checklist is short. A credit score of at least 620, with tiers at 660, 680, and 700. About six months of PITIA in reserves, about nine above $1,500,000. Standard programs run up to $3,000,000, with smaller balances routed through select lenders. Entity documents have to be clean for LLC-titled properties, subject to lender program eligibility. Equity available depends on rent used for lender review, PITIA, reserves, and the 75% ceiling, and it is not a guaranteed cash figure.
Proceeds are the point. A Buda cash-out only makes sense when the capital goes into a next purchase with better coverage than the property it came from. See the investment property refinance options for how rate-and-term compares, and pulling equity out for the mechanics. For the basics, Lendmire’s DSCR walkthrough covers the qualification model, and a comparison of conventional and DSCR loans for investors covers where each fits. Lendmire’s Texas DSCR platform has the statewide program overview.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Buda, Texas?
Qualification rests on the property’s rent against its full monthly obligation (principal, interest, taxes, insurance, and HOA dues), with a 1.00 baseline typical. Expect about six months of seasoning from title recording, a credit floor of 620, and about six months of PITIA reserves. Cash-out is capped at 75% LTV, all subject to lender guidelines.
What are the requirements for an investment property loan in Buda, Texas?
The core items are a lease or rent schedule, entity documents for LLC ownership, a property appraisal, insurance evidence, and reserves documentation. For HOA properties such as Whispering Hollow, a completed HOA questionnaire is part of the package. Manufactured homes, log homes, and barndominiums are outside these programs.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Buda, TX, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Why do Buda cash-outs often need less than the maximum LTV?
Median house rent near $2,189 against Redfin’s $411K median sale price gives gross rent-to-price near 0.53%. After taxes and insurance, modeled coverage falls below 1.00x at 75% LTV. Lowering the loan-to-value, or reviewing a sub-1.00 or interest-only program, is how those files typically get to a workable ratio.
Does Buda’s softer pricing hurt a cash-out?
It narrows the equity cushion. Redfin and Zillow both show prices flat to down, and Orchard shows inventory up 17.4%. Underwrite the appraisal at or near purchase basis, and treat new-build resale discounts as a risk.
What down-payment ranges may DSCR lenders review for Buda investment-property purchases?
Purchase files typically run 20-25% down, subject to lender guidelines. Lendmire arranges DSCR investor loans with standard programs up to $3,000,000. Reach the desk at 828-256-2183.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
One Step Before Ordering the Appraisal
Pull closed sales from the same subdivision and builder generation, then set them beside the in-place lease. Run coverage at full PITIA, HOA dues included, at 75%, 65%, and 50% LTV. In Buda, the number at 65% tells you more than the one at the cap. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C., through wholesale and investor-lending channels. Lenders evaluate DSCR loans on rental income rather than personal income, subject to lender guidelines, which fits LLC-owned portfolios, self-employed investors, and operators scaling past conventional loan caps. The brokerage was recognized by Scotsman Guide in 2025 and named a top-ranked workplace in 2026 as a Scotsman Guide Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Zumper — Rent Research Buda TX
3. Homes.com
4. Texas Tribune Schools Hays CISD
6. Redfin
9. Orchard
10. Movoto
11. Buda EDC
12. RentCafe
13. Dallas Fed
14. Fort Worth Inc.
15. Community Impact
17. Community Impact
18. recognized by Scotsman Guide in 2025
19. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Buda, Texas: Single-Family Equity Extraction · Cash Out Refinance Investment Property in Colleyville, Texas: What It Takes to Refinance a Colleyville Rental · DSCR Cash Out Refinance in Haltom City, Texas: The 2026 DSCR Financing Guide to Denton Highway
Guides: Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.