
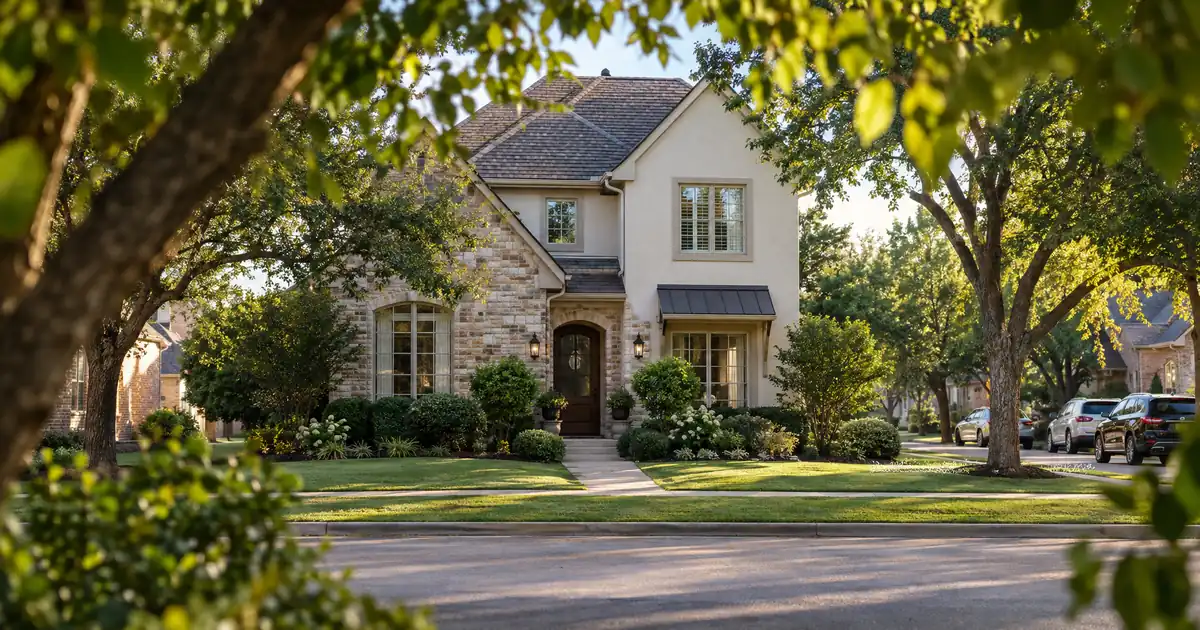
A rental near the Central Colleyville median hits the DSCR math like this. Take a home valued near $763K, the July Redfin neighborhood median. Assume it rents at the citywide median of $3,522 per Zumper. Pull 75 percent LTV against it and add full taxes and insurance to the debt service, and modeled coverage lands near 0.6x. That is well short of the 1.00x benchmark most standard programs are built around.
This is the central problem for equity extraction in Colleyville. The appreciation is real, but the rents don’t carry it.
DSCR Cash-Out Calculator
Run the cash-out numbers in Colleyville, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version: A cash-out refinance on a Colleyville, Texas investment property is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds limited by a 75 percent LTV ceiling and a seasoning period.
- Zillow’s average home value is $925,491, up 1.6 percent year over year, per Zillow.
- Modeled coverage on typical single-family stock sits well below 1.00x at 75 percent LTV.
- Multi-unit stacking is not a realistic fix; recent sales show almost no multifamily inventory.
- Cash-out sizing should follow conservative comps, not the highest ZIP median.
Colleyville Market Snapshot
A quick read on the Colleyville investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $1.0M median (Redfin housing market) |
| Typical rents | $3,520 median gross rent (2024) (City-Data Colleyville) |
| Recent appreciation | +11.0% yoy (Redfin housing market) |
The Price-to-Rent Gap Is the Whole Story
Colleyville is a built-out, high-income suburb. Census Bureau QuickFacts puts population at 26,012, and Point2Homes shows median household income at $218,328. Per City-Data, only 4,582 workers (36.8 percent) both live and work in the city, so this is a bedroom community feeding regional employers rather than a local job engine.
Homeowners dominate here, and the renting share sits well below the state average. Rental supply is thin and mostly large single-family product. The financing problem follows from that.
Three price references frame the range, and each uses a different method:
| Source | Measure | Figure |
|---|---|---|
| Zillow | Average home value index | $925,491 |
| Redfin | Median sale price | about $1.0M |
| HAR.com | Average price | $1,575,390 |
HAR’s figure is an average, so large estates pull it up. For underwriting, the $925K to $1M band is the defensible range.
Rents run $3,522 at the Zumper median and $3,520 median gross rent. HAR shows about $4,864 for a four-bedroom house. Against $925K to $1M values, that is a thin rent-to-value ratio by any workforce-market standard.
Run the Numbers Before Ordering the Appraisal
The coverage math doesn’t clear 1.00x at 75 percent LTV on typical Colleyville product. The modeled figures below use the median rents above and full debt service: principal and interest on a 30-year term at a modeled assumption of 7.03%, plus taxes and insurance at Texas averages. These are illustrations, not sourced market data.
- Zillow-value home at $925K, median rent $3,522, 75 percent LTV: coverage around 0.5x.
- Central Colleyville home near $763K, same rent, 75 percent LTV: around 0.6x.
- Same Central home at 50 percent LTV: around 0.8x. Better, still under 1.00x.
- HAR-average home near $1.58M with a $4,864 four-bedroom rent, 75 percent LTV: below 0.5x.
Cutting leverage to half helps but does not close the gap. Lenders sometimes review such files under a sub-1.00 program, an interest-only structure, or lower leverage with stronger reserves. Those paths usually mean different pricing, more cash left in the deal, and tighter conditions. Whether any of them applies depends on lender guidelines, credit approval, and property review.
Run it as a stress test, not a pitch. A Colleyville single-family rental that clears 1.00x on rent alone would need a materially lower basis, which usually means an older, lower-priced home in the central part of the city.
Equity Extraction Mechanics: 75 Percent, Six Months, Reserves
For an owner already holding a Colleyville rental, the cash-out parameters are straightforward. Eligibility ranges below are typical guidance subject to lender guidelines and not commitments.
- LTV ceiling: 75 percent on a cash-out. The 80 percent purchase figure does not apply.
- Seasoning: about six months of ownership, measured from title recording.
- Coverage floor: a 1.00 benchmark on rent used for lender review against full PITIA, with exceptions reviewed case by case.
- Credit: a 620 floor, with better terms generally available at 660, 680, and 700 tiers.
- Reserves: about six months of PITIA, rising to about nine months above $1.5M loan balances.
- Loan size: up to $3,000,000 on standard programs.
Proceeds are not a fixed number. They depend on appraised value, rent used for lender review, debt service, reserves, and the 75 percent cap. In a market where an owner may hold $400K or more in equity on paper, the binding constraint is usually coverage, not LTV. The guide “The Refi Options” covers the mechanics, and the guide “What Is a DSCR Loan” explains the ratio itself.
Working DSCR brokers see a recurring pattern in high-price suburban markets like this one. Owners anchor on the appreciation headline, run the equity math at 75 percent, and only then discover that rent covers a fraction of the new debt service. Testing coverage first, then sizing the loan to what coverage supports, avoids a dead file.
Which Comps Can You Trust?
Colleyville’s price data conflicts, and the conflict matters because the appraisal sets the cash-out. Redfin shows a three-month median of $1.0M, up 11.0 percent year over year, with 24 days on market. Zillow’s index shows only 1.6 percent growth. Redfin’s November city-level median was down 17.0 percent year over year, at $1.0M on about 20 sales.
Thin volume explains the swings. Orchard’s trailing-30-day report shows a $960,000 median, down 6.5 percent, on 16 sales against 37 a year earlier, with 37.5 percent of listings showing price drops. Days-on-market figures vary by source too.
The practical takeaway is simple. This is an appreciation-led market with volatile medians, not a steady cash-flow market. Sizing a cash-out off peak-price comps is the mistake to avoid. The Zillow-style trend of about 1.6 percent is a more conservative planning input than an 11 percent ZIP median, and appraisals may lean the same way.
No Duplexes Here
Don’t count on multi-unit income stacking in Colleyville. Redfin’s recent-sales mix counted 2 condos, 4 townhouses, and 1 multifamily property out of about 26 sales, per Redfin. Apartments.com shows an average townhome rent of $2,140. That tier may carry better coverage per dollar than large single-family homes, but no sourced townhome sale prices confirm it.
An investor in this market holds single-family product, and appraisals on anything unusual will rely on thin comps.
Who Rents a $3,500 Home
Tenant demand here is professional and regional. DFW International Airport sits a few miles away, and commuter-oriented sources point to airline, aerospace, and healthcare employers across the metro. No verified in-city headcounts exist, so this is a demand thesis, not a sourced employment table. Rent levels are high enough that the likely tenant is a relocating professional on a corporate package, though that is inference.
Rent trend is a warning sign too. Zumper’s listing-based median showed a 12 percent decrease over the prior year. That is a small sample, but it cuts against any underwriting that assumes rents will grow into the debt.
Skip the Estate Tier
Shopping for equity in this market means looking at the lower end of the price range. Central Colleyville’s older stock, with a median near $763K and $298 per square foot, offers the best rent-to-value in the city. The $1M-plus tier is the thinnest on coverage. Reducing leverage on a high-basis asset is expensive in cash terms, and the rent never catches up.
Honestly, the stronger play for many Colleyville owners might be a rate-and-term refinance or a smaller cash-out sized to the coverage number rather than the equity number. The refinance side is worth comparing, though investors prioritizing appreciation could reasonably argue for holding the asset and extracting equity elsewhere.
Texas lenders and brokers publish plenty of generic statewide copy. For the full state picture, see Texas DSCR financing. The Colleyville-specific question remains whether the property’s rent supports the leverage, which statewide averages cannot answer.
Frequently Asked Questions
How do you qualify for a DSCR loan in Colleyville?
Qualification centers on the property’s rent used for lender review against its full monthly obligation, typically with a 1.00 benchmark, a credit floor around 620, and several months of reserves. In Colleyville the rent-to-value ratio is the hurdle, so many files need lower leverage or a lower-basis asset. Eligibility depends on lender guidelines, credit approval, and property review.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Colleyville, TX, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property cash-out loan in Colleyville, Texas?
Expect about six months of ownership from title recording, a 75 percent LTV ceiling, reserves around six months of PITIA, and a loan amount up to $3,000,000 on standard programs. Appraised value drives the proceeds. These are typical guidelines, not guarantees, and they vary by borrower and scenario. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Can a typical Colleyville single-family rental clear 1.00x coverage on a cash-out?
Rarely at 75 percent LTV. Modeled coverage on median-priced homes runs well below 1.00x once taxes and insurance are included. Lower leverage, a lower-priced home, or a program that reviews sub-1.00 coverage may apply, subject to program review.
Why does the Colleyville price data look so inconsistent?
Sources use different methods. Zillow reports an index-based average near $925K, Redfin a median near $1.0M, and HAR an average above $1.5M. Monthly sales are thin, so medians swing. Plan around conservative values rather than the highest figure.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
Watchlist for the Next Quarter
Three indicators will show whether a Colleyville cash-out is worth pursuing:
1. Sales volume against price drops. If monthly closings climb back toward last year’s pace and the share of price-cut listings falls from 37.5 percent, comp depth improves.
2. Zumper-style rent trend. A reversal of the 12 percent annual decline would do more for coverage than any leverage change.
3. Days on market. Redfin’s 24 days against sources showing far longer holds is the gap to watch; convergence signals a market whose comps an appraiser can lean on.
Colleyville’s owner-occupied, built-out character means rents will stay high in absolute terms, but the market will stay a coverage puzzle until prices or rents move toward each other.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income, not the borrower’s W-2 history, which suits LLC-titled portfolios and self-employed investors. All scenarios remain subject to eligibility review and program guidelines. The firm has earned a 2025 Scotsman Guide Top Mortgage Workplace and a 2026 Scotsman Guide Top Mortgage Workplace recognition, two in a row. Investors can reach the team at 828-256-2183 or compare DSCR options.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Zumper
3. Zillow
5. City-Data
7. Point2Homes
8. HAR.com
9. Orchard’s trailing-30-day report
10. Redfin
11. a 2025 Scotsman Guide Top Mortgage Workplace
12. a 2026 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Colleyville, Texas: What Qualifying Takes on Colleyville Rents · DSCR Cash Out Refinance in Grapevine, Texas: The 2026 DSCR Financing Guide to Main Street Rentals · Cash Out Refinance Investment Property in Richardson, Texas: The 2026 DSCR Financing Guide to Telecom Corridor
Guides: Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.