
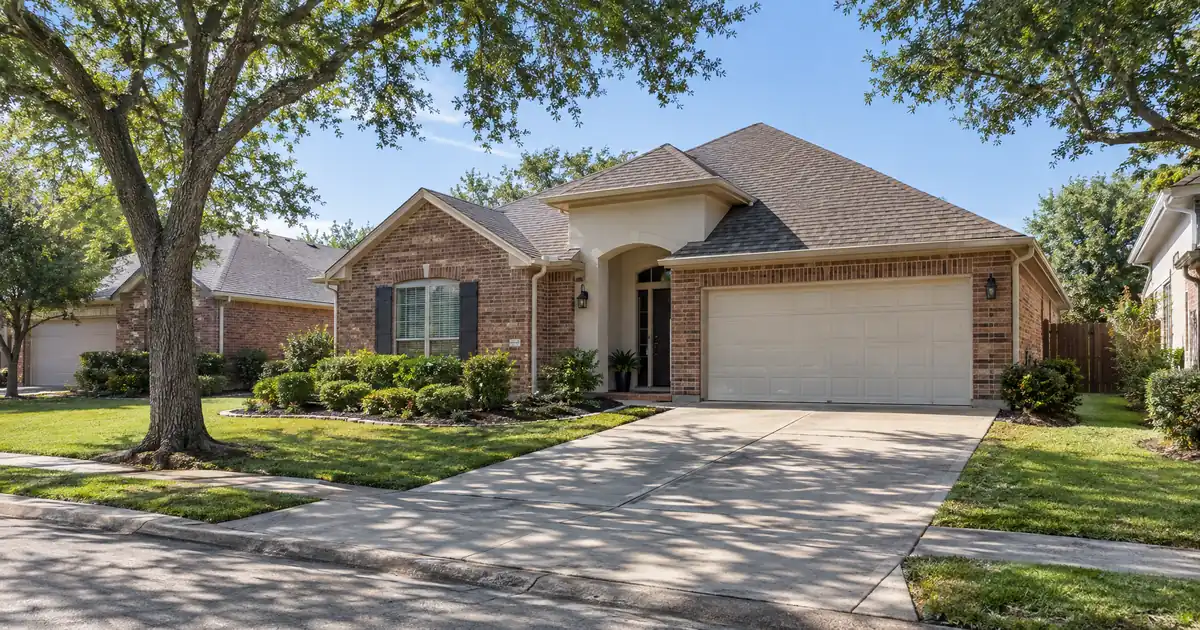
Picture two Richardson landlords holding the same three-bedroom floor plan. One owns in Canyon Creek, where the neighborhood median sale price is $635K per Redfin and the median rent is $2,925. The other owns near Richardson Heights, where the median sits at $377K. The Canyon Creek owner has more equity on paper. The Heights owner has the cleaner cash-out file, because rent covers the debt with far less strain. In Richardson, the math favors the lower-priced tier, and the rest of this piece explains why.
TL;DR: A cash-out refinance on an investment property in Richardson, Texas is a DSCR loan underwritten primarily on the property’s rental income measured against its full monthly obligation, letting an owner who has held title about six months borrow against equity up to a 75% loan-to-value ceiling, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Richardson, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- The citywide median sale price is $462,248, down 1.6% year over year, per Redfin.
- Heights and Berkner Park medians of $377K–$380K give the best rent-to-value ratios found.
- Single-family at the full 75% cap often lands near or below 1.00 once taxes and insurance count. UT Dallas enrolls 30,139 students inside city limits, anchoring long-term renter demand.
- Prices are flat to soft, so cash-out proceeds depend on basis and paydown, not appreciation.
Real estate investors buying in Richardson, Texas can work with Lendmire to access DSCR programs across a 41-market footprint that includes D.C. Lendmire is a mortgage broker that arranges these loans through wholesale and investor-lending channels. The lender, not the broker, reviews and approves the file. This article skips purchase mechanics. It is about the owner who already holds the asset and wants to turn equity into the next deal.
Richardson Market Snapshot
A quick read on the Richardson investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| University enrollment | 30,139 students (UT Dallas) |
| Population | 120,981 population (Richardson IQ) |
| Employment | 130,000+ jobs (Richardson IQ) |
| Vacancy | 1.0% (NeighborhoodScout) |
The Heights and Berkner Park: Where Coverage Holds Up
The lowest-priced single-family tier in Richardson is where a cash-out refinance pencils best. Richardson Heights posted a median sale price of $377K on a small sample of roughly eight sales a month, and Berkner Park sits near $380K. Treat both as directional, since thin samples swing.
Rents in this tier are harder to pin down, and honesty matters here. RentHop’s listing-based data puts three-bedroom rents in ZIP 75080 near $2,400. Redfin’s rental snapshot shows an Arapaho Heights median of $2,675, though that figure is noisy, with a 16% monthly swing. Zillow’s all-property average of $2,299 and its three-bedroom average of $2,522 bracket the range. Apartment one-bedroom numbers from Rent.com (Heights Park near $847, Cottonwood Heights near $1,220) are a different product and shouldn’t be mixed into house-rent underwriting.
Here is the practical read. Against a price near $380K, a rent of $2,400 to $2,675 gives a rent-to-value ratio that beats Canyon Creek by a wide margin. That ratio is what a cash-out file lives on.
Who rents here? Nothing in the research names the tenants directly. The area sits along the DART Red Line and Central Expressway, and Richardson has more than 130,000 jobs inside 27.4 square miles, so commuter demand is a reasonable assumption. It is still an assumption.
Canyon Creek: Big Equity, Thin Coverage
Canyon Creek and the surrounding Prairie Creek and Cottonwood Creek subdivisions in ZIP 75080 are established, mature-lot neighborhoods near UT Dallas, per Winston Alan Realty. Redfin shows the $635K median down 6.8% year over year. The equity is real. The coverage is the problem.
Run a modeled $2,925 rent against full PITIA at a $635K price and 75% LTV, with taxes and insurance included. The coverage number lands in the mid-0.6 range. That is not a rounding issue. To clear the 1.00 baseline, leverage would need to drop dramatically, which shrinks the cash-out proceeds until the exercise may not be worth it. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
There is a second wrinkle. NeighborhoodScout describes Canyon Creek as mostly owner-occupied with roughly 1.0% vacancy, so rental comps are thin and an appraiser may lean on few data points.
The flip point: if the Canyon Creek owner has a conventional-friendly profile (strong traditional employment income, few financed properties), a conventional cash-out may carry lower cost and skip the coverage test entirely. Lendmire’s DSCR-versus-conventional breakdown lays out where that break-even sits. DSCR earns its place when the borrower holds several financed properties, files through an entity, or has traditional personal-income documentation that understate income.
Is There Equity to Pull When Prices Are Softening?
Yes, but the source of the equity matters. Richardson’s citywide median sale price was $462,248 in the most recent Redfin reading, down 1.6% year over year. Richardson Heights was down 12.7%. Canyon Creek was down 6.8%. Berkner Park was down a modest 1.2%. Nobody should underwrite a cash-out on the assumption that appreciation did the work.
Equity in this market comes from three places:
- Original basis. An owner who bought well below current comps has cushion no matter what the last twelve months did.
- Principal paydown. Slow, steady, and more meaningful the longer the hold.
- Forced value. Renovation that shows up in the appraisal, which is the only lever the owner controls.
A properly seasoned file also matters. Programs typically look for about six months of ownership measured from title recording, and the 75% LTV ceiling is a hard cap on cash-out, not a target. What you can actually pull depends on rent used for lender review, full PITIA, reserves (typically about six months of PITIA), and the appraisal. It is not a guaranteed figure.
The appreciation-versus-cash-flow tension is genuine. An investor who bought at the top of the local market and now faces a softer appraisal may find the cash-out window narrower than expected. That is worth knowing before ordering anything.
Running a Modeled Cash-Out
Say an investor owns a three-bedroom near the Heights that appraises around $400,000. Assume a modeled rent of $2,400, which is an assumption for illustration and not a cited market figure. At the full 75% LTV, coverage including taxes and insurance lands in low-0.9 territory. That is under the 1.00 benchmark most standard programs are built around, because at 1.00 the rent covers the payment. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Trim the request to roughly 60% LTV and the same property moves to about 1.00, with a slim margin. The lesson: the Heights tier sits on the borderline, and the loan-to-value dial decides which side of it a file lands on. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Below 1.00, a few structures may be worth a lender’s review. Some programs accept sub-1.00 coverage with lower leverage and stronger credit. Others allow interest-only structuring. A few weigh compensating factors like reserves. None of this is automatic. Qualification stays subject to lender guidelines, credit approval, and property review, and pricing and leverage generally tighten as coverage drops.
Ask first whether sub-1.00 should be used at all. If the only way a property qualifies is by stretching the structure, the better move may be a smaller draw. That is the Richardson trade: a 75% cap is available, but a lower request often produces a healthier loan.
DSCR files in markets like this one typically look like a balancing act between rent and total obligation. Rents are flat, so there’s no growth to lean on. Coverage is decided by what the lender’s rent schedule supports today, and by whether taxes and insurance were priced honestly. The strongest submissions arrive with a current lease or a defensible market-rent comp and a fresh insurance quote before the appraisal is ordered. That sequence avoids surprises that show up late.
Credit tiers generally run from a 620 floor upward through 660, 680, and 700, with stronger scores giving more room on leverage. Loan sizes reach up to $3,000,000 on standard programs, well above anything typical for Richardson single-family. If the property is held in an LLC, that generally works subject to lender program eligibility, so confirm the entity structure before the file goes in. To understand the underwriting logic itself, the guide “What Is a DSCR Loan” covers the basics.
Duplexes, Fourplexes, and the Condo-Deed Catch
Richardson isn’t a small-multifamily market by reputation, but inventory exists. Redfin’s multifamily listings include a 1982-built full duplex in the Woodbridge subdivision, with two 3-bedroom, 2-bath units totaling 2,558 square feet. The stock is older and the units are family-sized.
The rent-side logic is straightforward. Apartments.com shows townhomes averaging $2,352, with a range from $1,410 to $4,300 and three-bedrooms near $2,485. Model two 3BR doors at $2,000 to $2,500 each and you get gross monthly income of roughly $4,000 to $5,000. That is my modeled estimate, not a sourced duplex rent. Stacked income is what can lift coverage above what one single-family rent achieves, as long as the per-door basis stays near the single-family tier. There’s no sourced price band for Richardson duplexes, so lender-ordered rent comps have to settle it.
Here’s the catch. One fourplex in the listings is sold as four individually deeded condominium units. A condo-deeded building may be underwritten differently than a single-parcel fourplex. Ask a lender before going under contract, and before assuming a refinance follows the same path.
The Tenant Base Behind the Appraisal
Cash-out files live and die on the durability of rental demand. Richardson has real depth here.
UT Dallas enrolled 30,139 students in the most recent fall term, split 76% undergraduate and 24% graduate. According to U.S. News, 78% of undergraduates live off campus. That is a large pool of renters near ZIP 75080 and the surrounding corridors.
The employment side is equally specific. Richardson has 130,000-plus jobs for roughly 120,981 residents, per Richardson IQ. Richardson Economic Development calls it the second-largest employment center in the DFW Metroplex, with over 1,000 employers, half in tech. Named employers include State Farm, Raytheon, Texas Instruments, RealPage, and BlueCross BlueShield of Texas. Collins Aerospace is expanding with a $57M investment and more than 570 new jobs. Methodist Richardson Medical Center, a Level III Trauma Center and Comprehensive Stroke Center, added a $46M expansion that supports healthcare-worker demand in ZIP 75082, where the median sale price runs near $565K per Redfin.
Renting is common, too. RentCafe reports 49% of households are renter-occupied. That supports low re-leasing risk for well-kept product.
Skip the Optimism on Apartment Supply
Rents here are flat to soft, and new apartments are the reason. The Apartment Association of Greater Dallas names the Plano East–North Richardson area as a notable construction submarket and says new supply will keep pressing on leasing competition and rent growth. Point2 shows Richardson apartments at a 3.5% rent decrease year over year, and Zillow’s average all-property rent fell $196 from the prior year.
The metro backdrop is stabilizing. DFW occupancy rose to 93.8%, and the Dallas Fed notes excess supply remains in some markets and new properties face longer lease-up timelines. Researchers project rent growth resuming later, but that is a projection.
For a cash-out file, flat rents cut both ways. The rent schedule at appraisal is less likely to be inflated. But there’s little rent growth to lift coverage after closing. Underwrite flat, not rising. Small-unit product in north and northeast Richardson faces the most direct competition from new apartments. The city has even put its Arapaho Center Station redevelopment on hold, citing market conditions. Single-family and larger-unit product competes on a different footing.
Where the Proceeds Go
The cash-out thesis depends on what the investor does with the money. Pulling equity to acquire another rental in a submarket where coverage still works, like the Heights tier, makes a clean argument. Pulling equity to fund a deal in a market where the numbers don’t pencil at current pricing is a different decision, and one worth stress-testing before committing.
Here’s some thinking out loud. The stronger play may be redeploying into the lower-priced richardson tier rather than adding to Canyon Creek, because the rent-to-value ratio is better. Then again, an investor betting on a rebound in Canyon Creek prices could reasonably argue the other way. It’s a genuine toss-up, and the deciding variable is time horizon: cash flow now, or appreciation later.
Another honest caveat. An investor with three or fewer financed properties and strong traditional employment income may find a conventional cash-out cheaper. Past four financed properties, the conventional lane thins out and DSCR becomes the practical path. A fuller look at the refi options helps map that decision, and the state hub for Texas DSCR investor loans covers the broader program picture. Investors who want to see how their own property pencils can call 828-256-2183 or request a quote.
Verify current local rental rules, property taxes, and insurance with qualified local professionals before committing. Redfin’s risk data flags severe heat and wind exposure in the area, so insurance quotes deserve early attention.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Richardson, Texas?
DSCR vs. conventional financing
Two common ways to finance an investment property in Richardson, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The file is built around the property’s rent compared with its full monthly obligation, typically with a 1.00 baseline. Most programs look for about six months of ownership from title recording, a credit floor near 620, and reserves of about six months of PITIA. Cash-out LTV tops out at 75%. Final eligibility depends on lender guidelines, credit, and property review.
What are the requirements for an investment property loan in Richardson, Texas?
Expect a rent-based coverage test, a credit score in the 620-and-up range, reserves, and an appraisal. Entity ownership is common, subject to lender program eligibility. Loan sizes run up to $3,000,000 on standard programs. Manufactured homes, log homes, and barndominiums fall outside these programs.
Will softening Richardson prices limit how much I can pull out?
Yes, they can. Appraisals drive the value, and Richardson Heights medians have fallen 12.7% year over year while the citywide median is down 1.6%. An owner with a low original basis usually still has room. A recent buyer near the top of the market may find the 75% cap shrinks against a lower appraisal.
Does UT Dallas demand help a cash-out refinance in ZIP 75080?
It helps the story more than the math. With 30,139 students and 78% of undergraduates living off campus, the renter pool is durable. But Canyon Creek prices are high relative to rent, so coverage stays thin at high leverage. The demand argument supports the appraisal narrative, not a lower payment.
Can Lendmire help structure DSCR financing for small multifamily investment properties in Richardson? Yes. Lendmire (NMLS# 2371349) arranges DSCR investor loans, and programs for duplexes and small multifamily generally qualify on property rent rather than personal income documentation, subject to lender guidelines. Condo-deeded fourplexes are worth raising early, since they can be reviewed differently.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
Watchlist for the Next Quarter
Three indicators will tell a Richardson owner whether to move on a cash-out now or wait:
- Heights and Berkner Park medians. If the year-over-year declines near $377K–$380K flatten, appraisals stop being a headwind for the strongest coverage tier.
- North Richardson apartment concessions. Watch whether new Plano East–North Richardson supply keeps pulling rents down, since that sets the ceiling for small-unit rent schedules.
- Collins Aerospace hiring. The 570-plus new jobs are the clearest near-term employment catalyst, and their arrival would show up first in rent demand around the Telecom Corridor.
About Lendmire
Lendmire — NMLS# 2371349 — is a mortgage brokerage specializing in DSCR investor loans, helping arrange financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. The model centers on property-level rental income reviewed by the lender rather than W-2 documentation, subject to lender guidelines, suiting entity-owned and multi-property investors. Recognition includes being named a 2026 Scotsman Guide Top Mortgage Workplace and a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Redfin — Richardson Rental Market
3. Redfin — Richardson Heights Housing Market
4. Redfin
5. UT Dallas
6. richardsoniq.com — Richardson
7. NeighborhoodScout — Richardson Canyon Creek
8. Berkner Park sits near $380K
9. RentHop’s listing-based data
10. Zillow’s all-property average
11. Rent.com
13. Redfin’s multifamily listings
14. Apartments.com shows townhomes averaging $2,352
15. Richardson Economic Development
16. Collins Aerospace is expanding
17. Methodist Richardson Medical Center
18. $46M expansion
19. Redfin
20. RentCafe reports 49% of households are renter-occupied
21. Apartment Association of Greater Dallas
22. Point2 shows Richardson apartments at a 3.5% rent decrease
23. DFW occupancy rose to 93.8%
24. Dallas Fed
25. a 2026 Scotsman Guide Top Mortgage Workplace
26. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Richardson Texas · DSCR Cash Out Refinance Harker Heights Texas · Cash Out Refinance Investment Property Hurst Texas
Guides: Investment Property Cash-Out Refinance in Richardson, TX · Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.