
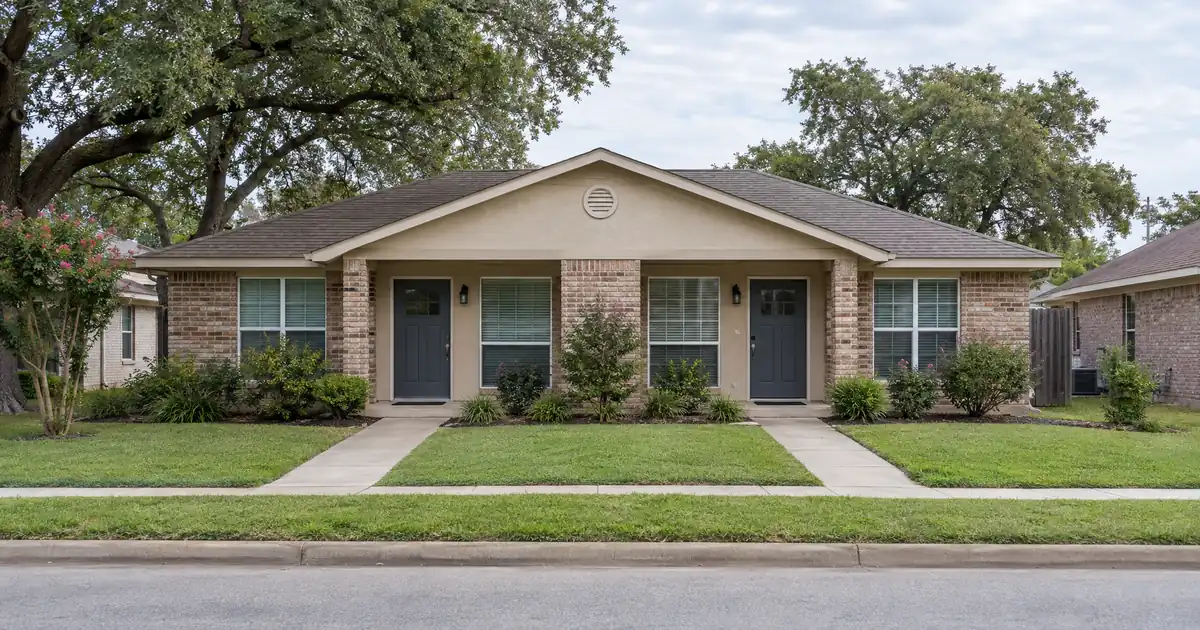
Coverage is the first hurdle on a Harker Heights cash-out, and single-family rent usually doesn’t clear it. Redfin puts the median sale price near $302,000, while Zumper shows a median rent of about $1,400 across all property types. Divide that rent by a full monthly obligation (principal, interest, taxes, and insurance) at 75 percent of value, and a median house lands well under 1.00. The investors who pull equity cleanly here tend to hold two-to-four-unit buildings, where several rent streams sit behind one loan.
DSCR Cash-Out Calculator
Run the cash-out numbers in Harker Heights, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A cash-out refinance on a Harker Heights, Texas rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the lender reviewing ownership seasoning, credit, reserves, and the appraised value behind the loan-to-value cap.
- Single-family at the roughly $302,000 median models below 1.00 coverage including taxes and insurance.
- Newer duplexes modeled in the mid-to-high $300s can land around 1.1x to 1.3x.
- Cash-out caps at 75 percent LTV, with about six months of seasoning typical.
- Prices are softening, so rent-driven value matters more than market lift.
This article skips purchase mechanics. The reader already owns the property, so what follows covers how the equity gets sized, where coverage breaks, and what the proceeds should do next.
Harker Heights Market Snapshot
A quick read on the Harker Heights investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $324,999 March 2026 median list (Wayfinder Builders blog) |
| Typical rents | $1,220 median gross (City-data Harker Heights) |
Why Single-Family Struggles and Stacked Units Don’t
Harker Heights is mostly a single-family city. NeighborhoodScout reports that detached homes are about 68 percent of housing units, and RentCafe shows 4,522 renter-occupied households (38 percent) against 7,440 owner-occupied (62 percent). The renter base is real. The rent-to-price ratio is the weak spot, because a $1,400 rent against a $302,000 house is roughly 0.46 percent a month.
Here are modeled numbers, not sourced market facts. They assume a 30-year structure at a low-7s assumed rate (7.03 percent), taxes near 1.68 percent and insurance near 0.50 percent of value (Texas averages), and 75 percent LTV.
| Property profile | Modeled rent basis | Modeled coverage |
|---|---|---|
| Median single-family, $302K | $1,400 | Under 0.8x |
| Entry-level older house, low $220Ks | $1,400 | Around 0.9x |
| Newer duplex, modeled at $375K | Two units, $1,400–$1,700 each | Roughly 1.1x–1.3x |
Every coverage figure above includes taxes and insurance. Leave those out and the single-family numbers look better than they are. Skip that shortcut, because lenders won’t.
Duplexes change the picture. A builder blog from Wayfinder Builders puts new-construction duplexes in the high $300s. Three-bedroom rents run from about $1,400 up to $1,700 for newer product, per LRG Realty. Two of those units on one loan roughly double the income per dollar of price compared with a house. That’s where coverage improves and where equity pulls get larger.
What Does the Equity Actually Look Like Here?
Expect a smaller pull than the purchase-era spreadsheet suggested. The 75 percent ceiling is firm for cash-out, about six months of ownership (measured from title recording) is typical before a lender will use the new value, and reserves of roughly six months of the full obligation are common. Every one of those is subject to lender guidelines, credit review, and the property’s appraisal.
Redfin shows the median sale price down 4.2 percent year over year, price per square foot at $144 (down 7.1 percent), and days on market at 77 versus 59 a year earlier. Sales ran 112 in June against 113 the year before. Volume is steady, but prices are drifting down and homes sit longer.
That matters for anyone counting on appreciation. Sources disagree here: one broker guide claims double-digit annual gains, which contradicts Redfin’s data, so treat that claim with caution. For planning, assume appraised value won’t jump between purchase and refinance. Proceeds then come from forced appreciation (renovation, lease-up, cleaner operations) rather than a rising tide.
Consider an investor holding a duplex bought below its stabilized value, with both sides now leased at market. The appraisal leans on income and comparable duplex sales, and a 75 percent cap applied to that value sets the ceiling. Whether the coverage ratio clears the lender’s 1.00 baseline then decides how much of that ceiling is usable. Most standard programs are built around 1.00x because the rent covers the payment at that level. Some lenders will look below it, but usually with lower leverage, stronger credit, or added cost. For more on the mechanics, see the guide “What Is a DSCR Loan”.
Duplex, Fourplex, or Triplex?
Fourplexes and duplexes dominate the local multifamily stock, with very few triplexes, townhomes, or condos. A Homes.com snapshot showed 29 multi-family listings on the local multi-family page, priced from $189,000 to about $1.78 million. That spread is wide enough that averages mislead. City-data’s mean price for three-to-four-unit structures is $374,337, but a two-unit average near $122,000 looks like a small-sample outlier, so don’t anchor on it.
The practical takeaway: if the collateral is a triplex, expect a thin comp set and a harder appraisal conversation. Duplexes and fourplexes have local sales to lean on. For borrowers who would rather not wait on a thin appraisal, refinancing a duplex or fourplex is usually the smoother file.
Tenant demand behind those units comes from employment, not students. The Texas Economic Development Corporation reports that the Killeen–Temple–Fort Hood metro has more than 475,000 residents and that Fort Cavazos supports more than 36,000 active-duty personnel, plus civilians and contractors. The Harker Heights Chamber of Commerce names healthcare, retail, and the military presence as the core drivers. HomeSnacks reports a population of 33,595, up 35 percent from 2010, and a median income of $82,685.
Where Coverage Pencils (and Where It Doesn’t)
Older entry-level pockets such as Dana Point and Indian Trail run from the $220,000s, per LRG Realty’s neighborhood guide. Against a rent floor near $1,400, that works out to roughly 0.6 percent of price on modeled math. This is the cash-flow-led product, and it’s where coverage comes closest to 1.00 as a single-family hold.
Bella Charis and other master-planned product run $350,000 to $500,000, and rents above $1,800 still only reach about 0.4 to 0.5 percent of price. That’s an amenity and appreciation play. As a single-family DSCR refinance, it will struggle to clear coverage.
It’s a genuine toss-up for investors weighing the older east-side houses against a newer duplex. The older houses cost less and carry less per-door risk. The duplex has better coverage and more cash-out room, but a thinner buyer pool if you ever sell. Investors who need maximum proceeds lean duplex. Investors who want simple, cheap, low-maintenance holds lean older houses and accept a smaller pull.
Working DSCR brokers see a recurring pattern in military-anchored markets like this one: the file looks strong on demand but weak on the appraisal. Rents are steady and leases renew, yet the value comes in near the original purchase price because comps are soft. The cleanest files arrive with complete leases, entity documents, title, and property details ready for lender review, and with a realistic expectation that the appraisal, not the rent, sets the ceiling.
Coverage below 1.00 isn’t automatically a dead end, but it’s a signal. Options a lender might review include a sub-1.00 program at lower leverage, an interest-only structure, or a reduced cash-out amount. Qualification is subject to lender guidelines, credit approval, and property review. If the investor is reaching for one of those to make a median house work, that’s a hint to reconsider the property type, not just the loan type.
Neighboring Comparisons Worth Knowing
Killeen sits next door at a lower price point. LRG puts Harker Heights three-bedroom rents around $1,400 to $1,700, versus $1,200 to $1,500 in Killeen, while buyers in Harker Heights typically pay $20,000 to $40,000 more for comparable square footage. The rent premium is modest and the price premium is larger. Harker Heights is a stability play, not a yield play. Underwrite the rent at the market level, not at any housing-allowance ceiling.
Zumper’s July apartment data shows average rent down 4.49 percent year over year. Apartment concessions compete with the low end of duplex rents, so underwrite flat-to-down rent, not growth, when sizing a pull. The city’s hospital access helps tenant retention: the City of Harker Heights lists Seton Medical Center in town and Carl R. Darnall Army Medical Center at the post. Baylor Scott & White in Temple is reachable in about 18 to 22 minutes east on US-190.
Using the Proceeds: The Flip Point
What the investor does with the money decides whether the cash-out makes sense. Pulling equity to acquire another duplex or fourplex in the same market, where coverage already works, is the straightforward case. Pulling equity to buy a single-family home at the median price is different, because that new property will itself model below 1.00 and the portfolio gets weaker, not stronger.
Conventional financing may be the better call for an investor with one property, high traditional employment income, and a long hold. A DSCR file usually makes more sense for an entity-owned portfolio, a self-employed borrower, or anyone whose traditional personal-income documentation doesn’t show the rental income cleanly. Here’s conventional vs DSCR on investor loans if that’s the decision on the table. Where some non-QM platforms still pull tax-return review despite the DSCR label, Lendmire, a non-QM mortgage broker, works with wholesale lenders whose programs center on the property’s rent, subject to program terms.
For LLC-held properties, eligibility applies subject to lender program eligibility. More background is in the investor refinance breakdown and on Lendmire’s DSCR cash-out refinance page. Anyone running numbers on a specific duplex can call 828-256-2183. Verify current local rental rules, taxes, and insurance with qualified local professionals before committing to a deal.
DSCR vs. conventional financing
Two common ways to finance an investment property in Harker Heights, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The Blind Spot: One Employer
Harker Heights’ economy leans heavily on one institution. A local broker guide warns that a future base-closure round or major drawdown would hit every community in this corridor, though it argues Harker Heights would hold up better because of its retail tax base. That argument may be right. It’s still an argument, not a guarantee.
Stress-testing matters. Run coverage at a lower rent, say 10 percent below current, and see whether the file still holds at the leverage you’re considering. The flip point is leverage: if the numbers only work at the full 75 percent with current rent, a single-employer market argues for borrowing less than the cap allows. Housing allowances are set to cover median rents, not premium ones, so they won’t protect an above-market lease if demand softens.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Harker Heights, Texas?
The file is reviewed mainly on the property’s rent versus its full monthly obligation, usually with a 1.00 baseline, plus credit (620 is the typical floor), reserves around six months, and seasoning. The appraisal sets the value that the 75 percent cap applies to. All of it is subject to lender guidelines and property review.
What are the requirements for an investment property loan in Harker Heights, Texas?
Typically lenders look at the lease or rent schedule, title, entity documents if an LLC holds the property, insurance, and reserves. Manufactured homes, log homes, and barndominiums fall outside these DSCR programs. Loan amounts generally run up to $3,000,000 on standard programs, with smaller balances routed through select lenders.
Does a median-priced house in Harker Heights cover on rent alone?
Usually not. With a roughly $302,000 median price and rents near $1,400, modeled coverage including taxes and insurance sits well under 1.00. Duplexes and fourplexes, where several rents back one loan, have a much better chance.
Can falling prices shrink a cash-out?
Yes. Redfin shows prices down 4.2 percent year over year with longer days on market, so the appraisal may come in flat or lower. Because the loan caps at 75 percent of appraised value, a softer appraisal directly reduces available equity.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR investor loans across 41 markets, including Washington, D.C. Eligibility is generally reviewed around the property’s rental income rather than personal income documentation, subject to lender guidelines. That serves LLC-structured portfolios and self-employed borrowers who don’t fit conventional boxes. Lendmire has been recognized by Scotsman Guide as a 2026 Top Workplace and is a 2025 Scotsman Guide Top Mortgage Workplace.
For broader investor-financing rules and property-type coverage across the state, see Texas DSCR loans.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Harker Heights Housing Market
2. Zumper: Harker Heights Rent Research
6. LRG Realty
7. Homes.com — Harker Heights TX Multi Family Homes
8. Texas Economic Development Corporation: Killeen–Temple–Fort Hood
9. Harker Heights Chamber of Commerce
10. HomeSnacks
11. LRG Realty’s neighborhood guide
12. recognized by Scotsman Guide as a 2026 Top Workplace
13. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Harker Heights, Texas: Duplex and Fourplex Equity Play · Cash Out Refinance Investment Property in Richardson, Texas: The 2026 DSCR Financing Guide to Telecom Corridor · DSCR Cash Out Refinance in Richardson, Texas: The 2026 DSCR Financing Guide to Telecom Corridor
Guides: Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.