
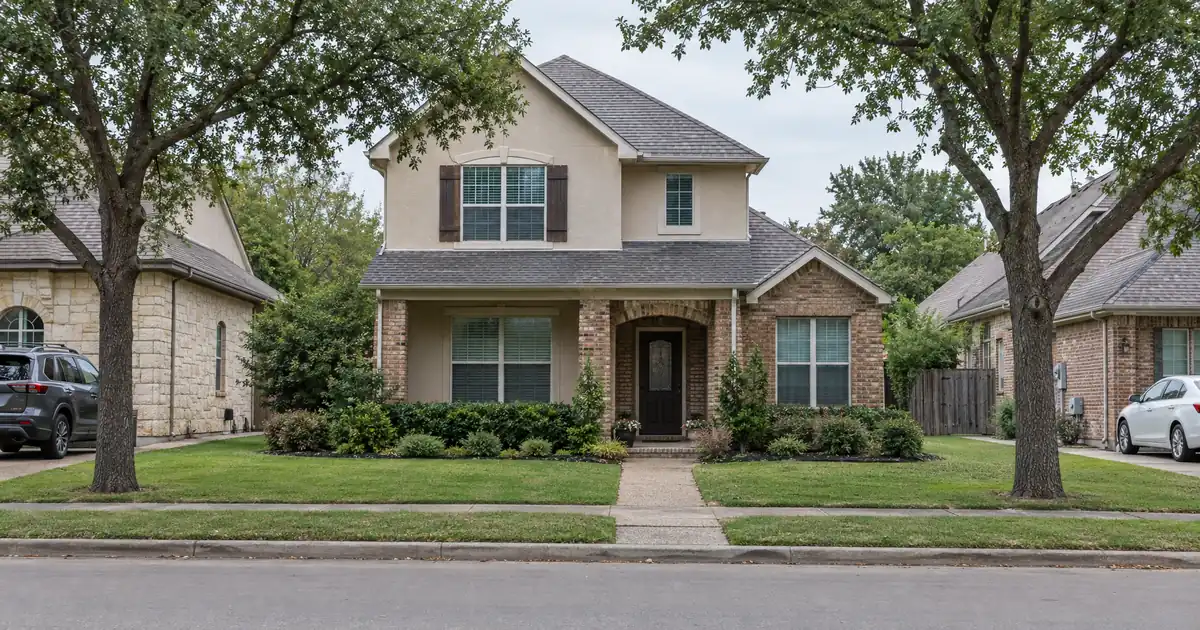
The cash-out files that stall on high-priced suburban rentals rarely stall on credit. They stall when the rent on the lease can’t cover the full monthly obligation at the leverage the borrower wants, and nobody ran that number before the appraisal was ordered. Southlake is that problem in its purest form. Values are high, rents are high, and the ratio between them is thin.
This piece is for investors who already own here and want to pull equity out. Purchase mechanics are a separate topic. Lendmire, a DSCR-focused mortgage broker, arranges these files through wholesale lending channels. Qualification stays with the lender.
DSCR Cash-Out Calculator
Run the cash-out numbers in Southlake, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A cash-out refinance on a Southlake, Texas rental is underwritten primarily on the property’s rent measured against its full monthly obligation. The file has to show a lease or market-rent schedule, recorded ownership past seasoning, and appraised value that supports a 75 percent ceiling.
- Zillow puts the average Southlake home value near $1.31 million, so rent-to-value is the pressure point.
- Modeled at 75 percent LTV with taxes and insurance, a typical single-family rental lands under 0.70x.
- Town Square townhomes and condos carry the lowest entry price in the city.
- Few sales per month means appraisal comps are the weak link.
- Seasoning runs about six months from the recorded title date.
Southlake Market Snapshot
A quick read on the Southlake investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $1.3M median (Redfin Southlake Housing Market) |
| Typical rents | $7,418 rent for 4-bed (HAR.com, Southlake) |
| Employment | 13.4K to 13.6K employees (Data USA, Southlake) |
Rent Against Carry: Where the Southlake Number Breaks
Southlake’s rent-to-value ratio is the lowest of any market a DSCR file will meet in the Dallas-Fort Worth area, and it decides the leverage you can actually use. The 75 percent LTV ceiling is a cap, not a target. On most single-family holdings here, the coverage number won’t reach the 1.00 baseline at that cap.
The sources disagree on both sides of the ratio:
| Source | Metric | Figure |
|---|---|---|
| Zillow | Average home value | $1,313,920 |
| Redfin | Median sale price | $1.3M |
| HAR | Average home price | $2,684,410 |
| Zumper | Median rent, all types | $6,000 |
| HAR | Average 4-bed house rent | $7,418 |
Zumper’s figure is a snapshot more than a year old, and HAR’s averages skew toward estate-tier sales. Treat the table as a range, not a comp. Zumper’s rent against Zillow’s value works out to roughly 0.46 percent a month. HAR’s pair works out to under 0.3 percent.
Here is how the coverage math plays out. The inputs are modeled assumptions, not market data. Rent is divided by full PITIA: principal and interest on a 30-year term plus taxes and insurance at Texas averages. At 75 percent LTV, the citywide-average value and the $6,000 median rent land under 0.70x. Coverage this far below 1.00 doesn’t get fixed with paperwork.
The structures a lender may review at that point are a lower loan-to-value, an interest-only feature, or a sub-1.00 program with stronger reserves and credit. Each is subject to lender guidelines, credit approval, and property review. None is a given. Run the numbers before the appraisal is ordered. The DSCR quote tool is the place to see how a quote looks at different leverage points; the guide “Requesting a Quote” explains the process.
Timarron and the 1990s Pockets: Closest to the Line
Timarron is where a single-family cash-out comes closest to clearing. The community covers about 1,200 acres with roughly 1,550 homes, and one agent page reports a median sale price of $952,000. That is agent marketing data, so read it as directional. It sits well below the citywide averages, and that gap is what helps the ratio.
Run the numbers on a Timarron-priced house at that median with a modeled rent equal to the $6,000 Zumper median. Rent is about 0.63 percent of value a month, so at 75 percent LTV including taxes and insurance, coverage lands in low-0.9 territory. That is still under the baseline. Lower leverage moves it toward 1.00. A lender may also look at a different structure.
Much of Timarron was built in the 1990s and early 2000s, and the Dana Pollard Group neighborhood guide flags dated interiors as the value-add angle. That matters for cash-out because renovation before the refinance can lift both appraised value and achievable rent. If the work is recent, document it: invoices, permits, and before-and-after photos give the appraiser something to adjust with.
The older 1990s neighborhoods on the south and west sides, South Ridge Lakes, Myers Meadow, and Southlake Woods, are described locally as the closest thing to an entry point. No reliable price or rent figures exist for them in the research. Underwrite them from the specific property, not from neighborhood averages.
Town Square Townhomes: The Lowest Carry in the City
The townhome and condo stock near Town Square is where the ratio works best. One agent guide puts townhomes, condos, and smaller single-family homes at $500,000 to $700,000. That is directional, but it is far below the citywide averages, and the carrying cost falls with the price.
Demand there comes from professionals and downsizers who want low-maintenance living. The buildings are close to corporate employment along SH 114. Rent evidence is thin: the visible listings are single snapshots, not medians. Don’t build a file on them. The appraisal’s rent schedule and a signed lease are what the lender will look at.
Condo and townhome cash-outs bring their own paperwork. HOA questionnaire completeness is the usual holdup. A missing or partial questionnaire, or an incomplete budget, stalls the review. Request it early, and confirm that HOA dues are in the PITIA figure you model. A coverage number that ignores dues will come back lower when the lender runs it.
Thin Comps: Plan for Appraisal Reconsideration
Southlake’s sales volume is low, and that puts the appraisal at risk. Redfin’s most recent monthly read counted 19 closings, with homes averaging 56 days on market and selling about 4 percent under list. With that few sales, one estate-tier closing moves the median, and a mid-priced rental can end up compared against sales that are older, farther away, or in a different price tier.
The sources also disagree on direction. Zillow shows average value up 2.5 percent over the past year, with homes going pending in about nine days. Redfin shows the median down 0.56 percent over the same stretch. The mix of homes sold in a small sample likely explains much of the gap. Southlake is flat to slightly soft on price, not a market where appreciation can be assumed into the loan.
Practical moves:
1. Get a broker opinion of value before committing to a leverage target. 2. Assemble an appraisal reconsideration packet in advance: recent in-neighborhood sales, condition adjustments, and any renovation records. 3. Model the loan at a value 5 to 10 percent under your expectation, so a soft appraisal doesn’t kill the file.
Seasoning and the Recorded Title Date
Cash-out on a recent purchase needs about six months of ownership, measured from title recording. The settlement statement documents it. Files that count from contract date or closing-table signature, rather than the recorded date, get kicked back. If you bought recently and plan to refinance, check the county recording date, not the calendar on your closing binder.
For deeper mechanics on how proceeds are sized, see the equity-extraction mechanics and the rate-and-term and cash-out refi details.
Where the Tenants Come From
Southlake’s rental demand is corporate and professional. The Wikipedia employer table, sourced to the city’s economic development office and now dated, lists Sabre Holdings at 2,550 employees, TD Ameritrade at 2,230, Carroll ISD at 1,176, Verizon Wireless at 685, and Keller Williams at 650. TD Ameritrade has since been absorbed into Schwab, so verify current headcounts. Data USA counts about 13,600 employed residents, led by health care and social assistance (2,158), professional and technical services (1,936), and finance and insurance (1,687).
Select Southlake reports 81 percent office occupancy and 95 percent retail occupancy. Healthcare adds another anchor: Methodist Southlake Medical Center is a 54-bed acute care hospital on SH 114. Fidelity’s 332-acre campus sits next door in Westlake.
This supports high-end rents staying occupied. It doesn’t support workforce-rent underwriting, and there’s no student demand, since no university sits in Southlake. Renter share is also very low: AreaVibes puts renter-occupied households 85 percent below the national average. Fewer rental comps also means fewer rent data points for the appraiser.
Reserves and Loan Size on Higher-Value Properties
Southlake values push against two program thresholds. Reserves typically run about six months of PITIA, stepping up to about nine months on balances above $1,500,000. Standard programs run up to $3,000,000, so estate-tier properties can outrun the loan guide before they reach the LTV cap. Reserves documentation needs to be current, with statements showing the funds in the borrower’s or entity’s name.
DSCR vs. conventional financing
Two common ways to finance an investment property in Southlake, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Two more program notes. Credit tiers begin at a 620 floor and price better at 660, 680, and 700. LLC-titled properties can be refinanced subject to lender program eligibility, so have the operating agreement and EIN letter in the file up front.
What Cleaner Files Tend to Look Like
The cleaner files in high-value, low-yield suburbs tend to arrive with the coverage math already run at two or three leverage points. They include a signed lease with a rent history, entity documents, a title report showing the recording date, and a reserves schedule that matches the loan size. The common friction point in markets like this is an appraisal that lands under expectation, followed by a rent figure that was never tested against full PITIA. A file that has already been modeled at lower leverage can pivot. One that hasn’t restarts.
Proceeds: Where the Cash Goes Next
Cash-out proceeds are capital for the next deal, and Southlake itself may not be where they work hardest. Nearby Grapevine apartments, listed on Zillow, sit in a different price tier with, in general, a higher rent-to-price ratio. Multi-unit stock and workforce rentals in adjacent cities weren’t researched here, so treat that as a direction to explore, not a finding.
The guide “What Is a DSCR Loan” is worth a read, and the guide “Where DSCR and Conventional Diverge” is worth a look if you’re weighing both. Lendmire’s Texas DSCR loan programs cover the state-level program picture. Questions on a specific file can go to Lendmire at 828-256-2183.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Southlake, Texas?
The property’s rent must cover its full monthly obligation (principal, interest, taxes, insurance, and any HOA dues) at a ratio of 1.00 or above on most programs. You also need about six months of seasoning from title recording, LTV at or under 75 percent, a 620 or higher credit score, and roughly six months of reserves. All of it is subject to lender guidelines and property review.
What are the requirements for an investment property loan in Southlake, Texas?
For a cash-out on an existing rental, expect a lease or appraisal rent schedule, entity documents if the property is LLC-titled, a title report, insurance evidence, and reserves statements. Given Southlake’s thin sales volume, an appraisal that supports the value is the piece most likely to decide the file.
Why is cash-out harder on Southlake single-family homes than on typical DSCR markets?
Rent runs roughly 0.3 to 0.5 percent of value per month against a carrying cost that is higher. Modeled at 75 percent LTV including taxes and insurance, coverage lands under 0.70x on citywide-average values. Lower leverage, an interest-only feature, or a sub-1.00 program are the structures a lender may review.
Does Town Square housing work better for cash-out than a house in Timarron?
Townhomes and condos near Town Square have the lowest entry prices, so the carry is lighter, but condo files add HOA questionnaire and budget review. Timarron houses sit closer to the 1.00 line at lower leverage. Neither is a sure pass, so test both against full PITIA.
The Biggest Blind Spot: The Appraisal, Not the Rent
The thing most likely to derail a Southlake cash-out is not the borrower or the lease. It’s a thin, lumpy sales market where a single appraisal can come in well under expectation, and where rent-to-value leaves little room to absorb the miss. A borrower who sizes the request off list prices or a neighbor’s estate sale is planning around a number the lender may never see. Model low, get a second opinion of value, and expect the proceeds to be smaller than the headline equity. Verify current local rental rules, taxes, and insurance with qualified local professionals before you commit.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income rather than the borrower’s W-2 history, which suits LLC-titled portfolios and self-employed investors. All scenarios remain subject to lender review and program guidelines. Lendmire is a 2026 Scotsman Guide Top Workplace and a 2025 Scotsman Guide Top Workplace, the two consecutive Top Mortgage Workplace recognitions.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values, Southlake
2. Redfin Southlake Housing Market
5. Zumper, Southlake Rent Research
6. Dana Pollard Group neighborhood guide
7. Wikipedia, Southlake, Texas
8. Select Southlake, Fast Facts
9. Methodist Southlake Medical Center
10. AreaVibes, Southlake Housing
11. Zillow — Southlake TX Apartments
12. announcement
13. 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Southlake TX · DSCR Cash Out Refinance Pflugerville Texas: Access Equity Without Income Docs · DSCR Cash Out Refinance Stephenville Texas: Access Equity Without Income Docs
Guides: Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.