
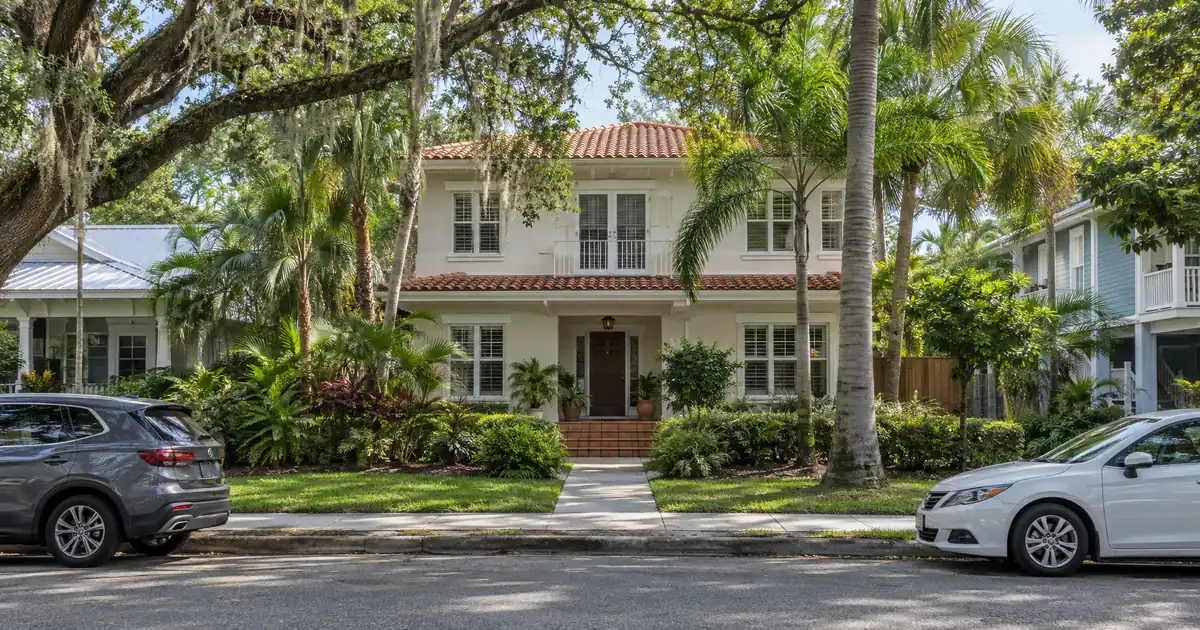
In Coconut Grove, the cash-out constraint is almost never the loan-to-value cap. It is the rent. A refinance at the 75 percent ceiling only works if monthly rent covers the full obligation (principal, interest, taxes, insurance, and any HOA dues), and Grove prices sit so far above rents that the coverage ratio usually decides how much capital comes out, not the equity. Lendmire (NMLS# 2371349) places DSCR investor loans on Coconut Grove, Florida properties through wholesale lending channels reaching 41 markets, including D.C., and the pattern in this neighborhood is consistent: appreciation is abundant, coverage is scarce.
DSCR Cash-Out Calculator
Run the cash-out numbers in Coconut Grove, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A cash-out refinance on a Coconut Grove, Florida rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the neighborhood’s wide gap between price and rent, rather than the equity itself, sets how much capital an investor can realistically pull out.
- Cash-out leverage caps at 75 percent LTV, with about six months of seasoning from title recording.
- Realtor.com sub-neighborhood medians run from roughly $649,500 in Sailboat Bay to $1,948,500 in Grove Center.
- Modeled coverage on mid-priced units falls below 1.00 unless rent reaches the middle of the broker-cited band.
- Older duplex-to-fourplex stock in West Grove is the likeliest structural fit; trophy single-family rarely covers.
Coconut Grove Market Snapshot
A quick read on the Coconut Grove investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $2.85M median (3 months) (Redfin: Coconut Grove Housing) |
| Typical rents | $2,660 asking rent (May 2026) (Miami REALTORS: South Florida) |
| Recent appreciation | +50.5% median (David Siddons Group Q1 2026) |
| University enrollment | 20,104 students (University of Miami) |
| Population | 22,053 population (Niche: Coconut Grove) |
| Employment | 18,003 staff (University of Miami) |
West Grove: Small Lots, High Ground, Unit-Level Rent
West Grove is the most interesting cash-out candidate in the neighborhood, and the least documented. It is the oldest continuously inhabited neighborhood in Miami-Dade County, was designated “Little Bahamas” in 2022, and sits on the Miami Rock Ridge, a limestone spine that WLRN reports averages nine feet above sea level, roughly three feet above Miami’s average. Developers have noticed. Large cube homes are replacing the historic shotgun bungalows, and per Coconut Grove Spotlight, two high-rises with a combined 795 apartments are planned for Douglas Road.
Why does that matter for a refinance? Because the equity story here is land and redevelopment optionality, while the coverage story is unit count. A duplex, triplex, or fourplex stacks several rents against one debt, which is the only mechanism in this neighborhood that plausibly offsets land values. The research turned up no sourced West Grove price or rent figures, and no sourced duplex-to-fourplex rents for the Grove at all. Underwriting there has to start from actual leases and a fresh appraisal, not neighborhood averages.
Two cautions. First, the Douglas Road high-rises and mixed-income projects such as the 345-unit Gallery in the Grove development (including 62 workforce units) add supply near older small-building stock, which can cap rent growth for lower-finish units. Second, some West Grove parcels carry subsidized or income-restricted programs, so an investor should confirm any deed or funding restrictions before assuming market rent. Check local rules, taxes, and insurance with qualified local professionals.
An investor with a small multifamily building bought before the redevelopment wave is the profile that fits. The appraisal may reflect land-driven appreciation, the 75 percent cap limits extraction to a defined slice of that value, and multiple leases give the coverage ratio a fighting chance.
The Price Ladder: Where 75 Percent LTV Meets Real Rent
The Grove is not one market, and a refinance is only as good as the pocket it sits in. The table lays out the segments the research supports, with coverage reads modeled on full obligations including taxes and insurance.
| Segment | Price signal | Modeled coverage read |
|---|---|---|
| Sailboat Bay / Bird Grove East | ~$650K–$725K medians | Near 1.00 only at upper-band rents |
| Older mid-market condos | Softer, longer supply | Thin; appraisal may limit proceeds |
| Grove Center / Village | ~$1.95M median | Far below 1.00 |
| Trophy inland and bayfront | ~$3.0M single-family median | Not a rent-coverage play |
The $649,500 and $725,000 medians for Sailboat Bay and Bird Grove East come from a Team Citron Miami summary of Realtor.com data, and that agent blog is a secondary source, so the property mix behind them deserves a check. They are the only price bands found that sit near normal DSCR loan sizes. Everything above them gets progressively harder.
Now the rent side. One broker source, Luxe Miami Realty, puts a quality two-bedroom apartment or condo in the Grove at $3,500 to $6,500 a month, depending on condition, views, and amenities. That is a promotional claim, not lease data. Data aggregators also disagree: NeighborhoodScout lists an average rental price of $2,984, while Niche puts the median rent at $1,991, and the two use different methodologies. Underwrite toward the low end of any band until comparable leases say otherwise.
Run the numbers on a property in the $700,000 neighborhood at 75 percent LTV, using modeled rent inputs rather than sourced figures. Including taxes and insurance, rent at the bottom of the $3,500-to-$6,500 band produces coverage in the mid-0.70s. Reaching the 1.00 benchmark takes rent in the neighborhood of $4,500. At the Grove Center median near $2 million, rent would need to run at multiples of that band. Not happening on long-term leases.
That is the tradeoff in plain form. A lower LTV improves the ratio, and it also shrinks the proceeds. The cash-out amount and the coverage ratio pull in opposite directions, and the investor’s job is to find the leverage level where both are acceptable.
What Appreciation Actually Hands You at the Appraisal
Headline appreciation in the Grove overstates what an appraiser will credit. Redfin shows a $2.85 million median sale price over the trailing three months, up 68.4 percent year over year. Yet the same page shows median price per square foot at about $1,060, up 23.0 percent. The gap between those two numbers is mix shift: more large, expensive homes closed, and the median jumped accordingly. Redfin’s figure is not a typical price, and it should not be read as one.
Local MLS-based reports point the same way. A Jorge Guanche market report counts 58 single-family closings in the first quarter, up from 46, with the median sold price rising 37.9 percent to $3.0 million. A David Siddons Group analysis says the inland trophy ceiling moved 79.2 percent in three years while the median moved 50.5 percent. Both are agent-authored, so treat them as directional. For contrast, NeighborhoodScout’s median real estate price is $1,073,323, a much lower and probably more representative number for non-trophy stock.
What does this mean for a cash-out? Three things.
- Appraisal, not headline, sets the ceiling. Proceeds are capped at 75 percent of appraised value, and appraisers work from like-for-like comps and price per square foot, not the median.
- Segment matters. The same Siddons analysis puts mid-market and older condo stock at 10.9 months of supply, so appraisals there may come in flat or soft, while waterfront and trophy inland properties sit at or near peak pricing. Trophy appraisals have more room, but those properties rarely cover debt on rent alone.
- Softening at the edges. Redfin shows Northeast Coconut Grove homes taking 100 days to sell versus 64 a year earlier, with a median sale price of $2.3 million. Sellers have less leverage than the year-over-year percentages suggest.
Seasoning is straightforward: about six months of ownership, measured from title recording. An investor who bought before the recent run-up clears it easily. Someone who closed on a property within the past half-year waits, regardless of how the market has moved since.
Loan Mechanics That Actually Bind Here
Four parameters do the work on a Grove file, all subject to lender guidelines and varying by borrower, property, and loan scenario.
- LTV: 75 percent is a hard ceiling for cash-out, and it is lower than the 80 percent purchase figure. Do not mix them up.
- Coverage: a 1.00 benchmark, measured as rent used for lender review against full PITIA. Some lenders will review lower ratios with compensating factors such as lower leverage or more cash in reserve, at different pricing.
- Credit and reserves: a 620 floor, with tiers at 660, 680, and 700, and about six months of PITIA in reserves (about nine months above $1,500,000). Reserve requirements matter in the Grove because balances run large.
- Loan size: standard programs run up to $3,000,000. A trophy property at 75 percent LTV can push past that guide, and smaller balances route through select lenders in the network. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Property type matters too. Condos and townhomes are the most accessible entry point in the neighborhood, and older single-family homes tend to be priced beyond what rent supports. Manufactured homes, log homes, and barndominiums fall outside these programs entirely. LLC-owned properties are reviewed subject to program terms.
For the step-by-step version of how equity extraction is structured, see DSCR cash-out refi mechanics and the refinance side of the program. For a first look at how the underwriting logic works, the guide “What Is a DSCR Loan” covers it, and the side-by-side comparison shows how it differs from conventional financing.
What Happens When the Number Lands Below 1.00?
Many Grove files will. Below 1.00 on long-term rent does not end the conversation, but it changes the options a lender would review. Paths that may apply include a sub-1.00 program, interest-only structuring to lower the obligation used in the ratio, a reduced LTV with a smaller cash-out, or a blend of documented income streams. Each comes with different pricing and reserve expectations, and qualification remains subject to lender guidelines, credit approval, and property review.
Here’s the catch: the more the structure bends to fit the ratio, the less the cash-out resembles what the equity alone suggests. Consider an investor holding a condo with substantial paper equity and rent well under the coverage benchmark. The lender may approve a much smaller extraction than the 75 percent cap implies. That investor is usually better off asking, before applying, how much cash they need and working backward from the coverage ratio.
On files from markets like this one, where value runs far ahead of rent, the common friction point is not credit or seasoning but the gap between the owner’s expectation of proceeds and what coverage allows. The cleaner files tend to arrive with signed leases, a recent rent survey, and an insurance quote already in hand, so the ratio is calculated on real numbers rather than estimates. Files built on owner-estimated rent tend to get re-cut once actual leases surface.
Who Rents in the Grove, and Does It Hold?
Tenant demand rests on healthcare, education, and professional employment, but only some of those anchors sit inside the neighborhood. Ransom Everglades School enrolled 1,147 students with 242 faculty in its most recent published year. The University of Miami is next door in Coral Gables, with 20,104 students, per its Fast Facts as cited on Wikipedia. Brickell’s finance and tech cluster is a short commute away.
The employment picture is mixed. Per Miami Finance Review, Miami metro nonfarm employment was up only 0.2 percent year over year, with financial activities down 2.5 percent and education and health services up 2.5 percent. Health and education growth supports the Grove’s own anchors more than finance does, and the finance decline is a caution for tenants who commute to Brickell. These are metro figures, not Grove figures.
Vacancy needs care. Miami REALTORS shows Miami’s metro multifamily vacancy at 6.6 percent, the lowest among the largest South Region metros, while Miami Finance Review cites 4.6 percent using different data. Call it mid-single digits, depending on source. No Grove-specific vacancy figure was found. Supply is the larger risk: 12-month completions of 11,489 units are outpacing absorption of 8,476, per the Miami REALTORS rental market report, and Miami-Dade asking rents rose only 1.5 percent to $2,660 in the latest month reported by Miami REALTORS. Coconut Grove was not among the submarkets leading rent gains. Underwrite modest vacancy and some concession risk, especially in older, lower-finish units.
Should the Proceeds Go Back Into the Grove?
Probably not into the same pocket. This is a genuine toss-up, and the answer flips depending on the investor’s goal. An investor who wants to keep Grove exposure for appreciation could redeploy into a West Grove small multifamily building or an entry-priced condo. An investor who wants cash flow will likely find better unit-level coverage elsewhere in Miami-Dade. A Marcus & Millichap managing director quoted in South Florida Agent Magazine said investor interest is picking up in North Beach and, more selectively, Little Havana, which suggests small-multifamily buyers are already looking outside the Grove for cash flow.
The cleanest cycle looks like this: a Grove property bought before the run-up, refinanced at or below 75 percent LTV with the coverage ratio holding, and the proceeds deployed into an asset priced closer to its rent. The refinance becomes a rebalancing of the portfolio, not just an equity pull. Investors weighing this can review DSCR loan options for Florida investors to see how the program applies across the state, or get a rental-income loan quote once leases and an appraisal target are in hand. Questions go to Lendmire at 828-256-2183.
The single most useful next step is to pull the actual lease comps and a recent appraisal-grade price per square foot for the specific block, and then test the coverage ratio at 75, 70, and 65 percent LTV. That one exercise shows whether the property is a refinance candidate or an appreciation hold.
DSCR vs. conventional financing
Two common ways to finance an investment property in Coconut Grove, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Coconut Grove?
Qualification centers on the property’s rent measured against its full obligation, including taxes and insurance, with a 1.00 benchmark common across programs. Typical guidance includes a credit floor of 620, about six months of seasoning from title recording, and reserves of about six months of PITIA. Cash-out LTV tops out at 75 percent. Actual eligibility depends on lender guidelines, credit profile, and property review.
What are the requirements for an investment property loan in Coconut Grove, Florida?
Expect a rent-driven review of the property, a credit review, and reserve verification. Standard programs generally run up to $3,000,000, with smaller balances placed through select lenders in the network. Manufactured homes, log homes, and barndominiums are ineligible. Because Grove values are high, the reserve requirement (about nine months above $1,500,000) can matter as much as the ratio.
Why do Coconut Grove appreciation numbers look so different across sources?
Luxury sales skew the medians. Redfin shows a $2.85 million median sale price, but price per square foot rose only 23.0 percent against a 68.4 percent median jump. Agent reports show the same pattern, with trophy properties outpacing the median. Appraisers work from like-for-like comps, so the usable equity is usually smaller than the headline suggests.
Does West Grove work better than the Village for a cash-out?
It may, for small multifamily. Older duplex-to-fourplex stock on West Grove’s limestone ridge stacks several rents against one debt, which the Village’s high-priced single-family stock cannot do. No sourced West Grove price or rent figures exist, though, so lease documentation and a current appraisal carry the analysis. Confirm any deed or funding restrictions before assuming market rent.
What property types work best for DSCR cash-out in Coconut Grove?
Small multifamily and entry-priced condos or townhomes tend to fit best, while trophy single-family rarely covers on rent. Lendmire arranges DSCR investor loans with cash-out leverage capped at 75 percent LTV. Eligibility is subject to lender and program guidelines.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. Eligibility is generally reviewed around a property’s rental income instead of personal income, subject to lender and program guidelines, which suits self-employed investors and LLC-owned portfolios. The firm was recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. $649,500 in Sailboat Bay to $1,948,500 in Grove Center
2. Redfin: Coconut Grove Housing Market
3. Miami REALTORS: South Florida Rents Outpace the Nation
4. David Siddons Group analysis
6. Niche
7. WLRN: West Grove and Little Bahamas
8. Coconut Grove Spotlight: A Small Housing Project
11. Jorge Guanche market report
12. Miami Finance Review: Miami Multifamily Market
13. Miami REALTORS
14. Miami REALTORS: South Florida Rental Market Report
15. South Florida Agent Magazine
16. a 2026 Scotsman Guide Top Mortgage Workplace
17. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Coconut Grove, Florida: Can the Rent Cover a Cash-Out Loan Here? · DSCR Cash Out Refinance in Grove City, Ohio: Will My Rent Cover the Loan After Pulling Equity? · DSCR Cash Out Refinance in Ocala, Florida: Pulling Equity From Southeast Ocala Rentals
Guides: Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.