
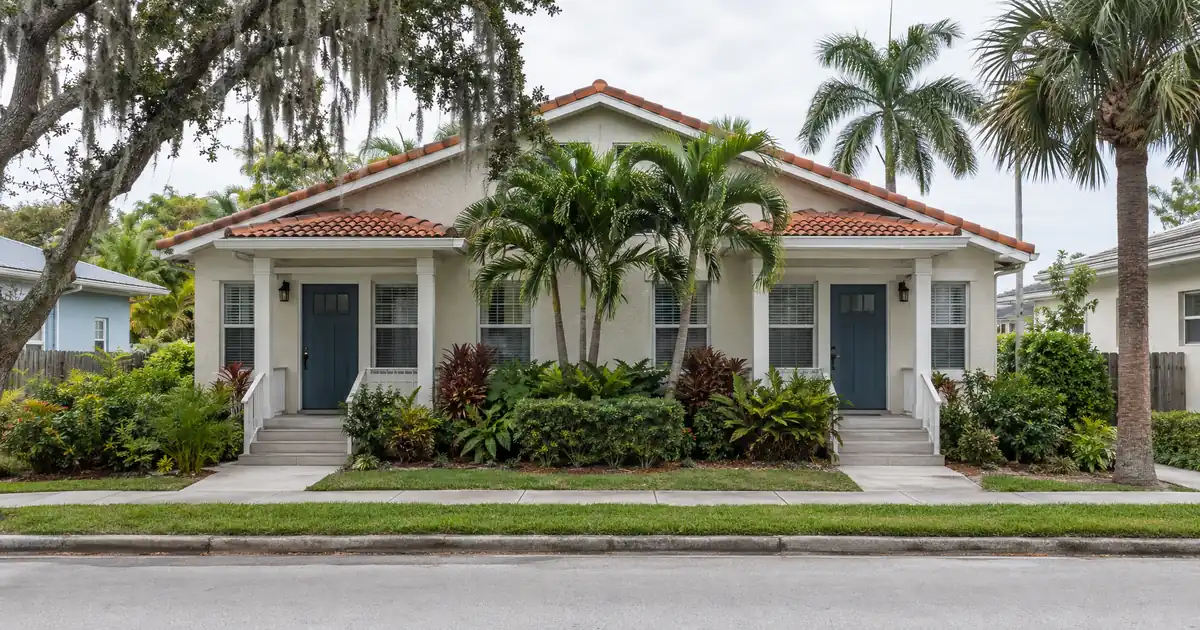
Delray Beach has no single agreed home value. Zillow puts the average at $340,609, down 3.8% year over year, while Redfin reports a median sale price of $474,900, down 12.1%, with homes sitting about 75 days. That is a gap of more than $134,000 on the same city, and for an owner planning a cash-out refinance it matters more than almost any other input. The 75% loan-to-value ceiling is applied to an appraised value, not to either headline figure. Equity extraction here is a valuation-risk exercise first and a coverage-ratio exercise second.
DSCR Cash-Out Calculator
Run the cash-out numbers in Delray Beach, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version:
A DSCR cash-out refinance on a Delray Beach, Florida rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the investor’s personal income documents play a secondary role while value, seasoning, reserves, and credit still get reviewed.
- Osceola Park rents average $3,106 per RentCafe, the highest of any neighborhood RentCafe tracks.
- Cash-out is capped at 75% LTV, with about 6 months of seasoning from title recording.
- Rent roll against full PITIA decides the file. A renovated seven-figure duplex rarely clears 1.00.
- Delray Beach Heights and inland pockets give lower bases against rents near the city average.
- Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Lendmire (NMLS# 2371349) places DSCR investor loans on Delray Beach, Florida properties through wholesale lending channels reaching 41 markets, including D.C. The sections below cover how the cash-out math behaves across Delray Beach’s submarkets, and why a value decline in some data sets changes how proceeds should be sized.
Delray Beach Market Snapshot
A quick read on the Delray Beach investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $4,000/mo (Homes.com Osceola Park duplex) |
| University enrollment | ~3,500 students (Capstone Development Partners) |
| Population | 70,133 population (Census Reporter) |
| Employment | 2,500 employees (LinkedIn) |
What Equity Is Actually There to Pull?
Usable equity in Delray Beach is the appraised value times 75%, minus the existing balance, then reduced by whatever the rent roll will carry. The ceiling is a maximum, not a promise. Proceeds also depend on rent used for lender review, PITIA, reserves of about 6 months (about 9 months above $1,500,000), and the lender’s review, all subject to lender guidelines.
The sources disagree on value for methodological reasons. Zillow’s figure is an index estimate. Redfin’s is a median of closed sales. A local valuation explainer drawing on Regional MLS data from more than 3,200 sales notes the citywide range running from roughly $340,000 up to $510,000–$545,000 depending on the source. Citywide medians also blend $195,000 workforce villas with $1.3 million coastal homes, so they say little about any one property.
Consider an owner who bought a small property more than six months ago and sees a “$475,000 city median” and assumes their house is worth that. It isn’t. The appraiser’s comps decide it. In a market where Redfin shows values down 12.1%, a cautious investor sizes the refinance on a conservative appraisal and treats any upside as bonus proceeds.
Seasoning is the other timing gate. Cash-out typically requires about 6 months of ownership measured from title recording, so an investor who closed a renovation purchase last quarter may need to wait. The refinance side covers the rate-and-term alternative, which can sometimes be reviewed on different timing. Seasoning and eligibility remain subject to program terms.
Osceola Park: Where the Income Stacking Lives
Osceola Park is the strongest cash-out candidate pool in Delray Beach, but only at the right basis. The neighborhood sits just south of Atlantic Avenue. It has been redeveloping from modest bungalows toward renovated and custom homes. RentCafe’s $3,106 average rent here exceeds the citywide average of $2,909 and the $2,382 that Apartments.com reports for the city.
The older bungalow stock often carries guest houses or in-law suites on the same lot, which is what makes income stacking possible. One listed Osceola Park duplex was marketed at $4,000 per month in rent on an 8,293 sq ft lot. Another renovated 1953 duplex nearby, with two 2-bed/1-bath units, a new roof, and impact windows, was listed near $1,100,000.
Those two data points show the whole problem. Run the numbers on the second property as modeled assumptions: rents of $4,000 to $4,500 against a $1.1 million basis at 75% LTV. Rent divided by full PITIA, including taxes and insurance, lands well under 0.65. Skip it as a cash-out candidate. A rough comp analysis might suggest that rent roll “clears” 1.0, and it does not on a full-PITIA basis. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Now model a more typical value. Assume a bungalow duplex appraising at $700,000 with two units at $2,800 each, $5,600 combined (a modeled figure, not a sourced rent). At 75% LTV and including taxes and insurance, full PITIA coverage lands in roughly the 0.87x to 0.95x band across a plausible range of rate environments, so even this rent roll falls just short of 1.0. Keep the same $700,000 value but use the listed duplex’s $4,000 rent roll and coverage drops well below that band. These specifics are modeled assumptions, subject to lender guidelines and a full review of property, leverage, and credit.
Below 1.00 is not a dead end, but it changes the structure. A sub-1.00 program, interest-only terms, lower leverage, or a larger reserve position may be reviewed, each with different pricing and conditions. Qualification stays subject to lender guidelines, credit approval, and property review.
The pattern that comes out of this: in Osceola Park, a $3,000-range two-bedroom unit paired with a basis well under roughly $350,000 per unit is where coverage clears. Above that, the neighborhood trades on land value and redevelopment upside rather than yield.
Delray Beach Heights and the Workforce Tier
Delray Beach Heights, west of downtown, is the better yield play. The neighborhood mixes older homes with new development and sits near major transportation routes. There is no verified per-neighborhood price or rent figure for it, so the case here is structural rather than numeric.
Published benchmarks give a conservative floor. The Palm Beach County Housing Authority payment standards run $2,060 for a one-bedroom and $2,440 for a two-bedroom in ZIP 33445, against $1,800 and $2,130 in ZIP 33444. The county benchmarks are $1,901 and $2,254. These are payment ceilings, not market rents, but they give a lender a defensible underwriting floor beyond a listing estimate.
The ZIP spread also shows where the equity is priced for yield. By one ZIP breakdown, median list prices run from $195,000 in 33484 to $1,300,000 in coastal 33483, a spread of roughly 6x. Rents do not scale at anything like that multiple. That is the appreciation-versus-cash-flow tension in one number. An owner in 33445 or 33484 is working with rent-to-price ratios that support coverage, while an owner in 33483 holds equity priced for lifestyle buyers.
Housing anchors back up the long-term demand. Delray Medical Center is a 536-bed hospital employing over 1,700 people and 700 physicians. Palm Beach Health Network reports 300,000-plus patients a year and one of only two trauma centers in the county. Bethesda Hospital East, a short commute away, is part of a Baptist Health system with a teaching affiliation with FAU’s medical college. Per the Bethesda hospitals’ LinkedIn profile, the Bethesda East and West campuses employ roughly 2,500 people. Shift-based hospital employment is a steadier tenant base than seasonal tourism.
Lynn University in Boca Raton adds a smaller layer. Enrollment is about 3,500, and with only 46% living on campus, more than half of the student body looks off-campus.
The Tiers That Don’t Pencil
Waterfront and coastal Delray Beach is a poor fit for cash-out financing. Tropic Isle and the marina district are deepwater boating enclaves where one broker source puts waterfront homes at $1.5 million to $2.2 million. At those bases, no realistic rent roll covers PITIA at a 75% LTV. Seagate, Palm Trail, and the gated single-family zones trade on cash buyers and lifestyle demand. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Downtown condo towers and the Atlantic Avenue corridor carry high rents but also high acquisition costs, so coverage stays capped. West-side Kings Point is the opposite problem. Zumper shows average rent at $1,695, down 7% year over year, which limits what the rent can support regardless of the purchase price. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Lake Ida and the Grove sit in the middle: family-oriented single-family rentals near downtown, appreciation-driven, with moderate coverage at best. This one is a genuine toss-up. An owner holding a Lake Ida house for a decade may have the most equity of anyone in the city, yet the rent against a high current value won’t carry a full 75% cash-out. In that case a lower-leverage refinance or a smaller draw is the realistic route. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Vacancy, Supply, and What Softer Values Mean
Regional apartment vacancy has roughly doubled, which matters more for large complexes than for small-unit rentals. A secondary broker-blog source citing regional data reports the wider West Palm–Boca–Delray division at an 8.8% apartment vacancy rate, up from 4.5% three years earlier. That figure is metro-division level, not Delray-specific, and it is not from a primary Census or BLS dataset, so treat it as directional.
The investor angle is the property type. Amenity-heavy apartment complexes compete with new supply. A two-to-four unit property in a walkable submarket competes on yard, privacy, and character, and is less exposed to that supply wave. Rent figures across aggregators are broadly consistent, with two-bedroom averages in the $2,600 to $2,900 range per month.
Working DSCR brokers see a recurring pattern in South Florida markets with falling values and still-high rents: the rent side of the file looks fine, but the appraisal comes in below the owner’s expectation, so the 75% ceiling produces less cash than planned. Files that go in with a conservative value assumption and full reserves in hand tend to stay on schedule. Files built on a Zestimate often get re-cut.
How the Proceeds Get Used
The cash-out is not the goal. It funds the next acquisition, so the useful question is whether the new asset covers its own debt. Take proceeds from an Osceola Park refinance and redeploy them toward a workforce duplex in Delray Beach Heights, where the basis is lower and rents sit close to the city average. Coverage on that second property is what keeps a portfolio expanding rather than stretching.
Delray Beach has about 70,133 residents per the U.S. Census Bureau’s ACS data via Census Reporter, up from 66,846 at the last decennial count. The median household income is $82,041 according to Point2Homes. The city is part of a Palm Beach County market of roughly 1.58 million people, so the tenant pool extends well beyond city limits. How DSCR coverage is calculated is straightforward: monthly rent divided by principal, interest, taxes, insurance, and any HOA dues. The standard benchmark is 1.00x, though some programs review lower ratios with offsetting factors.
For the broader program picture, Lendmire’s DSCR cash-out refinance page covers structure, and the side-by-side comparison shows how it differs from a conventional refinance. Statewide program context is on Lendmire’s Florida DSCR platform. Investors can request a quote or call 828-256-2183. Verify current local rules, taxes, and insurance with qualified local professionals before underwriting.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Delray Beach, FL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Delray Beach?
The file is built around the property’s rent used for lender review against its full PITIA, with a typical minimum of 1.00. Lenders also review credit (a 620 floor, with better tiers at 660, 680, and 700), about 6 months of reserves, and about 6 months of seasoning from title recording. Cash-out is capped at 75% LTV. Final eligibility depends on lender guidelines and property review.
What are the requirements for an investment property loan in Delray Beach, Florida?
Typical guidance covers the 1.00 coverage benchmark, a credit floor of 620, reserves around 6 months of PITIA, and loan amounts up to $3,000,000 on standard programs. Manufactured homes, log homes, and barndominiums fall outside these programs. Details vary by borrower, property, and loan scenario.
Does a falling home value in Delray Beach shrink the cash-out amount?
Yes, directly. Proceeds come from the appraised value times the LTV ceiling minus the current balance, so a lower appraisal cuts the number even if rents hold. Zillow and Redfin both show year-over-year declines (3.8% and 12.1%), so conservative sizing is prudent.
Which Delray Beach properties tend to clear coverage on a cash-out?
Duplexes and bungalows with guest houses in Osceola Park at moderate bases, and workforce rentals in Delray Beach Heights. Waterfront and coastal homes rarely do, because acquisition cost outruns achievable rent.
Can an LLC-owned Delray Beach rental be reviewed for DSCR financing?
Yes, subject to lender program eligibility. Lendmire arranges DSCR investor loans, and DSCR programs are reviewed around the property’s rental income rather than personal income documentation.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that helps arrange investor financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR eligibility is generally reviewed by the lender on the property’s rental income rather than personal income documentation, subject to lender guidelines, which works for self-employed investors, LLC operators, and portfolios above four financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
5. Capstone Development Partners
9. Palm Beach County Housing Authority payment standards
12. Baptist Health, Bethesda Hospital East
13. courses.flvc.org — College Lynn University
14. Zumper
16. Point2Homes
17. 2025
18. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Delray Beach Florida · Luxury Rental DSCR Loans In Delray Beach: How STR Rents Are Read · Cash Out Refinance Investment Property in Pompano Beach, Florida: How the Rent Math Clears at 75% LTV
Guides: Investment Property Cash-Out Refinance in Delray Beach, FL · Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.