
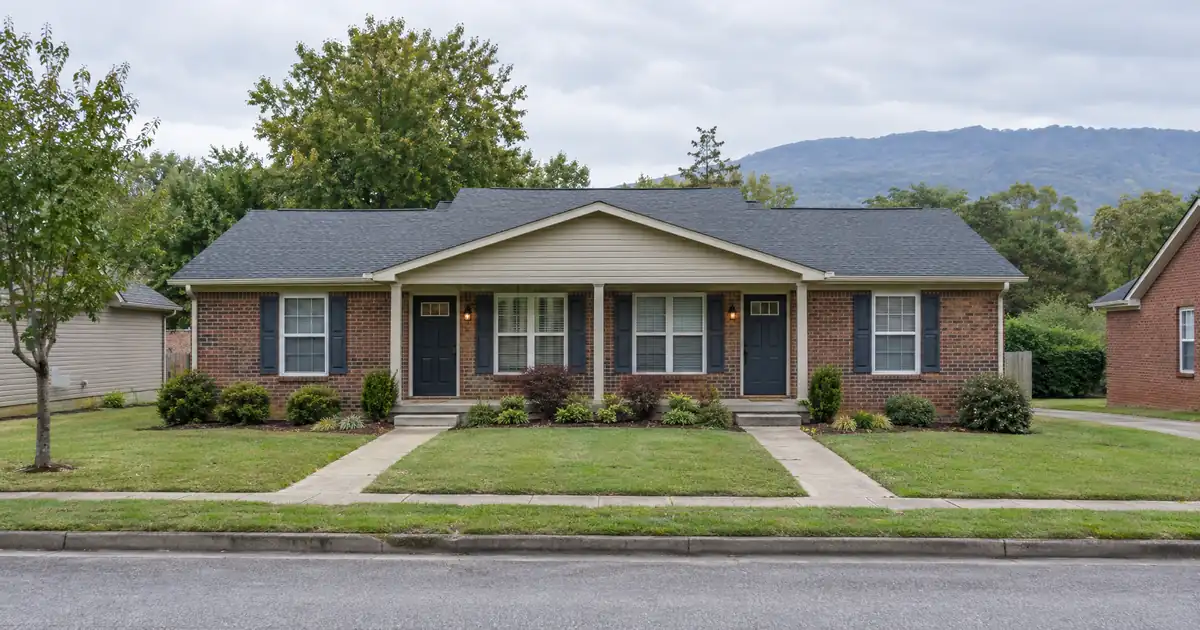
Three signals will shape Tullahoma equity pulls over the next 6 to 18 months. Redfin shows homes taking 67 days to sell, up from 50 the year before. Redfin’s new-construction page lists 34 new builds at a $319K median list price. And a large mixed-use proposal off North Jackson Street could add rental supply. Investors sitting on paid-down or appreciated rentals here should expect appraisers to work with thin comps and lenders to run the coverage math strictly.
TL;DR: A DSCR cash-out refinance on a Tullahoma, Tennessee rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds capped by a 75 percent loan-to-value ceiling and sized after appraisal, reserve and seasoning review, all subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Tullahoma, TN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Redfin’s median sale price sits near $300K, and other sources run higher. (Redfin)
- Rent-to-value is thin: $1,200 average rent against prices in the $300K range. (Zumper)
- Older bungalows and ranches at the low end of the price range carry the best coverage math.
- Seasoning runs about six months from title recording before a cash-out is on the table.
- Tenant demand rests on AEDC, a hospital and a college, not one factory.
Tullahoma Market Snapshot
A quick read on the Tullahoma investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 25 sales (Redfin) |
| Typical rents | $815 median contract (City-Data) |
| University enrollment | ~7,000 students (Motlow State Community College) |
| Employment | Hospital ~450 staff (tullahoma.org — Move to Tullahoma) |
Why Timing and Comps Matter Before You Refinance
Tullahoma is a thin-trade market, and that changes how equity extraction should be planned. Redfin’s Tullahoma market data shows the median sale price running roughly in the vicinity of the low-to-mid range for the area and up modestly year over year, with only a small number of homes sold in the month tracked. An earlier Redfin snapshot showed a noticeably lower median and a year-over-year decline. Both figures come from the same city and the same source, and the swing between them is mostly a mix effect: a few new-construction sales can move the median by a wide margin.
The sources also disagree with each other. Homes.com puts the 12-month median sale price at $385,000, up 4 percent. That is a different methodology and a different sample, so this article treats Redfin’s roughly $300K as the primary citywide reference and the Homes.com figure as the high end of the range. Zillow’s home value index sits at $263,387, up 4.8 percent, which is closer to the older, lower-priced stock that most rental investors actually hold.
What does that mean for a cash-out? An appraiser working a market with 25 monthly sales and a 67-day average marketing period has few recent, truly comparable sales to lean on. The valuation that supports a 75 percent loan-to-value ceiling may land at the conservative end of the range. Sizing the proceeds off a Homes.com-style number is the fastest way to be disappointed at appraisal. Plan around the lower figures and treat anything above them as upside.
Seasoning is the other clock. The standard program guidance is about six months of ownership measured from title recording, so an investor who bought in a soft month and rehabbed a bungalow needs the calendar to cooperate before a value-add thesis can be tested by an appraiser. Anyone counting on a rapid revaluation of a recently acquired property should read the days-on-market data as a warning. Slow absorption tends to mean lenders and appraisers give little credit for projected value.
Where Does 1.00x Actually Clear in Tullahoma?
Coverage clears 1.00x on older, lower-priced stock and fails on new construction. At 75 percent LTV, a house valued near $180,000 renting for $1,200 lands around 1.1x, while a $350,000 new build at the same rent lands in the high 0.5s.
Start with the rent side. Zumper reports an average rent of $1,200, up 11 percent year over year but down 4 percent over the latest month. That looks like a small-sample listing average. Zillow Rental Manager shows houses renting between $775 and $1,775 with a $1,200 median, though that data point is older and moved only $5 year over year. Two sources, one $1,200 anchor, conflicting growth signals. The practical read: underwrite in the $1,200 to $1,400 zone unless a signed lease or a close rental comp says otherwise. City-Data’s $815 median contract rent is an all-tenure Census-based figure that includes older and subsidized units, so it understates what a renovated house commands.
Now the value side. Dividing $1,200 by the roughly $328K list-price median on Movoto gives about 0.37 percent a month. Dividing by Zillow’s $263K value gives about 0.46 percent. Those are Lendmire Research calculations that blend a list-price median and a value index with a listing-based rent average, so treat them as a band rather than a measured ratio. Either way, the rent-to-value relationship is well under the 0.5 percent territory where high-leverage cash-out files tend to struggle.
The modeled scenarios below run rent against full PITIA, meaning principal and interest at an assumed 7.03% rate plus taxes and insurance. Values and rents are modeled assumptions, not market data, and the bands are rounded down.
| Modeled property | Modeled rent | Coverage at 75 percent LTV |
|---|---|---|
| Older bungalow, $180K value | $1,200 | About 1.1x |
| Mid-market ranch, $265K value | $1,200 | High 0.7s |
| Mid-market ranch, $265K value | $1,400 | About 0.9x |
| New build, $350K value | $1,200 | High 0.5s |
The pattern is clear. Coverage improves as price falls, because taxes, insurance and debt service all scale with value while rent barely moves across the band. Run the numbers on a $265K ranch renting at $1,200: reaching 1.00x including taxes and insurance takes a loan-to-value in the mid-50s percent range, well below the 75 percent ceiling. At $1,400 rent, the breakeven loan-to-value rises to the low-to-mid 60s. That gap is the cost of buying at a price the local rent base does not support.
Sub-1.00 files are not dead. A lender may review a sub-1.00 program, a reduced loan-to-value that brings coverage back to the baseline, or a no-ratio product with more cash in the file. These paths typically come with tighter leverage, different pricing or heavier reserves, and eligibility depends on lender guidelines, credit profile and property review. The standard 1.00x benchmark is common because the rent covers the obligation at that level, and files that sit under it usually need compensating strength.
For readers new to the mechanics, the DSCR fundamentals page walks through the ratio, and a comparison of DSCR and conventional loans explains why rental-income underwriting matters for an owner who already holds multiple financed properties.
Skip the New Builds
New construction is the weakest cash-out collateral in Tullahoma. The price-to-rent gap is widest there, and the supply pipeline is the most exposed.
Homes.com’s new-construction listings for The Stillwater show three- and four-bedroom homes priced around $349,000 to $371,000. Against a $1,200 market rent, that is the high-0.5s coverage profile in the table above. A newly built rental can be a fine hold, but as a source of extractable equity it works against the investor. The appraisal reflects the builder’s price, not a seasoned value with room to grow, and the rent cannot carry a 75 percent loan.
The broader price landscape reinforces the point. Homes.com describes the city as mostly early-20th-century bungalows and mid-century ranches priced from $110,000 to $500,000, with newer homes on the north and west ends running $450,000 to $770,000. Redfin lists Bel-Aire as a popular neighborhood but offers no price or rent detail, so no coverage claim can be made there. The only defensible conclusion is that rent-to-value is best in the older, lower-priced stock and worst in the new-build ring.
Supply is the second concern. The reporting is dated, and the current status should be checked before anyone underwrites around it. If even part of it delivers, that corridor faces lease-up competition against a rent base that has shown no consistent multi-year trend. Investors holding or eyeing rentals near that corridor should stress-test rent downward.
The Tenant Base Behind the Rent
Tullahoma’s demand story is engineering and healthcare, which is a steadier base than most small Tennessee markets can claim. It supports occupancy. It does not lift rents past what the market pays.
Arnold Air Force Base hosts the Arnold Engineering Development Complex, which the Tullahoma Area Chamber of Commerce lists among its board members alongside the University of Tennessee Space Institute, Motlow State Community College and the hospital. No sourced headcount for AEDC or its contractors was available, so this analysis stays qualitative: the complex supports engineers, IT staff and security personnel through contractors, and that produces a technical, higher-income renter pool. Demand is tied to federal testing activity rather than one plant, which lowers single-employer risk compared with factory towns of similar size.
The University of Tennessee Space Institute, a graduate aerospace school created to work alongside AEDC, adds graduate students, faculty and researchers. No enrollment figure was found.
The medical anchor is Vanderbilt Tullahoma-Harton Hospital. The Chamber’s relocation page describes a 135-bed facility employing approximately 450 physicians, nurses and staff, though the page is undated and the headcount should be read as approximate. That workforce drives nurse and allied-health rental demand.
Motlow State Community College reports approximately 7,000 students, but it serves an 11-county area across multiple campuses, so only a fraction is local. The Ledford Mill Road area near the main campus draws students, staff and commuters. No price or rent data exists for that pocket, so it earns a mention as a demand node and nothing more.
Population is roughly 21,000 per NeighborhoodScout, which also puts single-family detached homes at 74.73 percent of the 8,222 housing units. HomeSnacks cites a slightly higher count, and neither figure is authoritative, so use Census QuickFacts for a final citation. The takeaway is the housing mix: this is a house-rental market, which shapes what collateral is available for a cash-out.
Houses Beat Apartments (and Small Multifamily Is Unproven)
A single-family rental is the natural DSCR asset here, and the data gives no support yet for a duplex or fourplex thesis. Investors should not assume multi-unit stock exists at attractive pricing.
Apartment rents sit below the house median. Rent.com shows one-bedroom apartments at $850 and two-bedrooms at $1,050, against $1,200 for a typical house. That premium for houses is the core of the local rental economy. It also means a duplex or fourplex would need per-unit rents near that apartment band, and stacking units only helps if the price per door is well below a single-family price.
There is a data gap here. RentCafe’s coverage focuses on buildings with 50 or more units, so it says little about small multifamily, and no sourced small-multifamily prices or rents were found. Tullahoma’s stock is overwhelmingly single-family, so small multi-unit inventory is likely thin. Verify locally before building a multi-unit plan around a cash-out.
The honest comparison is between an older single-family house and the alternative of deploying proceeds elsewhere. This is a genuine toss-up for some owners. Tullahoma appreciation has been modest, in the 2 to 5 percent range depending on the source, while rent-to-value is thin, so the equity being extracted has usually come from a low basis, a rehab or a long hold rather than from rapid market gains. An owner who bought a bungalow near the low end of the $110,000 to $500,000 band and has held it through the recent appreciation is the strongest candidate. An owner who bought new at 2 percent above list and expects a large value bump is not.
What the Proceeds Have to Do Next
Cash-out proceeds only make sense if the next deal covers itself better than the one being refinanced. In Tullahoma, that constraint matters more than the loan terms.
The program guidance frames the ceiling: up to 75 percent LTV on a cash-out (the 80 percent purchase figure does not apply), a minimum 1.00 DSCR, reserves of about six months of PITIA, and credit tiers with a 620 floor. Equity available depends on rent used for lender review, the full monthly obligation, reserves and the LTV ceiling. It is not a guaranteed figure, and all of it is subject to lender guidelines. Loan amounts run up to $3,000,000 on standard programs, though smaller balances route through select lenders in the network. Most Tullahoma balances will be small, so file structure matters.
DSCR vs. conventional financing
Two common ways to finance an investment property in Tullahoma, TN. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Lendmire’s deal desk sees a consistent pattern on files from small, thin-comp markets like this one. The common friction point is not coverage but valuation: a low appraisal shrinks the cash-out, and the rent on the appraiser’s schedule often exceeds what a lender will credit. Cleaner files tend to include a signed lease or a rental comp inside the $1,200 to $1,400 zone and a realistic value expectation built from the conservative end of local data. Reserves are the other recurring item, since a small cash-out can be partly absorbed by the six-month reserve requirement.
The proceeds question should be solved before the application. If the plan is to buy another bungalow in the older core, the same coverage math applies to the new property, and stacking two thin-coverage assets compounds the risk. Investors weighing the mechanics can review pulling equity out and the broader refi programs pages. Those planning a Tullahoma file can also look at Lendmire’s Tennessee DSCR loan programs or request a scenario quote to see how a specific value and rent combination pencils. Verify current local rental rules, taxes and insurance with qualified local professionals before committing.
Frequently Asked Questions
Can a Tullahoma bungalow support a 75 percent cash-out?
Sometimes, but the price and rent have to line up. In modeled math, a house valued near $180,000 renting for $1,200 covers around 1.1x including taxes and insurance at 75 percent LTV. A $265,000 house at the same rent does not, and would need a much lower loan-to-value. Eligibility remains subject to lender guidelines.
Why do Tullahoma price figures vary so much between sources?
Sales volume is thin, so medians swing with the mix of new construction and older homes. Redfin shows about $300K, Homes.com shows $385,000 and Zillow’s index sits at $263,387. Each uses a different sample and method. For a cash-out, plan around the lower figures because an appraiser may have few comparable sales to work with.
Does AEDC make Tullahoma rents more stable?
It supports occupancy more than rent growth. Arnold Engineering Development Complex contractors produce a technical tenant pool tied to federal testing activity rather than a single factory, which helps demand. But rent signals conflict, with an 11 percent one-year rise on Zumper against a $5 move on Zillow’s older data, so underwrite conservatively.
How long must I own a property before a cash-out?
Program guidance is about six months of ownership, measured from title recording. After that, the loan is sized against the appraised value, rent used for lender review and reserves. Owners who recently acquired a property should also expect lenders to look closely at the rent and the appraisal, given how long homes take to sell locally.
Are duplexes or fourplexes a better cash-out play in Tullahoma?
Not on current evidence. Single-family detached homes are about 75 percent of housing units, and no sourced small-multifamily pricing or rent data turned up. Apartment rents of $850 to $1,050 sit below the $1,200 house median, so a multi-unit plan needs per-door pricing well under single-family levels to work.
The Appraiser’s Read
The 1.00x line in Tullahoma clears on the older bungalows and ranches at the low end of the price band and fails on the $350,000 new builds, so the cash-out that works is the one taken on a paid-down house near $180,000, sized off the low end of the local sale prices rather than the listing sheet.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage focused on investor financing, arranging DSCR loans in 40 states plus Washington, D.C. — 41 markets total. Qualification is based on the property’s income rather than personal income documentation, subject to lender guidelines, making it a fit for LLC-held rentals and scaling portfolios. The brokerage has been recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a 2025 Scotsman Guide Top Workplace. Reach the team at 828-256-2183.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Tullahoma Housing Market
2. Redfin’s new-construction page
3. Zumper: Tullahoma Rent Research
4. City-Data’s
5. Motlow State Community College: Admissions
6. Tullahoma Area Chamber of Commerce: Move to Tullahoma
7. Homes.com: Tullahoma Local Guide
10. Movoto
11. Tullahoma Area Chamber of Commerce
12. The University of Tennessee Space Institute
14. Rent.com
15. a 2026 Scotsman Guide Top Mortgage Workplace
16. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Tullahoma Tennessee · Cash Out Refinance on Kingsport Investment Property · Cash Out Refinance on Investment Property in Oak Ridge TN
Guides: Investment Property Cash-Out Refinance in Tennessee
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.