
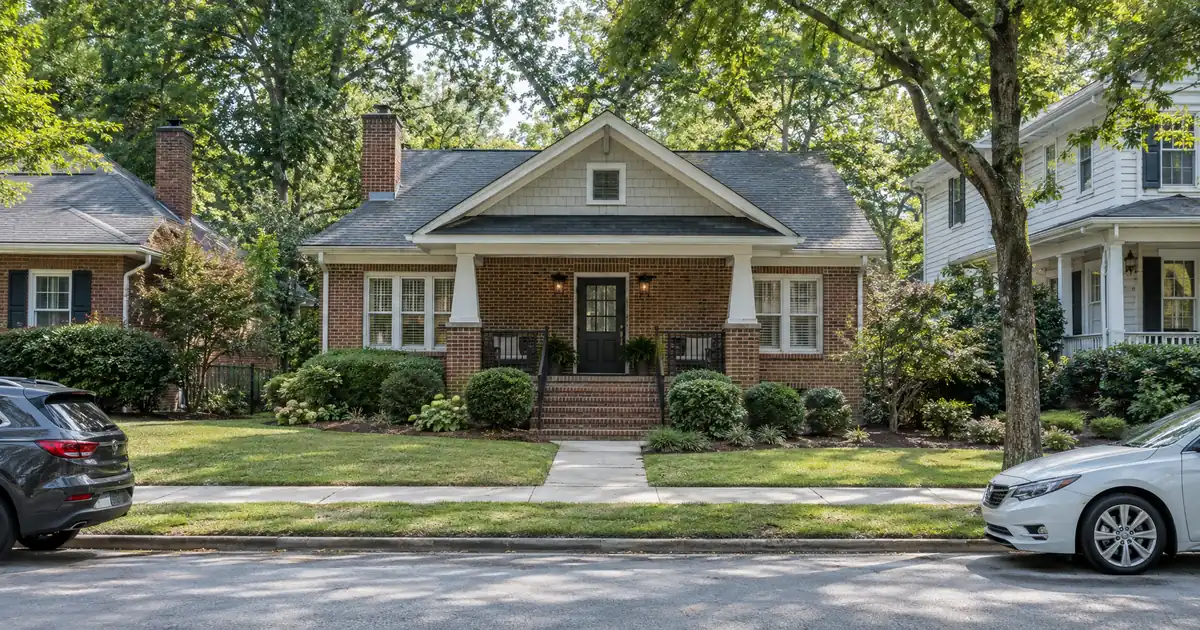
Sandy Springs’ median owner-occupied home value of $583,900 sits against a median gross rent of $1,789, per Census Bureau ACS data as compiled by CensusDepth. That works out to a monthly rent-to-value ratio near 0.31 percent. At the 75 percent loan-to-value ceiling on a cash-out, that ratio leaves full-PITIA coverage well under 1.00 on a typical home. The city’s cash-out opportunities are therefore found by price segment and rent pocket, not by citywide averages.
DSCR Cash-Out Calculator
Run the cash-out numbers in Sandy Springs, GA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A DSCR cash-out refinance on a Sandy Springs, Georgia rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds sized by the lesser of what rent supports and the 75 percent loan-to-value ceiling rather than by the owner’s personal income documentation.
- North Springs ZIP 30350 shows a 3BR rent of $2,070, the most affordable rental pocket in the city. Matthews puts Sandy Springs vacancy at 4.8 percent, against 5.86 percent metro-wide.
- Rents are flat and prices are soft, so proceeds depend on purchase discount or renovation value.
- Duplex-to-fourplex inventory is thin, and 51.53 percent of units sit in large apartment complexes.
North Springs Is Where the Coverage Math Starts to Close
North Springs, the ZIP 30350 pocket served by the North Springs MARTA station at the Red Line terminus, is the most affordable rental corner of the city. Prop-Metrics, using RentCast data, puts 2BR rent at $1,640 and 3BR at $2,070 there. Those ZIP-level figures may stretch past city limits, so treat them as directional. Tenant demand here is commuters and workforce renters riding rail to the medical district and Perimeter Center offices.
No sourced purchase-price data is available for the neighborhood. That gap matters, because coverage is a function of rent relative to value. Here is a modeled assumption, not a cited market fact. At 75 percent loan-to-value, with taxes and insurance included in the obligation, a property needs monthly rent of roughly 0.60 percent of value to reach 1.00 coverage. Using the ZIP’s $2,070 three-bedroom rent, that implies a property value around $345,000 or less. Above that, coverage slips under the baseline.
Two markers cut against the pocket. Prop-Metrics shows ZIP 30350 average rent down 3.6 percent year over year. Its listings data shows 37 percent of homes carrying price reductions and a 52-day median on market. Falling rent and price cuts cut both ways: you can buy at a discount, but you cannot assume the appraisal rises to meet you.
Pill Hill and Perimeter: The Tenant Base Is the Story
The medical and corporate district delivers the deepest demand but the hardest math. Per the City of Sandy Springs, Northside Hospital, Emory Saint Joseph’s Hospital, and Children’s Healthcare of Atlanta at Scottish Rite all sit here. Children’s Healthcare of Atlanta places Scottish Rite on Johnson Ferry Road near its two neighbors. The local Sandy Springs news site describes it as a 319-bed pediatric hospital and claims 40 percent of the Atlanta metro’s hospital beds are in the city. That 40 percent figure is a local-news claim, so read it as directional.
Corporate anchors add to the picture. The local news site’s Fortune 500 report cites UPS, Intercontinental Exchange (parent of the New York Stock Exchange), and Mercedes-Benz USA as headquartered in the city. Perimeter Center carries over 29 million square feet of office space and spans three cities. Employers like these keep a renter pool with steady paychecks, which is exactly what lenders want behind a lease.
The rent side in ZIP 30328 is strong: 2BR at $2,080 and 3BR at $2,840, per Prop-Metrics. The price side is the problem. Modeled at the same 75 percent leverage including taxes and insurance, a $2,840 three-bedroom needs a value near $470,000 to reach 1.00. Perimeter-area condos and townhomes priced around $390,000, per a local agent’s blog citing Redfin, may clear that bar. Single-family homes priced like the $583,900 citywide median do not.
Here’s the catch on the ZIP: average rent fell 2.8 percent year over year. Median days on market reached 62, and 23 percent of listings carried price reductions. Good tenant base, soft pricing. That combination rewards investors who bought below market, not those counting on a rising appraisal.
Inside the Perimeter: High Point, Glenridge Hammond, and City Springs
High Point and Glenridge Hammond sit inside I-285 and are bisected by GA-400, with mostly mid-century brick ranches and newer infill, according to a local moving company’s neighborhood guide. Single-family rentals here serve hospital and corporate workers within a short commute. No sourced price or rent data exists for these neighborhoods in the research, so no coverage number gets published for them. The property type fits. The math has to be run file by file.
City Springs, the downtown district with municipal offices, residential, retail, and a performing arts center, runs a lower price point. A local agent’s blog citing Redfin puts the downtown median sale price near $284,154, mostly attached and condo-style homes. Condos add a gate: association rental rules and lender condo-eligibility review come before any coverage ratio matters. At a sub-$300,000 value, a condo renting in the range of the city’s 2BR averages is where the modeled math lands closest to 1.00.
Skip the Chastain Park area and the Riverside river corridor for cash-out purposes. Upper-tier brick traditionals and river-adjacent homes have no rent-to-value support in the research, and the ratio at those price points almost certainly falls well short.
How the Cash-Out Math Works on a Flat-Rent Market
Sandy Springs is a price-led, stable-rent market, not a rent-growth one. RentCafe shows a citywide average of $1,660, essentially flat year over year. Apartment List shows a $1,559 median, up 0.9 percent. A local agent’s blog citing Point2Homes shows median apartment rent falling from $1,782 to $1,664 over roughly two and a half years. The sources disagree on direction, from flat to slightly up to down, so underwrite today’s in-place rent with zero growth.
The program mechanics set the rest. The cash-out ceiling is 75 percent loan-to-value, with seasoning of about six months measured from title recording. Minimum coverage is 1.00 on the standard benchmark, credit tiers run from a 620 floor up through 700, and reserves run about six months of PITIA. Loans go up to $3,000,000 on standard programs. All of this is subject to lender guidelines, credit review, and property review. For the ratio and the process in full, see the DSCR qualification mechanics and the guide “The Refi Options”.
Consider a scenario with modeled inputs, not sourced market data. An investor bought a Pill Hill-area townhome at a discount after listing reductions, renovated it, and waited out seasoning. The appraisal lands at $400,000, and the property rents at a level that produces coverage in the low-1.0 range at 75 percent leverage including taxes and insurance. That file is eligible for lender review. The same investor on a home appraised near the citywide median, renting near the ACS median, sees coverage closer to half of 1.00. Below the baseline, lenders may review lower-leverage structures, interest-only options, or sub-1.00 programs with stronger compensating factors. Those paths depend on credit, reserves, and property review, and none is assured.
Appreciation won’t bail out a thin file. Movoto reported a median list price of $650,000, down 5 percent year over year, with homes sitting a median of 52 days. A refinance after six months of seasoning may capture no market appreciation at all. Proceeds then depend on purchase discount or renovation value. Whether the extracted capital funds the next deal or just the renovation budget is a question to answer before the application, not after.
For the broader refinance menu, rate-and-term and cash-out refi details are on the Lendmire site, and Lendmire’s DSCR-versus-conventional breakdown explains why a rent-based file suits LLC-held, multi-property portfolios. Program details shift by lender, so Lendmire confirms current terms file by file at 828-256-2183.
What Does Vacancy Say About the Appraisal?
Low vacancy supports both the rent haircut and the appraisal. Matthews’ Atlanta multifamily report puts Sandy Springs at 4.8 percent vacancy, the second-tightest submarket in the metro behind Roswell/Alpharetta at 4.4 percent, against a metro average of 5.86 percent. Cushman & Wakefield’s reading for the Sandy Springs/Dunwoody submarket, cited by a local agent’s blog, shows 91.4 percent occupancy and effective rent of $1,664. That is lower than the Matthews vacancy reading implies, so underwrite vacancy at roughly 5 to 8 percent rather than a rosy figure. The same blog, summarizing Marcus & Millichap, points to a limited construction slate, which keeps new-lease concessions from competing with existing units.
Those are apartment-building numbers. RentCafe’s $1,660 average covers 50-plus-unit buildings only. Small-scale rentals sit in the same tenant pool but are not measured by these surveys.
The Small-Multifamily Scarcity Problem
Duplexes, triplexes, and fourplexes are opportunistic finds in Sandy Springs, not core inventory. Large apartment complexes make up 51.53 percent of housing units, and the city counts 96 apartment complexes of three or more units, with two under construction. Homes.com showed just two multi-family homes for sale, with asking prices from $350,000 to $2,850,000 across all building sizes.
For cash-out, scarcity has a mechanical consequence. Appraisers may reach into Brookhaven, Dunwoody, or Chamblee for comparable sales, which can cap how much value, and so how much cash-out, an appraisal supports. The city’s 2.06 persons per household, per the same agent blog, favors 1 and 2BR layouts. With 49 percent of households renting, about 25,675 of roughly 52,000, the tenant pool is deep enough to fill them.
Population counts differ by source: the ACS shows 107,198 residents and NeighborhoodScout shows 105,505. Both are the same story at different vintages. A city roughly 105,000 to 107,000 strong with a 69.9 percent bachelor’s-degree rate and $101,593 median income draws a professional renter base, which suits the long-term rental file.
What the Deal Desk Sees in Markets Like This
In high-value corporate suburbs where rent-to-price runs thin, the cleaner files tend to be the ones where the appraisal and the lease line up before submission. The common friction point is condo eligibility and appraisal comps, not credit. Files that arrive with a signed lease at market rent, a reserve account already seasoned, and an appraisal-ready renovation scope tend to move through lender review with fewer open questions. Investors in markets like this often gain more from trimming leverage on a borderline file than from chasing a higher loan amount.
The Question Behind the Numbers
Sandy Springs pairs a hospital district and a corporate-headquarters base with flat rents, soft prices, and a housing stock dominated by large complexes. That rewards the investor who bought below market and refinances for what the lease supports. It punishes the one who expected the appraisal to do the work. Before a cash-out application goes in, is your property’s rent closer to 0.60 percent of its appraised value, or closer to 0.31 percent?
Frequently Asked Questions
How do you qualify for a DSCR loan in Sandy Springs?
Qualification centers on the property’s rent relative to its full monthly obligation, including taxes and insurance, with 1.00 as the common baseline. Lenders also review credit (tiers run from a 620 floor up through 700), reserves of about six months PITIA, and the property itself. Sandy Springs’ median rent-to-value ratio sits near 0.31 percent, so lower-priced condos, townhomes, and the ZIP 30350 pocket tend to show the strongest coverage. Final eligibility depends on lender guidelines, credit approval, and property review.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Sandy Springs, GA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property cash-out refinance in Sandy Springs, Georgia?
Expect a 75 percent loan-to-value ceiling, about six months of ownership from title recording, and minimum coverage of 1.00 on the standard benchmark. Reserves run about six months of PITIA, rising to about nine months above $1,500,000. Loan amounts go up to $3,000,000 on standard programs. Manufactured homes, log homes, and barndominiums fall outside these programs. Available equity depends on rent, PITIA, reserves, and the leverage ceiling, so no cash figure is guaranteed.
Will Sandy Springs’ flat rents limit how much cash I can pull out?
Usually yes, because the proceeds track what the rent supports, not what you hope the market does. Rents here are essentially flat across RentCafe and Apartment List readings, and list prices are soft. A property bought at a discount or renovated to a higher value can still produce a workable refinance. One relying on appreciation alone may not.
Why do appraisals matter more on a Sandy Springs duplex than on a condo?
Small multifamily is scarce, with only two multi-family homes listed on Homes.com in the snapshot. Appraisers may pull comparable sales from neighboring cities, and that can hold down the supported value. Condos have more comps but carry association rental rules and lender condo-eligibility review.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage built around DSCR investor lending, with programs available in 41 markets, including Washington, D.C. DSCR lenders commonly evaluate rental-income coverage instead of personal income paperwork, a practical fit for LLC-owned and multi-property investors, subject to lender program eligibility. Terms vary by lender, property, leverage, and program. Lendmire is a 2025 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2026, per the Top Workplace press announcement.
For broader investor-financing rules and property-type coverage across the state, see Georgia DSCR loans.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. ZIP 30350
2. Matthews, Atlanta multifamily report
3. NeighborhoodScout — Sandy Springs Real Estate
4. City of Sandy Springs, Hospitals
5. Children’s Healthcare of Atlanta, Scottish Rite
6. Sandy Springs local news, Hospitals
7. Sandy Springs local news, Fortune 500 headquarters
10. lioomoving.com — Best Neighborhoods in Sandy Springs GA
12. Apartment List
13. Movoto
14. dawnandersonrealestate.com — Investing in Small Multifamily Properties in Sandy Springs
15. City of Sandy Springs, Multifamily Rental Housing
16. Homes.com
17. a 2025 Scotsman Guide Top Mortgage Workplace
18. Scotsman Guide — Top Workplaces 2026
19. the Top Workplace press announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance on Sandy Springs Investment Property · Cash Out Refinance Investment Property in Dunwoody, Georgia: Can Your Rent Cover the New Loan? · Cash Out Refinance Investment Property in Holly Springs, North Carolina: How the Rent Math Clears at 75% LTV
Guides: Investment Property Cash-Out Refinance in Sandy Springs, GA · Investment Property Cash-Out Refinance in Georgia
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.