
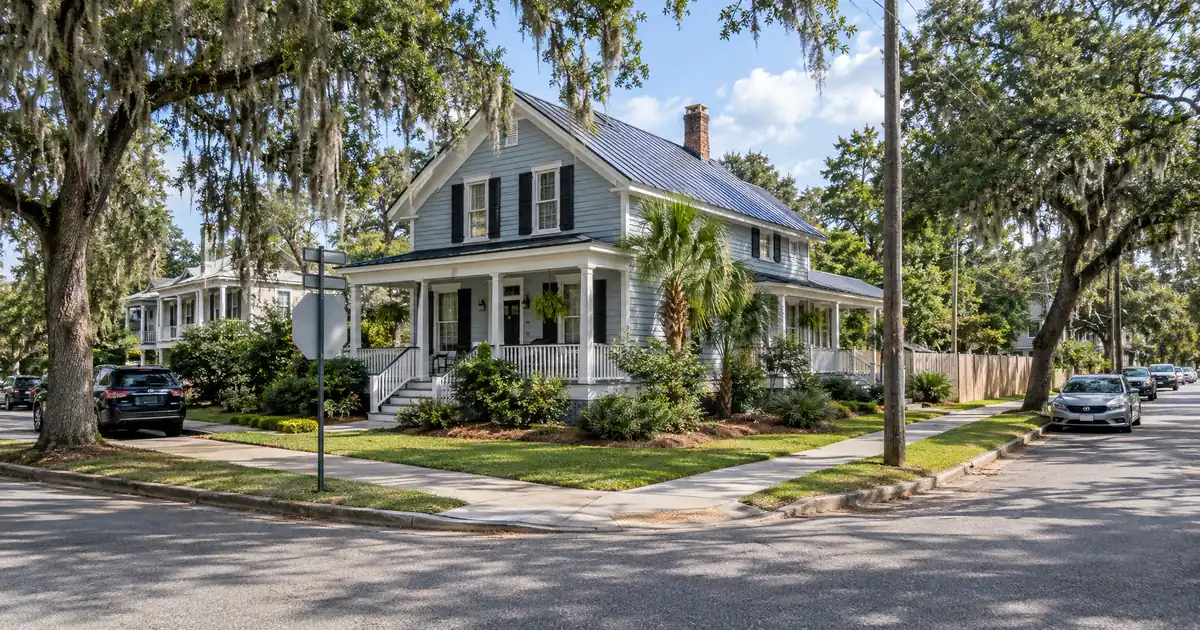
Picture an investor holding a three-bedroom house bought at $225,000 in the St. Andrews corridor, rented out for well over six months, and now sitting next to a second deal that needs a down payment. The question isn’t whether equity exists. It’s how much of it an appraiser will recognize, and whether the rent can carry a bigger loan balance at a 75 percent ceiling. Irmo makes that question harder than most Midlands suburbs, and more interesting.
TL;DR: A cash-out refinance in Irmo, South Carolina suits owners of seasoned single-family rentals whose rent still covers full monthly obligations after a larger loan, because the file is underwritten primarily on the property’s rental income measured against its full monthly obligation.
DSCR Cash-Out Calculator
Run the cash-out numbers in Irmo, SC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Hubrec’s CMLS-based report puts the median sale price at $237,500, with days on market rising from 51 to 67.
- Single-family detached homes are about 90 percent of Irmo’s housing, so the rent comp is a single-unit comp.
- Cash-out caps at 75 percent LTV, with about six months of seasoning from title recording.
- Modeled coverage holds comfortably below roughly $255,000 in value and thins fast above it.
Irmo Market Snapshot
A quick read on the Irmo investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $237,500 median (Hubrec / CMLS market report) |
| Typical rents | ~$1,900 (REI Lense LTR) |
| University enrollment | 17,053 students (Niche, District 5) |
| Employment | Scout motors 4,000 jobs (The Kirkland Company, Columbia) |
| Vacancy | 8.4% rental (Wikipedia, Irmo) |
Start With Appreciation You Can Actually Prove
Irmo’s price trend depends on which source you read, so the equity story has to rest on documented basis, not market drift. Per Hubrec’s market report built on CMLS data, the median sale price is $237,500, down 1 percent, with inventory up 27 percent and sellers getting about 98.1 percent of asking. Days on market climbed from 51 to 67.
Other portals disagree. Zillow’s home value index shows $286,812, up 1.3 percent. Redfin’s housing market page shows a $250,000 median, up 6.4 percent, while an agent blog citing Redfin reports a 7.7 percent decline. Same town, four stories.
The working read: flat to softening. An investor who bought a couple of years ago shouldn’t assume the appraisal lands above the purchase price. The cleaner cash-out cases are the ones with documented renovation value layered onto basis: a kitchen, a roof, a finished bonus room. Appreciation is a bonus here, not the plan.
What the Coverage Math Looks Like at 75 Percent
At 75 percent LTV, most Irmo single-family rentals in the lower price bands clear the 1.00 benchmark with room to spare, but the cushion shrinks quickly as value climbs. Most standard DSCR programs are built around a 1.00 baseline because rent covers the full payment at that level. Some lenders review lower ratios with compensating factors, and exact eligibility depends on lender guidelines, credit, reserves, and property review.
Rent itself is a range, not a number. Homes.com shows a median of $1,899 for single-family. Zumper averages $2,022, up 1 percent year over year. RentCafe averages $1,668, down 3.53 percent, though it only covers buildings with 50 or more units. Niche’s median is $1,477, likely on older survey data.
Run the numbers on the modeled cases below. These are illustrative assumptions, not sourced market facts: a 30-year amortization at 75 percent LTV, with taxes and insurance built in at South Carolina average loads.
| Modeled value | Assumed rent | Modeled coverage |
|---|---|---|
| $225,000 | $1,900 | Roughly 1.35 |
| $255,000 | $1,900 | Roughly 1.25 |
| $225,000 | $1,668 | Roughly 1.25 |
| $286,812 | $1,900 | Around 1.10 |
Every band includes taxes and insurance, and each is rounded down. The pattern is plain: coverage depends more on where the value sits than on which rent source you trust. A $1,900 rent on a $225,000 house is about 0.84 percent rent-to-price. REI Lense’s modeled data shows roughly the same ratio and a median monthly cash flow of negative $170 across ten-plus Irmo properties. That figure likely layers in operating costs a coverage ratio ignores, so the two aren’t contradictory. They do mean a passing ratio is not the same as fat cash flow.
Where the Numbers Hold: Four Irmo Pockets
The strongest cash-out candidates sit in the lower-priced band. Resideline tracked 172 closings over twelve months, with a $225,000 median and the middle half closing between $173,000 and $254,500. Ninety-nine percent were single-family. That middle band is where the coverage table looks healthiest.
Downtown Irmo and the St. Andrews Road corridor. Older stock and the most concentrated rental inventory in town. BestNeighborhood flags St. Andrews for less expensive homes, and its citywide median home price is $212,045. No reliable neighborhood-level rent figure exists, so treat it as a cash-flow-led pocket you underwrite yourself. Homes.com also lists Saint Andrews and Seven Oaks as popular rental areas.
Seven Oaks. Long-established, with the town’s first Okra Strut held at Seven Oaks Park. No clean price or rent data. Comps here are the ones an appraiser can most likely pull from within the neighborhood itself.
Ballentine and West Lake. Rentometer describes the area as running from quiet cul-de-sacs to community parks. Its rent bands put three-bedroom rents in the $1,800s and four-bedroom-plus near $2,000. Good tenant-fit property, thin on published numbers.
Lake Murray-adjacent homes. The appreciation-led end. A local agent blog (directional only) puts lake-area homes at $206 to $213 per square foot, against $158 to $172 in a mid-range corridor like Broad River. Rent doesn’t rise in step with price. That leaves the modeled coverage near the bottom of the table, and a lake-area owner may need to borrow below the 75 percent ceiling to keep the ratio comfortable.
Honestly, this is a toss-up for investors with a choice: lake homes offer the bigger equity cushion, while sub-$255,000 houses make the cleaner refinance. An investor after proceeds for a second purchase should probably lean toward the latter.
Single-Family Is the Product
Irmo is a single-family market, full stop. NeighborhoodScout’s housing mix shows 89.91 percent single-family detached, 4.48 percent attached, 2.78 percent large complexes, and only 1.76 percent duplexes and small multifamily. Its basis is partly older data, but the direction is clear. RentCafe counts 852 renter-occupied households (18 percent) against 3,780 owner-occupied (82 percent).
Two practical effects follow. Duplex and fourplex comps are scarce, so income-stacking deals rarely exist. Underwrite every file on single-unit rent and don’t assume multi-unit coverage. And limited rental supply works in an existing landlord’s favor, though large-complex rents are flat to soft at RentCafe, which means newer apartments still compete for the same tenants. Budget for rents that hold, not grow.
Small note on ineligible stock: manufactured homes, log homes, and barndominiums fall outside these DSCR programs, which matters in unincorporated pockets of the Dutch Fork.
Which County Is Your House In?
Irmo straddles Lexington and Richland counties, and plenty of “Irmo” addresses aren’t inside the town at all. Lexington-Richland School District Five covers roughly 196 square miles across both counties, and many properties carry an Irmo postal address while sitting in unincorporated Richland or Lexington County. Landmarks that feel central to town can be outside its limits.
Why it matters for a refinance: the jurisdiction determines which records, comps, and local offices apply to the property. Confirm it before you order anything. Also verify current local rental rules, taxes, and insurance with qualified local professionals. That’s the only regulatory reminder this article carries, and it’s enough.
Who Fills the House
Irmo’s tenant base is Columbia commuters. The town itself counted 11,569 residents in the most recent decennial Census, with Data Commons showing 12,204 more recently. The rental pool is a fraction of that, but the jobs are regional. Per COLAtoday, Blue Cross Blue Shield of South Carolina employs over 10,000 and is the region’s top private employer, while Prisma Health Midlands and Lexington Medical Center together employ over 21,000. Walmart employs almost 6,000 and Amazon over 2,600.
The state government remains the area’s largest employer, according to a published report, which also puts University of South Carolina enrollment above 36,000. It cites Scout Motors’ planned Blythewood plant at 4,000 jobs, but that report is dated, so verify the plant’s current status before leaning on it. Long-term lease demand here rides on government, healthcare, and retail, not on any single employer.
Working DSCR brokers see a recurring pattern in suburban single-family markets like this one. Files underwritten on a conservative rent comp, not the highest portal number, tend to hold together through appraisal and lender review, while files that assumed rent growth or quoted one bullish listing site often lose ground. Comps in thin markets like this one also commonly stretch across neighboring areas. Strong files arrive with a lease, a rent survey, and a realistic value in hand.
What Seasoning Does to Your Comps
Expect comp depth to be the quiet risk. With 172 closings a year across a wide price spread, an appraiser may reach into Ballentine, St. Andrews, and even Columbia-area sales for support. That adds valuation risk on a cash-out. A sub-$255,000 target band gives the best chance of clean comps, which is where the sourced data concentrates.
Program basics for this file type, all subject to lender guidelines and varying by borrower, property, and loan scenario:
- Cash-out caps at 75 percent LTV, lower than the purchase ceiling.
- Seasoning is about six months from title recording.
- Reserves typically run about six months of PITIA.
- Credit tiers start at a 620 floor, with better terms generally available at higher scores.
- Minimum DSCR is 1.00, rent used for lender review against PITIA.
Whatever proceeds come out depend on rent used for lender review, reserves, and the 75 percent cap, not on a guaranteed number. For the broader mechanics, see Lendmire’s DSCR walkthrough and the guide “Where DSCR and Conventional Diverge”. Investors weighing rate-and-term against cash-out can compare the refi options. LLC-titled properties are welcome subject to lender program eligibility.
Then comes the real question: what do proceeds buy? In Irmo the answer is often another single-family rental in the same sub-$255,000 band, which keeps the next file’s coverage in a similar range. Lendmire’s South Carolina DSCR platform covers the wider state picture. Investors ready to price a specific file can talk to Lendmire or call 828-256-2183.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Irmo?
The file is underwritten primarily on whether the property’s rent covers its full monthly obligation (principal, interest, taxes, insurance, and any HOA dues), with 1.00 as the common baseline. Beyond that, expect program review of ownership seasoning of about six months, a credit floor of 620, reserves of about six months PITIA, and a value supported by comps. Final eligibility depends on lender guidelines and property review.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Irmo, SC, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Irmo, South Carolina?
Most files need a rent figure used for eligibility review, a credit score in the program tiers (620 to 700), and reserves, with leverage capped at 75 percent on cash-out. The property must be an eligible type; manufactured homes, log homes, and barndominiums are not. Because nearly 90 percent of Irmo housing is single-family, the rent comp is usually a single-unit comp. Terms vary by borrower and scenario.
Does it matter whether my Irmo house is in Richland or Lexington County?
Yes. The town spans both counties, and many Irmo-addressed homes sit in unincorporated areas outside town limits. Confirm the property’s actual jurisdiction and county before you order an appraisal, since that determines which records and comps apply.
What if the appraisal comes in flat?
Flat values are plausible in a market where median price moved down 1 percent and days on market stretched from 51 to 67. The fix is structural: underwrite on purchase price plus documented improvements, and borrow below the ceiling if coverage gets tight.
Closing Thought
Irmo rewards owners who buy in the middle band, document their improvements, and keep leverage honest. With rents flat and prices soft, the next move depends on the house you already own. Does its rent still cover a bigger loan at 75 percent, or is it time to run the numbers on one of the cheaper neighbors?
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker working with real estate investors across 41 markets, including Washington, D.C., through DSCR investor loan programs. Lenders generally review qualification around the property’s rental income rather than the borrower’s W-2 history, which fits LLC-titled portfolios and self-employed investors. Every scenario stays subject to financing review and program guidelines. The firm is a 2025 Scotsman Guide Top Workplace and a top-ranked workplace in 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Hubrec / CMLS market report
4. The Kirkland Company, Columbia
7. Redfin’s housing market page
8. Homes.com
9. Zumper, Irmo
10. RentCafe, Irmo
11. Resideline, Irmo housing market
12. BestNeighborhood
14. Lexington-Richland School District Five
15. U.S. Census Bureau QuickFacts, Irmo town
17. COLAtoday, Columbia top employers
18. a 2025 Scotsman Guide Top Workplace
19. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Irmo, South Carolina: Equity Math for Single-Family Rentals · Cash Out Refinance Investment Property in Columbia SC · Cash Out Refinance Investment Property in Newberry, South Carolina: Plant-Town Equity on Thin Comps
Guides: Investment Property Cash-Out Refinance in South Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.