
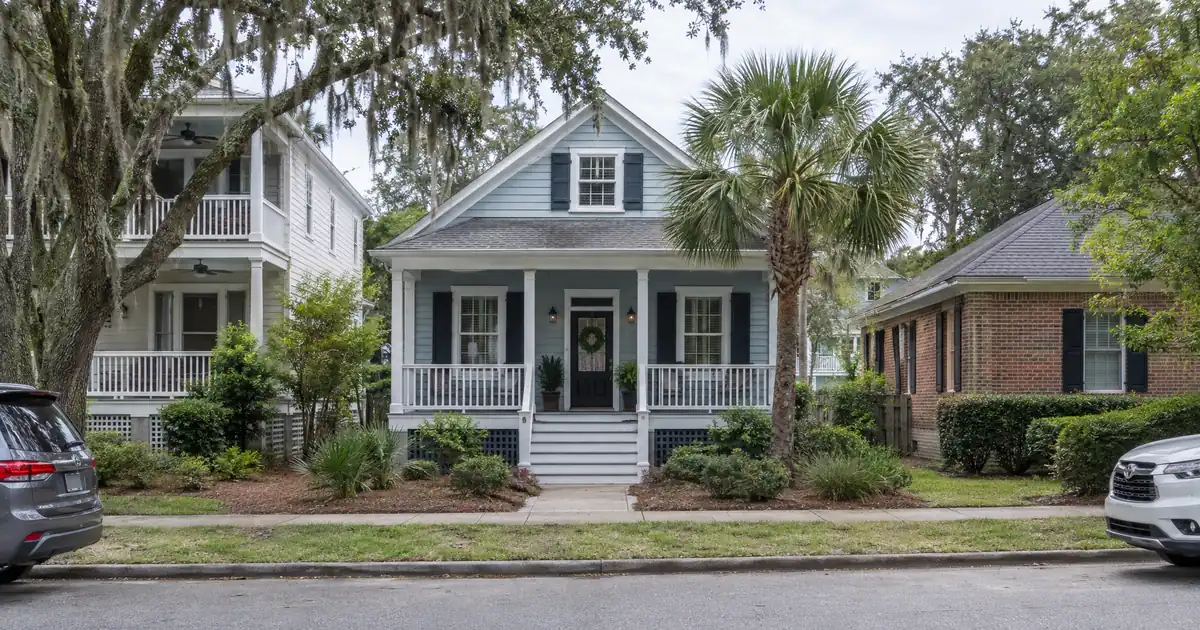
If you own a rental on the Waccamaw Neck and the appraisal came back in seven figures, here’s what most brokers won’t say: the value on paper is not the number that decides your cash-out. Rent is. And the rent people quote for Pawleys Island is mostly fiction.
TL;DR: A cash-out refinance on a Pawleys Island, South Carolina rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the gap between vacation-style rents and year-round lease rents decides how much equity the file can support. Per Zillow Rental Manager, average rent is $2,200.
DSCR Cash-Out Calculator
Run the cash-out numbers in Pawleys Island, SC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out is typically capped at 75% LTV, with about 6 months of seasoning.
- A 3BR at $2,600 rent only just covers a modest purchase price and falls short on a $565,000 one.
- Georgetown County rental vacancy is 0%.
- Comps are thin and luxury-skewed, so appraisals can surprise in either direction.
Pawleys Island Market Snapshot
A quick read on the Pawleys Island investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $999,081 median home price (NeighborhoodScout – Pawleys) |
| Typical rents | $2,678 avg (NeighborhoodScout – DeBordieu) |
| Recent appreciation | +169.6% yoy (Redfin – Pawleys Island Housing) |
| University enrollment | 11,881 students (Wikipedia – Coastal Carolina) |
| Population | 170 population (Census Reporter (ACS 5-Year)) |
| Employment | 2,500+ employees (Glassdoor – Tidelands Health) |
Two Markets Wearing One Name
The town of Pawleys Island is tiny. Census Reporter puts the incorporated town at 170 residents. The real market is the Waccamaw Neck, the narrow peninsula between the Atlantic and the Waccamaw River that shares zip code 29585 with Litchfield Beach. The rental catchment is Georgetown County, home to roughly 65,000 people per the Waccamaw Regional Council of Governments.
That mismatch creates the central data problem. NeighborhoodScout reports a town-proper median home value of $999,081. Redfin shows a median sale price near $2.0M over three months, with homes taking 75 days to sell, but that sample is small and luxury-weighted. Movoto shows a median sale price of $565,000 across 338 monthly sales, which better reflects attainable inventory. This article uses $565,000 as the working median and treats the other two as estate-pricing outliers.
Lendmire (NMLS# 2371349) is a non-QM mortgage broker. Lendmire structures DSCR scenarios for investors targeting Pawleys Island, South Carolina and places them with wholesale lenders across 41 markets, including D.C. Its work on cash-out files starts with the rent, not the appraisal.
Which Rent Do You Actually Underwrite?
Underwrite the unfurnished, 12-month lease rent. Anything else overstates coverage.
Homes.com listings show a median rent of $3,859 for the area, but furnished vacation listings dominate that figure, per Homes.com. Zillow’s landlord-facing data is more useful: $2,200 average across property types, $1,700 for two-bedrooms, and $2,600 for three-bedrooms. County-wide, the median rental rate was $1,531 as of the last full-year reading, per RentalSource.
An investor modeling off the $3,859 headline will overstate achievable income by well over a third. The lender won’t make that mistake. Lease-based rent is what the appraiser’s rent schedule and the DSCR calculation tend to rely on.
The Coverage Math at Two Price Points
Run the numbers on two modeled assumptions. These are illustrations, not market data.
Modeled case one. A three-bedroom appraised at $425,000, renting at $2,600, refinanced at 75% LTV. Including taxes and insurance at South Carolina average loads, coverage lands around 1.05x. That clears the standard 1.00x benchmark, but only just. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Modeled case two. The same rent on a $565,000 property at 75% LTV. Coverage falls into the high-0.7s, including taxes and insurance. Not close. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Rent divided by full monthly obligation. That’s the whole formula, and it punishes price without rent to match. A 1.00x baseline is common because the rent covers the payment at that level. Some lenders review lower-ratio files, but those typically need lower leverage, more cash in reserve, or different pricing, and eligibility ultimately depends on lender guidelines, credit, and property review. For a sub-1.00 file, the paths a lender might review include a sub-1.00 program, an interest-only structure, or a lower LTV that trims the loan balance. None of these is a promise. See the guide “What Is a DSCR Loan” for how the ratio works.
In this market, the sub-$450,000 band is where cash-out files tend to work. Above it, leverage usually has to come down.
Neighborhoods That Fit a Cash-Out (and Ones That Don’t)
Three submarkets matter here. One fits poorly.
Traditions and Willbrook Plantation. These golf-community single-family residential areas are the mid-tier, less resort-priced option on the Neck. Price-to-rent ratios are friendlier to a standard 12-month lease, which is the profile a rent-based refinance wants. They are the likeliest fit for a 3BR at that $2,600 figure.
Waverly Mills. Inland and workforce-adjacent, it sits closest to where tenant demand is deepest. Per NeighborhoodScout’s zip-code listing it’s the attainable end of 29585. Comps here are the ones an appraiser can actually defend.
DeBordieu Colony and Pawleys Plantation. Skip this one for cash-out math. The median value is $927,387 and average rent is $2,678, per NeighborhoodScout. That is a rent-to-value ratio too thin for a 75% LTV file. The vacancy rate is 40.7%, with 38.9% of housing seasonally occupied. It’s a second-home market, not a lease market. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
The historic island core and Litchfield Beach follow the same logic: seasonal-heavy, with little long-term stock. Long-term-rent files belong inland.
Why the Tenant Pool Holds Up
Georgetown County’s rental vacancy is 0%, per Affordable Housing Online. Whatever you make of a single aggregator’s figure, the direction matches local reporting. A county housing study found few market-rate apartments under $1,000 in the Waccamaw Neck, per the Coastal Observer, and a later analysis found no homes or apartments in Georgetown County at the roughly $589 monthly rent that tourism-sector workers can afford, per the Coastal Observer.
Employment anchors are healthcare and hospitality. Health Care and Social Assistance is the county’s largest sector at 4,605 employees. Tidelands Health runs four hospitals and more than 70 outpatient locations, with a newly built 125-bed hospital in Murrells Inlet minutes away.
The counterweight is real. International Paper closed its Georgetown mill by the end of 2024, eliminating 674 jobs, per Packaging Dive. It had been the county’s largest employer, per the SC Daily Gazette. Those were higher-paying jobs. The county has been shifting from manufacturing toward a healthcare and tourism labor base, which favors rents in the $1,500 to $2,600 band over premium ones.
The Property Type Question
Working DSCR brokers see a recurring pattern in thin coastal resort markets: appraisers reach past the immediate submarket for comparables, and the file’s value comes back lower than the owner’s assumption, not higher. Owners who plan a cash-out on projected equity, rather than on comps that survive appraisal review, tend to be the ones who restructure the loan amount downward late in the process.
Small-scale product dominates the region’s rental stock. In nearby Georgetown, 76% of apartments sit in complexes under 50 units and 20% are single-family rentals, per RentCafe. Duplex and fourplex inventory specific to Pawleys Island wasn’t found in the research, so nothing here should be read as a multi-unit thesis. Single-family is the workable asset.
Appreciation Is Up. Comps Are Thin.
That Redfin median shows appreciation of 169.6% year-over-year. Ignore it. A small sample of estate sales moved the median, and it says nothing about your cottage in Waverly Mills.
The more useful tension: Redfin scores the market 25 out of 100 for competitiveness, meaning it isn’t very competitive. Murrells Inlet, by contrast, has deeper listing inventory and a $449,000 median list price, per Movoto. Deeper comps make appraisals more predictable. Pawleys Island’s thin sales record makes them less so.
Practical read: don’t assume aggressive equity extraction on a fast renovation cycle. The seasoning clock is about 6 months from title recording, and a conservative appraiser can still land under your target. The stronger play might be a lower-LTV refinance on a property with solid lease history over a maxed-out one on projected value. That’s a genuine toss-up for investors chasing growth, since leaving equity in the property has a cost of its own.
What the Proceeds Do Next
Cash-out is a funding source, not the goal. Equity available depends on rent used for lender review, full monthly obligation, reserves, and the 75% LTV ceiling. It is not a guaranteed figure. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Typical program guidance runs like this, subject to lender guidelines: minimum DSCR of 1.00, credit tiers from a 620 floor up through 660, 680, and 700, and reserves around six months of PITIA (about nine above $1,500,000). Standard programs run up to $3,000,000, with smaller balances routed through select lenders in the network. The cash-out refinance walkthrough covers the mechanics, and Lendmire’s guide to the refinance pathway for investor properties lays out how it differs from a rate-and-term move. An LLC can hold title, depending on program guidelines. For the trade-offs against a bank loan, see the side-by-side comparison.
Then there’s the next purchase. In a county with 0% reported vacancy and a documented shortage of workforce-priced rentals, proceeds tend to do better in inland long-term product than in the oceanfront colonies. Investors can review South Carolina DSCR investor loans or request a quote at 828-256-2183.
Before You Pull Anything Out
Pull your own comps. Specifically, find sold, unfurnished long-term rentals in 29585 and adjacent Murrells Inlet, and match them to your property’s bedroom count. That single exercise tells you whether your refinance should be run on the Pawleys Island number or the Murrells Inlet number, which is the difference between a file that works and one that needs a lower loan amount. Confirm current local rules, taxes, and insurance with qualified local professionals.
Frequently Asked Questions
How do you qualify for a DSCR loan in Pawleys Island?
Qualification centers on the property’s rent relative to its full monthly obligation, typically with a 1.00 minimum ratio, a credit score of 620 or higher, and about six months of reserves. Personal income documentation is generally not the focus, subject to lender guidelines and property review. In Pawleys Island the key input is a documented 12-month lease rent, not vacation-style listing rates.
DSCR vs. conventional financing
Two common ways to finance an investment property in Pawleys Island, SC. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Pawleys Island, South Carolina?
For a cash-out refinance: about six months of ownership from title recording, LTV up to 75%, and reserves that scale with the loan amount. Eligible property types generally exclude manufactured homes, log homes, and barndominiums. Final eligibility depends on the lender, the borrower’s credit profile, and the appraisal.
Why do Pawleys Island appraisals come in unpredictably?
The sales sample is small and luxury-skewed. Redfin’s median and Movoto’s median differ by a wide margin, and one large estate sale moves the average. Appraisers often widen the comp search to nearby markets like Murrells Inlet, which can pull value down for inland properties.
Does the International Paper closure affect rental demand?
It changes the mix more than the volume. Roughly 674 jobs were lost in Georgetown, but healthcare and hospitality remain the county’s largest employment sectors, and county vacancy remains at 0%. Tenants earning mid-range wages tend to rent in the $1,500 to $2,600 band.
What DSCR terms may lenders review for investors in South Carolina?
Lendmire arranges DSCR investor loans. A typical cash-out file is reviewed against a 75% LTV ceiling and a 1.00 minimum ratio, subject to lender guidelines and credit approval.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR loans are evaluated by the lender on rental income rather than personal income, subject to lender guidelines. That makes them a fit for LLC-owned portfolios, self-employed investors, and operators scaling beyond conventional loan caps. Recognized as a Scotsman Guide Top Mortgage Workplace: a top-ranked workplace in 2025 and a 2026 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
4. Redfin
5. Wikipedia – Coastal Carolina
6. Census Reporter (ACS 5-Year)
7. Glassdoor – Tidelands Health
8. Waccamaw Regional Council of Governments
9. Movoto
10. Homes.com
11. RentalSource
13. Coastal Observer
14. Coastal Observer
15. Tidelands Health
16. Packaging Dive
17. SC Daily Gazette
18. RentCafe
19. Movoto
20. Scotsman Guide — Top Workplaces 2025
21. a 2026 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Pawleys Island, South Carolina: Equity Beyond the Luxury Comps · DSCR Loans Pawleys Island & Georgetown · DSCR Loans Myrtle Beach: Investor Financing for North Myrtle Beach, Surfside, Pawleys Island, Conway & Real Estate Investors
Guides: Investment Property Cash-Out Refinance in South Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.