
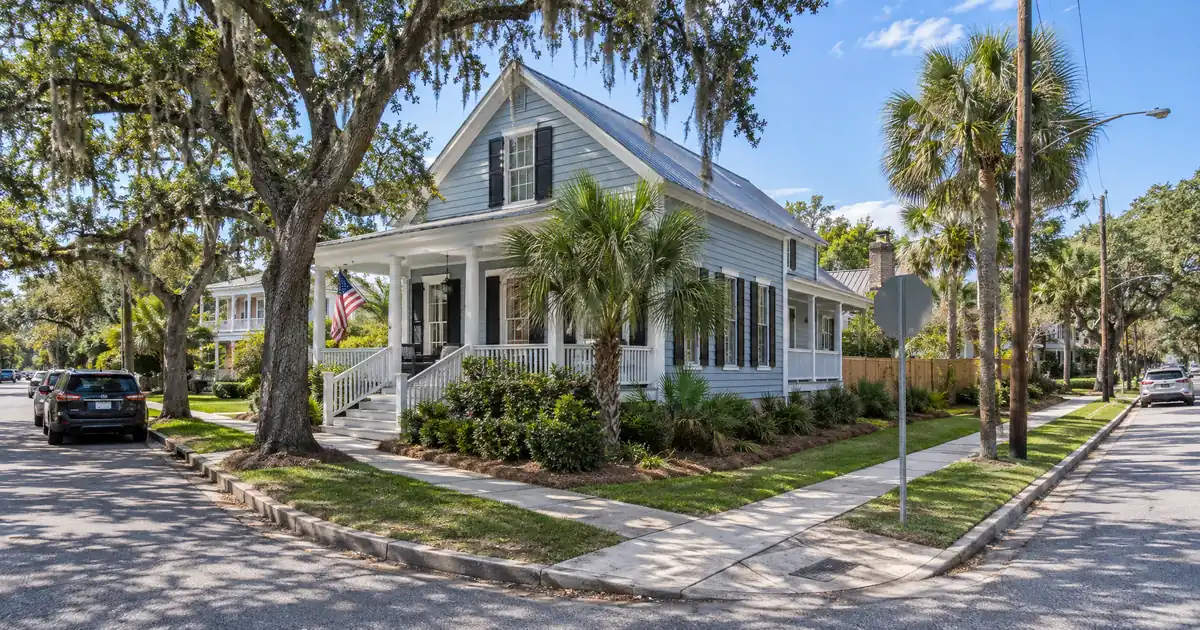
Take a $449,900 median sale price (Movoto) and set it against a three-bedroom rent near $1,994 (Apartments.com). Cap the cash-out at 75 percent LTV and count taxes and insurance in the payment. A single-family file lands well under the 1.00x benchmark. That is the mechanical reality of pulling equity out of a Murrells Inlet rental, and it shapes everything below.
Murrells Inlet, South Carolina is one of the 41 markets (40 states plus Washington, D.C.) where Lendmire places DSCR loans for investment-property borrowers. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. This piece is about owners who already hold property here and want that equity working elsewhere.
DSCR Cash-Out Calculator
Run the cash-out numbers in Murrells Inlet, SC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version: A DSCR cash-out refinance in Murrells Inlet, South Carolina is underwritten primarily on the property’s rental income measured against its full monthly obligation, with a lender ordering an appraisal, checking about six months of seasoning, and sizing proceeds under a 75 percent LTV ceiling.
- Single-family rents sit low against price, so coverage often starts below 1.00x.
- Duplexes are scarce but produce the strongest coverage math in town.
- Portal price medians conflict badly, so the appraisal decides your proceeds.
- Tidelands Health anchors year-round tenant demand near the Highway 17 Bypass.
The Highway 17 Bypass Medical Corridor Carries the Tenant Base
The strongest long-term rental demand in Murrells Inlet runs along the Highway 17 Bypass, where Tidelands Waccamaw Community Hospital sits. Tidelands Health operates four hospitals and more than 70 outpatient locations. The City of Georgetown names it the county’s largest employer.
That matters for a cash-out because the lender wants durable, year-round rent. Clinicians, technicians and support staff sign 12-month leases whether or not the beaches are full. The Georgetown County community update lists a lack of workforce housing as a county-level challenge. That supports rents holding up for well-located, modestly priced stock.
There is no neighborhood-level rent data here, so treat the corridor as a tenant thesis, not a coverage promise. Rents across sources are flat to slightly down. Apartments.com shows about a 2.2 percent decline over the prior year. Don’t underwrite rent growth to justify a bigger cash-out.
Marsh Walk and the Inlet Core: Great Address, Thin Coverage
The creek-front restaurant district is, in PawleysIsland.com’s words, the heart and soul of the Inlet. The Marsh Walk is a half-mile boardwalk over salt marsh. It is a wonderful place to own and a hard place to make rent cover the payment.
Properties near the core carry a premium for the address, not for the rent. The likely long-term tenant is restaurant and hospitality workers. That is inference, not sourced, but it caps rent at workforce levels while the basis climbs. NeighborhoodScout puts the town’s median house value at $586,744 and calls it one of the most expensive places in the state. Treat that figure with caution, since it is an aggregator estimate.
An owner here is sitting on appreciation. Coverage is not the story. A DSCR cash-out on this stock is an equity play, and the file needs to be structured that way.
Where Duplexes Change the Math
Duplexes and small multiples are the best-fitting product for DSCR cash-out in this town, and there are barely any. PawleysIsland.com describes the nearby Garden City area as mostly single-family homes, duplexes and the occasional small condo building. NeighborhoodScout puts single-family detached at 57.02 percent of housing units and attached row houses at only 6.52 percent. Comps for two-to-four unit properties will be thin.
Run the numbers on both structures. These are modeled assumptions, not sourced market facts, and coverage includes taxes and insurance at 75 percent leverage:
- Single-family at $449,900 with a $1,994 rent: coverage comes out around 0.75x. Not close.
- Duplex near $440,000 with a one-bedroom at $1,460 and a two-bedroom at $1,851: coverage lands around 1.25x, rounded down.
The duplex price comes from a dated Homes.com multifamily snapshot that showed a $440,000 median and just two listings. Treat it as a directional guide only. Two rent streams against one basis is the only realistic way to clear 1.00x here without a huge equity cushion.
A single-family owner below 1.00x is not necessarily shut out. Lenders may review a sub-1.00 program, an interest-only structure or a lower LTV. Each of those trades away leverage, pricing or cash-out size, and eligibility depends on lender guidelines, credit and property review. The guide “What Is a DSCR Loan” is worth a read before you pick a route.
DSCR files in markets like this one typically look like a strong-equity, thin-coverage borrower. The rent supports a modest payment, the appraisal supports the value, and the structure has to bridge the gap. The files that go smoothly come in with a clean rent schedule, a written lease and reserves already seasoned in the account. The ones that stall usually have equity but a coverage number that only works at the maximum leverage the borrower hoped for.
Why Portal Medians Won’t Save Your Appraisal
Murrells Inlet price data is a mess, and the appraisal is the only number that counts. Redfin shows a $495K median, up 7.0 percent year over year, with homes selling in 90 days. Houzeo shows $334,500, down 22.49 percent, with 8.2 months of inventory and 77.33 percent of listings carrying price reductions.
Same town, opposite stories. Small sample sizes explain most of it, because a handful of sales moves a monthly median a long way. A seasoned owner walking into an appraisal expecting the Redfin number can get a rude surprise.
Sizing cash-out here takes discipline:
- Assume the appraiser uses closed comps, not portal medians.
- Use about six months of ownership from title recording as the seasoning floor, not a target.
- Remember the 75 percent LTV ceiling is a cap, not what you will get. Proceeds depend on rent used for lender review, the full payment, reserves of roughly six months and the appraised value.
- Loans up to $3,000,000 fit standard programs. Smaller balances route through select lenders in the network.
Heavy price cuts cut both ways. They help a buyer’s basis, but they weaken the comps a later refinance depends on. A slow market is an appraisal risk for the refinancer, so a conservative valuation is the better planning assumption. The cash-out mechanics page walks through how LTV, seasoning and reserves interact.
What the Proceeds Should Do Next
Cash-out proceeds only make sense if the next deal covers itself. Murrells Inlet is appreciation-led, so the smart move is usually to redeploy equity into a property with better rent-to-price math. That might be a duplex, a small multi-unit or workforce stock in a market with higher rent relative to price. Pulling equity to buy another thin-coverage coastal house just stacks the same problem twice.
An owner who has built real equity might treat this as rebalancing. Roughly 0.4 percent of price in monthly rent (derived from the figures above) is a poor yield on a high-value asset. Moving a slice of that equity into higher-yield stock improves the portfolio without selling the original property. The refinance pathway for investor properties covers the options, and the side-by-side comparison shows why DSCR is often the cleaner route for owners with multiple properties and irregular income.
Investors can also review South Carolina DSCR financing for statewide context, since a portfolio rarely stays inside one town.
Skip the Oceanfront Side of Garden City
Garden City Beach sits on the Georgetown and Horry line, and Homes.com says it is one of the only inlet neighborhoods allowing rental homes. Verify that locally before you build a plan on it. Demand there is seasonal and vacation-oriented, which is a weaker fit for a lender looking at long-term lease income.
Two more cautions. Housing near Huntington Beach State Park is mostly higher-end and second-home stock, with little evidence of rental depth. And NeighborhoodScout shows 18.21 percent of local housing units are mobile homes or trailers. Manufactured homes, log homes and barndominiums fall outside the network’s DSCR programs, so those properties will not work here regardless of equity.
Verify current local rental rules, taxes and insurance with qualified local professionals before you commit. The county-line split means more than one jurisdiction may be in play.
DSCR vs. conventional financing
Two common ways to finance an investment property in Murrells Inlet, SC. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Murrells Inlet?
The lender looks at rent used for lender review against the full payment, with 1.00x as the common benchmark. Most files need about six months of ownership from title recording and a loan-to-value ceiling of 75 percent on cash-out. Reserves of about six months of PITIA are typical. Eligibility depends on lender guidelines, credit and property review.
What are the requirements for an investment property loan in Murrells Inlet, South Carolina?
Credit generally starts around a 620 floor, with better tiers at 660, 680 and 700. Reserves run about six months of PITIA, and standard programs go up to $3,000,000. Manufactured homes, log homes and barndominiums are outside the programs, which matters in a town with a real mobile-home share. Confirm current terms with a broker before planning around any number.
Can a self-employed investor buying in Murrells Inlet be reviewed for DSCR financing?
Yes. Lendmire places DSCR investor loans, and these programs are commonly evaluated around the property’s rental income rather than personal income paperwork. Approval is subject to lender guidelines, and LLC-titled borrowers are handled per lender program requirements.
Will Murrells Inlet’s conflicting price data hurt my cash-out?
It can. Redfin and Houzeo show opposite trends, so an appraisal can land above or below what an owner expects. Plan proceeds on a conservative value and don’t lean on a portal median.
Does a duplex really beat a single-family here?
On coverage, yes. Two rent streams against one purchase price is the main way to lift the number toward 1.25x or better in this market. The catch is availability, since multifamily listings are very thin. To see how a specific file might work, start your quote or call 828-256-2183.
About Lendmire
Lendmire (NMLS# 2371349), a non-QM mortgage broker serving investors in 41 markets including Washington, D.C., helps structure DSCR scenarios commonly evaluated around a property’s rental income rather than personal income paperwork, subject to lender guidelines. Recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2025, Lendmire places loans through wholesale investor lenders and is not a direct lender.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Movoto Murrells Inlet market trends
2. Apartments.com Murrells Inlet rent trends
4. City of Georgetown Facts and Figures
5. Georgetown County community update
7. NeighborhoodScout Murrells Inlet real estate
9. Homes.com multifamily snapshot
10. Redfin Murrells Inlet housing market
11. Houzeo Murrells Inlet housing market
12. Homes.com
13. a 2026 Scotsman Guide Top Mortgage Workplace
14. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Murrells Inlet SC · DSCR Cash Out Refinance Folly Beach South Carolina · Cash Out Refinance Investment Property Surfside Beach South Carolina
Guides: Investment Property Cash-Out Refinance in South Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.