
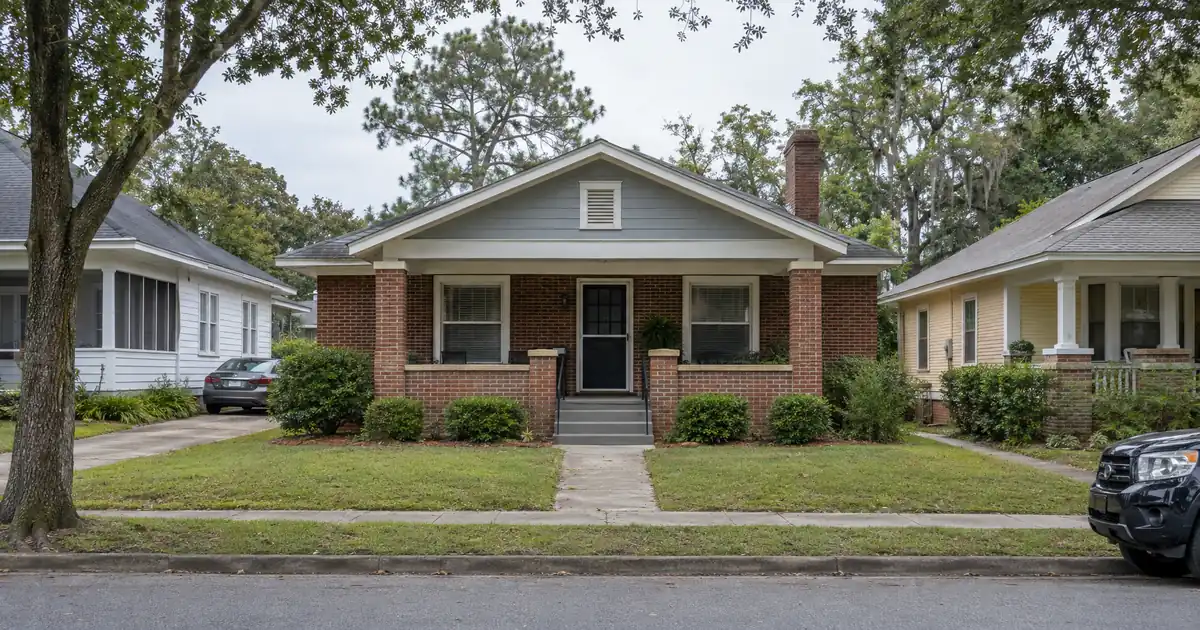
Waycross is sending mixed signals, and the next 6 to 18 months should settle which ones matter. Redfin’s latest read shows a median sale price of $76K, down 12.0 percent year over year, with 112 days on market. Other feeds show flat-to-modest movement. Meanwhile a Georgia Conservancy housing study says incoming economic development projects and population growth are straining local housing supply. Cheap, slow-selling, and possibly tightening is an unusual mix. For an owner sitting on a seasoned rental, it makes the appraisal the most important document in the file.
Lendmire is a DSCR-focused mortgage broker (NMLS# 2371349). Waycross, Georgia rental property investors can tap DSCR programs that Lendmire arranges, available across 41 markets, including Washington, D.C.
DSCR Cash-Out Calculator
Run the cash-out numbers in Waycross, GA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A DSCR cash-out refinance in Waycross, Georgia fits investors holding a seasoned two- or three-bedroom rental who want to recycle equity; the loan is underwritten primarily on the property’s rental income measured against its full monthly obligation, and proceeds are capped by a 75 percent loan-to-value ceiling applied to the appraised value.
- Sale-price reads run from $76K at Redfin to $168,500 at Resideline. The appraisal is the variable.
- Two- and three-bedroom units are 46.5 percent and 28.0 percent of ZIP 31501 rental stock.
- House-rent estimates span $850 at HotPads to $1,200 at Fundry. Underwrite the low end.
- Modeled coverage runs near 1.3x at $1,200 rent and near 0.9x at $850.
- Cash-out needs about six months of seasoning and stays at or below 75 percent LTV.
Waycross Market Snapshot
A quick read on the Waycross investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 8 sales (Redfin (sales)) |
| University enrollment | 4,130 students (Wikipedia: Coastal Pines) |
| Employment | 600+ staff/physicians/volunteers (Waycross-Ware County) |
The Equity Question Comes Before the Loan Question
Cash-out proceeds are the appraised value times the LTV ceiling, minus the payoff on the existing loan and closing costs. Waycross makes each piece of that sentence less certain than it looks. The ceiling for a cash-out refinance on an investment property is 75 percent, a separate cap from the purchase-side limit. Ownership needs about six months of seasoning, measured from title recording. Reserves typically run around six months of PITIA. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Review details remain subject to lender overlays and program guidelines.
The part most owners skip is that equity depends on value, and value in Waycross has to be argued for. Appraisers here work with thin comps. Holding the 75 percent ceiling constant, a $30,000 swing in appraised value moves your proceeds far more than any adjustment to the loan structure. That’s why a cash-out refinance in a thin market should start with comps, not with a lender shopping list.
For the general mechanics, the guide “The Refi Options” covers the program side, and the guide “What Is a DSCR Loan” covers the ratio itself. This piece stays on Waycross.
Why the Waycross Number Is Hard to Pin Down
Waycross sale-price data conflicts by a factor of nearly three, and investors should treat every median as a range. Redfin’s $76K comes from a month with only 8 sales, which makes it noisy. Movoto reports a $224,500 median on 146 sales, and Resideline shows $168,500 across 126 closings. Fundry’s typical home value is $149,874, up 1.7 percent year over year. Prop:Metrics puts the ZIP 31501 median at $134,000, down 5.6 percent.
Two individual Redfin sales show the dispersion: a three-bed, two-bath home on Cleve Road in 31503 sold for $205,000, and a four-bed on Pioneer Street in 31501 sold for $259,900. These are single transactions, not neighborhood medians. They do show that well-kept, larger houses can sit far above the city-wide figures, and that’s where a cash-out thesis has room to work.
Rents have the same problem:
| Source | Figure | Read |
|---|---|---|
| HotPads | $850 median, houses | House-oriented, low end |
| Apartments.com | $763 (2BR), $848+ (3BR) | Apartment-heavy, dated |
| Rentcast via Prop:Metrics | $1,120 (2BR), $1,500 (3BR) | ZIP 31501, modeled |
| Fundry | $1,200 median | Modeled estimate |
An appraiser’s rent schedule will probably land nearer the lower comps than the aggregator highs. Don’t size a cash-out on $1,200 without actual local leases in hand.
Running the Coverage Math
Coverage is monthly rent divided by the full monthly obligation: principal, interest, taxes, and insurance. Standard programs are built around a 1.00x benchmark, and some lenders will review lower ratios with more cash, lower leverage, or stronger credit.
Run the numbers on a modeled $150,000 appraised value (close to Fundry’s typical value) at the 75 percent LTV ceiling. These are modeled assumptions, not market data, and they assume a 30-year term with taxes and insurance included in the obligation:
- $1,200 rent: coverage of around 1.3x.
- $1,000 rent: about 1.1x, still clearing the benchmark.
- $850 rent: about 0.9x, below 1.00x.
The spread between the first and last lines is only $350 of monthly rent, and it decides whether the file is clean or difficult. At the low end, the options a lender might review are a sub-1.00 program, an interest-only structure, or reduced leverage. Each is subject to lender guidelines, credit review, and property review, and none is automatic.
DSCR files in markets like this one typically come in with a wide gap between the owner’s rent assumption and the appraiser’s rent schedule. The stronger files arrive with signed leases, a few comparable local rentals, and a realistic view of the valuation before the order goes in. The files that struggle usually lead with the highest aggregator rent and the lowest payoff balance and assume the appraisal will follow.
One more wrinkle: at Waycross price points, loan balances can be small. Loan amounts up to $3,000,000 are available on standard programs, but smaller balances route through select lenders in the network. Plan for that rather than assuming a standard-program fit.
Where Waycross Equity Gets Built
The Waycross equity stories that work involve forced appreciation through renovation, not market lift. Resideline lists the city among Georgia markets with 100 or more closings and medians well under the state’s $360,000, which is a cash-flow profile, not an appreciation one. Prop:Metrics’ ZIP 31501 data shows the core rental product clearly: two- and three-bedroom units are 46.5 percent and 28.0 percent of rental stock. Neighborhood-level price and rent data doesn’t exist in any source reviewed, so what follows is character and investor relevance, not numbers.
The residential Historic District is the best renovation-play candidate. It’s a 178-acre district listed on the National Register in 1976, bounded roughly by Plant Avenue and Williams, Lee, Chandler, and Stephen Streets, with Victorian-era housing stock. Older houses here suit buy, renovate, season, and refinance, where the renovation itself creates the equity. The catch is appraisal risk. Renovated homes need renovated comps, and with volume this thin, an appraiser may struggle to support the after-repair value you’re counting on.
ZIP 31501 broadly is where the rent data is deepest, and the two- and three-bedroom mix fits a workforce single-family strategy. For a typical 31501 house, the Rentcast figures are $1,120 for a two-bedroom and $1,500 for a three-bedroom. Treat the three-bedroom number as a ceiling.
The Darling Avenue corridor around Memorial Satilla Health gives a rental a demand anchor. The hospital is a 231-bed regional referral center serving more than 185,000 residents across nine counties. Hospital staff are a steady tenant pool, though no source ties specific prices or rents to this corridor.
Downtown’s historic district is walkable, sits near the rail depot and CSX yard, and is a nationally recognized Main Street city, per the City of Waycross. It’s interesting for small conversions and less useful for a clean cash-out, because the product mix is irregular and comps are scarce.
The outer south and west (31503, Cleve Road, Laura Walker Road) got the headline sale above, but one sale isn’t a pattern. Skip extrapolating from it. One $205,000 closing tells you a good house can sell there, not what yours will appraise for.
The Rice Yard Tenant Base (and Its Limits)
Waycross rental demand rests on rail, health care, and a thin but real employment base, not on a university or a military installation. The Waycross-Ware County Development Authority calls the local CSX facility the company’s largest and most productive automated classification yard. The Rice Yard covers 850 acres with about 150 miles of track, and nearly 300 acres are available for industry seeking rail access. The city is named for six rail lines meeting there.
Data USA shows resident employment concentrated in manufacturing (623 people), retail trade (586), and health care and social assistance (522). Census Bureau QuickFacts puts the population at 13,756 with a median household income of $38,301. Other anchors include Memorial Satilla, which reports more than 600 employees, physicians, and volunteers, and Coastal Pines Technical College, with more than 200 full-time employees.
That income figure explains why the 2- and 3-bedroom workforce product dominates and why the rent ceiling is modest. Here’s the cautionary note: the same Data USA source shows resident employment fell 6.57 percent from one year to the next. A small city with one dominant industrial employer is concentrated, and a cash-out that assumes rent growth is betting on a base that just shrank. Underwrite flat rents and treat any growth as a bonus.
Putting the Proceeds to Work (or Skipping the Cash-Out)
The proceeds only make sense if the next deal clears its own coverage math, because a cash-out that fails to earn more than it costs is just a larger loan. In a market where prices are soft and days on market are long, there are two defensible uses: fund a renovation on another Historic District house, or seed a purchase in a market with stronger appreciation and an exit you can count on. Movoto reports 80 days on market, and Fundry reports about 63 days to contract with 22.2 percent of listings taking a price cut. That’s a thin exit, so the plan should be hold and refinance, not build and flip.
The stronger play might be skipping the cash-out if the rent schedule comes back near $850. At that level you’d be stretching for coverage and leaving reserves thin, and a rate-and-term refinance or a simple hold could serve the portfolio better. Investors buying for appreciation could argue the other way, but the price direction in Waycross is unclear, and a cash-out thesis here should rest on rent coverage and forced equity. It’s worth understanding the details of both rate-and-term and cash-out refinances, and the conventional-vs-DSCR tradeoffs matter if your personal income is strong enough to consider the alternative. For the broader picture, see DSCR loan options for Georgia investors.
Investors can see how the DSCR math pencils on a specific property, or reach the brokerage at 828-256-2183. Verify current local rental rules, taxes, and insurance with qualified local professionals before committing.
DSCR vs. conventional financing
Two common ways to finance an investment property in Waycross, GA. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Waycross, Georgia?
The property’s rent has to cover its full monthly obligation, with 1.00x as the standard benchmark. Most files also need a credit score of at least 620, about six months of reserves, and roughly six months of ownership. In Waycross the practical hurdle is the appraiser’s rent schedule, which tends to land nearer the low end of the rent estimates. Final eligibility is subject to lender guidelines and property review.
What are the requirements for an investment property loan in Waycross, Georgia?
For a cash-out, the requirements are about six months of seasoning, a loan-to-value ceiling of 75 percent, and rent used for lender review at or above the benchmark against full PITIA. Manufactured homes, log homes, and barndominiums fall outside these programs. Small balances common at Waycross prices may route through select lenders in the network. Terms vary by borrower, property, and loan scenario.
How much equity can I pull from a Waycross rental when the price data conflicts so much?
It depends on the appraisal, not on any city median. City-wide figures range from $76K to $224,500 depending on source, and monthly sales counts are low enough to make medians volatile. Proceeds equal the appraised value times 75 percent, minus your payoff and costs, and that result isn’t a fixed figure. Gather recent sold comps for similar houses before planning what to do with the cash.
Can a LLC-owned Waycross rental be reviewed for DSCR financing?
Yes, subject to lender program eligibility. Lendmire arranges DSCR investor loans, and because the file is underwritten primarily on the property’s cash flow, entity-owned rentals are a common fit.
Is Waycross a cash-flow market or an appreciation market?
Cash flow, by a wide margin. Fundry models an unlevered cap rate near 5.8 percent, while price direction ranges from up 1.7 percent to down 12.0 percent depending on source. Build the cash-out case on rent coverage and renovation-driven equity, not on market lift.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
Before You Order the Appraisal
If the appraiser’s rent schedule for your Waycross rental came back $350 below the listing you’re picturing, would the cash-out still be worth doing?
About Lendmire
A non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR financing for real estate investors in 41 markets, which means 40 states plus Washington, D.C. Because deals are underwritten primarily on property cash flow rather than personal income documentation, the structure suits self-employed buyers and entity-owned portfolios. Lendmire places loans through wholesale investor lenders and is not a direct lender. It has been recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. $76K, down 12.0 percent year over year, with 112 days on market
2. Georgia Conservancy housing study
4. 46.5 percent and 28.0 percent of ZIP 31501 rental stock
9. Movoto reports a $224,500 median on 146 sales
10. City of Waycross
11. Rice Yard covers 850 acres with about 150 miles of track
12. walb.com — Waycross Ware Co Railroad Expansion Creates Job Opportunities Industry Growth
13. Data USA
15. Coastal Pines Technical College
16. a 2026 Scotsman Guide Top Mortgage Workplace
17. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Georgia
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.