
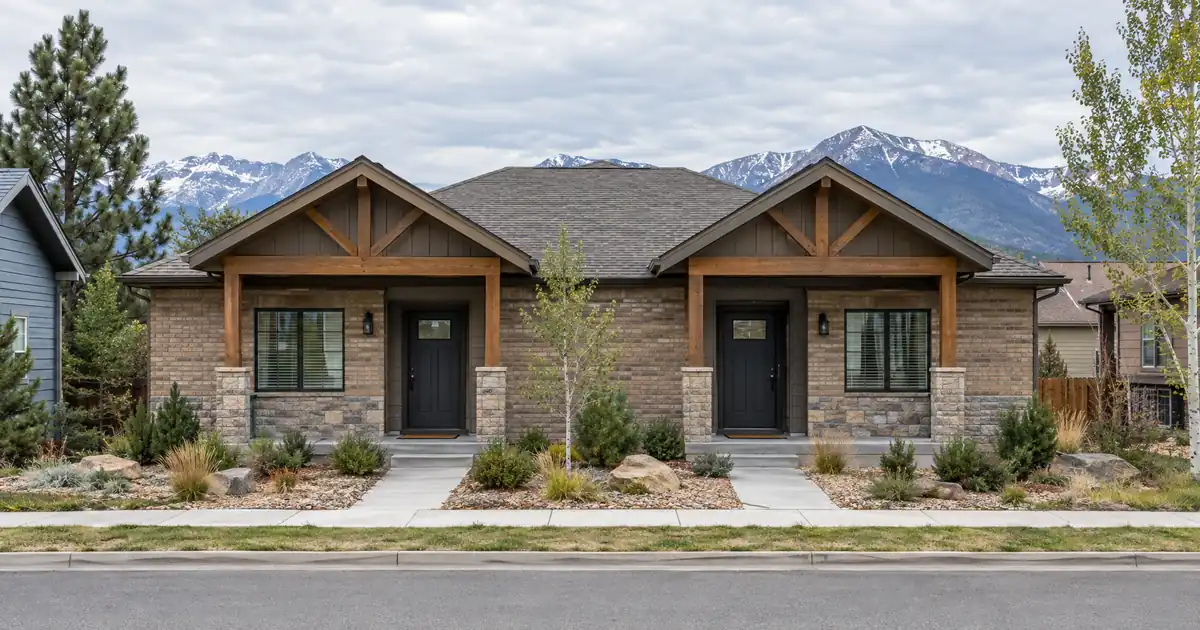
An out-of-state investor scrolling Parker listings sees a lot to like. Median household income sits near $139,826, the town has roughly 65,765 residents, and a Level II trauma hospital anchors the local economy. The Cherry Creek Trail runs through it. What that investor tends to miss is the ratio between price and rent. A DSCR cash-out refinance here is constrained less by demand than by arithmetic, and the coverage number is what decides how much equity can come out.
Investors underwriting deals in Parker, Colorado can use DSCR programs Lendmire arranges, available across 41 markets, including D.C. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker, and the sections below cover how equity extraction pencils in this specific suburb.
DSCR Cash-Out Calculator
Run the cash-out numbers in Parker, CO
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A DSCR cash-out refinance in Parker, Colorado is underwritten primarily on the property’s rental income measured against its full monthly obligation. The deal works from ownership seasoning to appraisal to a coverage test, with proceeds capped by the 75 percent LTV ceiling and subject to lender guidelines.
- Median sale price is $675K, down 1.3 percent year over year.
- Modeled single-family coverage at the 75 percent ceiling lands near 0.7x, including taxes and insurance.
- Paired homes and townhomes in Old Town and Meridian Village carry the best rent per dollar of price. AdventHealth Parker employs more than 1,100 people and anchors tenant demand.
- Falling price per square foot means appraisals may not validate purchase-era equity.
The Coverage Problem at the Median
The median Parker single-family rental does not clear 1.0x coverage at maximum leverage. Two independent rent sources show why. Zumper puts the median rent across all property types at $2,645, a listing-based figure. RentCafe reports $2,723 for a three-bedroom, though its data covers buildings with 50 or more units, so it is not a single-family figure. Against a $675K median sale price, both imply gross monthly rent-to-value of roughly 0.4 percent. That is thin.
Run the numbers this way, using modeled assumptions rather than sourced market data. Take a $675K single-family home, rent at about $2,700, and a 75 percent LTV cash-out refinance on standard 30-year terms. Full obligation including taxes and insurance produces coverage near 0.7x. Drop leverage toward 50 percent and the number climbs to roughly 1.0x. The standard DSCR benchmark is 1.00x because rent covers the payment at that level. Some lenders review lower ratios, but those files typically need stronger compensating factors, lower leverage, or different pricing, and eligibility depends on lender guidelines, credit profile, and reserves.
Here’s the catch. The equity may exist on paper while the rent only supports a fraction of the 75 percent ceiling. Leverage ends up set by coverage, not by the LTV cap. How the qualification works is straightforward, but in Parker the ratio is the binding constraint on proceeds.
Appraisal Risk in a Drifting Market
Parker prices are flat to slightly down, which changes the extraction math for anyone who bought recently. Redfin shows the three-month median sale price at $675K, down 1.3 percent year over year, while price per square foot slipped 5.1 percent to $205. Zillow puts the average home value higher, at $706,476, down 1.7 percent, reflecting a different methodology. Direction agrees across sources even where levels do not.
The implication for a cash-out file is direct. An investor holding a property bought near the recent peak should not assume appreciation. The appraisal may land near or below the purchase price, which shrinks the equity the 75 percent ceiling can reach. Program guidance typically looks for about six months of ownership, measured from title recording, before a cash-out refinance is available. Seasoning is the easy part. The appraised value is the variable.
Liquidity is better than the price trend suggests. Redfin reports roughly 33 days on market, about two offers per home on average, and 441 closed sales in August against 474 a year earlier. Comp supply is adequate for standard single-family product, but volume is slipping, and a thin comp set for an attached or paired property can widen the valuation range. Anyone planning a refinance over the next 6-24 months should track that sales count. A continued decline in volume is the early warning that appraisals get harder before prices visibly break.
Where the Price-to-Rent Ratio Improves
Per Homes.com median prices, The Pinery single-family sits near $875K, Stonegate near $694K, and Stroh Ranch near $627K. Old Town townhouses come in around $380K, with condos at $295K for one bedroom and $360K for two. Figures are approximate, since the page carries no visible date. The spread runs more than 2x from bottom to top while rents do not scale with it.
No neighborhood-level rent source exists for Parker, so submarket coverage below is directional. Verify rents against actual comps.
Old Town townhomes and condos
This is the strongest rent-per-dollar product in the data. Model a $380K townhome at 75 percent LTV against rent near the RentCafe two-bedroom figure of $2,184 (a modeled assumption, since no townhome rent series exists). Full obligation including taxes and insurance puts coverage at roughly 1.0x. That is the only segment where maximum-leverage cash-out plausibly works without restructuring. Older, larger lots in Rowley Downs, the “old Parker” pocket near the core, are where any small-multifamily or accessory-unit potential would most likely sit, though no source quantifies it.
Meridian Village, Stonegate north, and Dove Village
The E-470 corridor has the most varied product: paired homes, townhomes, and single-family. DougCo Social describes Meridian Village as 15-20 minutes off-peak from the Denver Tech Center. A local neighborhood guide also lists paired homes in Challenger Park Estates and Stroh Ranch. Paired product is the closest thing Parker has to a middle path between a $380K condo and a $675K detached home.
Stroh Ranch
The master-planned community along the Cherry Creek Trail, with a DougCo Social range of $500K-$750K, offers a mix of single-family homes and townhomes. A $627K median at 75 percent leverage models near 0.75x on $2,700 rent. Workable only with reduced leverage or rent above the town averages. Not a bad asset. Just not a maximum-proceeds one.
The Pinery and Pradera
Skip them for DSCR purposes. With homes reaching $1.5M and above, rents cannot approach the coverage these prices demand. Equity is large, coverage is poor, and the loan amount is limited by the ratio long before the 75 percent cap matters.
The Multi-Unit Mirage
Multi-unit stacking would fix the ratio, but Parker has almost none. Per RentCafe, 72 percent of households are owner-occupied and 28 percent rent. Listing pages tell the same story: Zillow’s duplex and triplex page shows 21 homes in its title, and Compass returned zero multi-family listings in Parker North at the time of retrieval. These are live pages, so counts change daily, and no duplex, triplex, or fourplex price data was available.
An investor who already owns one has a scarce asset. That cuts both ways. Scarcity supports rents and exit liquidity, but anyone planning to buy a fourplex to refinance later is planning around inventory that barely exists. Attached townhomes and paired homes are the realistic substitute.
Demand Anchors That Underwrite Tenant Durability
Tenant demand in Parker rests on a medical cluster unusual for a town of this size. AdventHealth Parker is the town’s largest employer, and per Parker Economic Development it carries 55-plus specialties. DougCo Social describes a $300M expansion underway and notes that a Kaiser Permanente outpatient facility recently opened. Safran Defense & Space, the Town of Parker, and the Parker Fire District round out the named employers, though headcounts beyond AdventHealth were not found.
Rocky Vista University adds a graduate health-professions population. Data USA reports 1,574 students, and other sources run higher, so a range of roughly 1,500-1,900 graduate students is the honest framing. Hospital staff and medical students rent for predictable, employment-linked reasons, which supports lease continuity. It does not fix the rent-to-value ratio.
Working DSCR brokers see a recurring pattern in high-price commuter suburbs like this one: the equity is substantial, the demand is steady, and the coverage ratio is the thing that trims proceeds. Files tend to close the gap through lower leverage, stronger reserves, or a property type with better rent per dollar rather than through optimistic rent assumptions. Appraisers and lenders both discount listing-based rent figures that stray far from leased comps.
What the Program Looks Like
Cash-out refinance guidance is generally built around a 75 percent LTV ceiling, about six months of ownership from title recording, and a minimum DSCR of 1.00. Credit tiers commonly start at a 620 floor with pricing and leverage improving at higher scores (660, 680, 700). Reserves typically run about six months of full payment, rising to about nine above $1,500,000. Loan amounts go up to $3,000,000 on standard programs, with smaller balances routed through select lenders. Program details are subject to lender guidelines and can change, so confirm them before structuring a file.
Equity available is not a guaranteed figure. It depends on rent used for lender review, the full payment including taxes and insurance, reserves, and the 75 percent ceiling. Properties held in an LLC are generally considered subject to lender program eligibility. Manufactured homes, log homes, and barndominiums fall outside these programs.
Two structural questions matter most for Parker: what the proceeds will do and whether they justify reduced leverage. Rate-and-term and cash-out refi details help frame the choice, and the refi options lay out how each path changes coverage. Against conventional underwriting, the guide “Where DSCR and Conventional Diverge” come down to documentation and how income is measured. Investors can run the numbers with Lendmire before committing to a leverage level, and the DSCR loans in Colorado hub page covers state-specific considerations.
Indicators That Decide the Next 6-24 Months
Three data points tell an investor whether Parker equity is firming or eroding:
- Price per square foot. It fell 5.1 percent while the median dropped only 1.3 percent. If it keeps sliding, appraisals follow.
- Closed sales volume. A gap from 474 to 441 is small. A widening gap thins comps.
- Hospital campus progress. The AdventHealth expansion is the clearest source of new medical employment. Delays or completions shift the tenant pool.
Rents, meanwhile, are creeping up: RentCafe shows average apartment rent up 2.77 percent year over year. If rents keep rising while prices drift down, rent-to-value improves from both sides, and coverage on the same property gets better without any change in leverage. That divergence is the thing to watch, and it is not guaranteed. Investors should also verify current local rental rules, taxes, and insurance with qualified local professionals.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Parker, Colorado?
Qualification centers on the property: rent used for lender review divided by the full monthly obligation should generally reach at least 1.00x, with about six months of seasoning and a credit score at or above the 620 floor. Reserves of roughly six months are typical. At Parker’s roughly 0.4 percent rent-to-value, many single-family files need leverage below the 75 percent ceiling to reach that ratio. Final eligibility rests with the lender.
DSCR vs. conventional financing
Two common ways to finance an investment property in Parker, CO. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Parker, Colorado?
Expect a rent-based coverage test, reserves, a credit minimum, and a property review. Loan amounts run up to $3,000,000 on standard programs, and the 75 percent cash-out LTV cap applies to equity extraction. Manufactured homes, log homes, and barndominiums are excluded. All terms are subject to lender guidelines and credit approval.
Why is coverage so tight on Parker single-family homes?
Price has outrun rent. A $675K median against rents in the $2,600-$2,700 range produces roughly 0.4 percent monthly rent-to-value, which yields modeled coverage near 0.7x at the 75 percent ceiling including taxes and insurance. Attached product in Old Town and Meridian Village improves that ratio because price per door is far lower.
Does falling Parker pricing hurt cash-out proceeds?
Yes, it can. Proceeds depend on appraised value, and Redfin data shows the median price and the price per square foot both trending lower. An investor who bought recently may find the appraisal near the purchase price, leaving less equity under the 75 percent cap. Sales are still moving at a steady pace, so comparable sales are generally available to support an appraisal.
Can a self-employed investor buying in Parker be reviewed for DSCR financing?
Yes. DSCR eligibility is generally reviewed around the property’s rental income rather than personal income, which suits self-employed investors, subject to lender and program guidelines. Lendmire arranges DSCR investor loans with cash-out refinances available up to the 75 percent LTV ceiling.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
Where the Asymmetry Sits
The mispricing in Parker is not at the top or the middle of the market. It is in attached product near the medical and commuter anchors: Old Town townhomes around $380K and paired homes along the E-470 corridor in Meridian Village. Those properties carry the town’s best rent per dollar of price, draw from the same hospital, medical-school, and Tech Center commuter demand as the $700K detached homes, and sit closest to the 1.0x coverage line at maximum leverage.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. Eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, which suits self-employed investors and LLC-owned portfolios. Lendmire was recognized as a top-ranked workplace in 2026 and recognized by Scotsman Guide in 2025 as a Top Mortgage Workplace. Reach the team at 828-256-2183.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. $675K, down 1.3 percent year over year
3. Zumper
4. RentCafe
5. Zillow
6. Homes.com
8. parkercoloradohomecenter.com — Parker Colorado Neighborhoods
9. Zillow’s duplex and triplex page
10. Compass
11. Parker Economic Development
12. DougCo Social
14. Data USA
15. Scotsman Guide — Top Workplaces 2026
16. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Parker, CO · Investment Property Cash-Out Refinance in Colorado
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.