
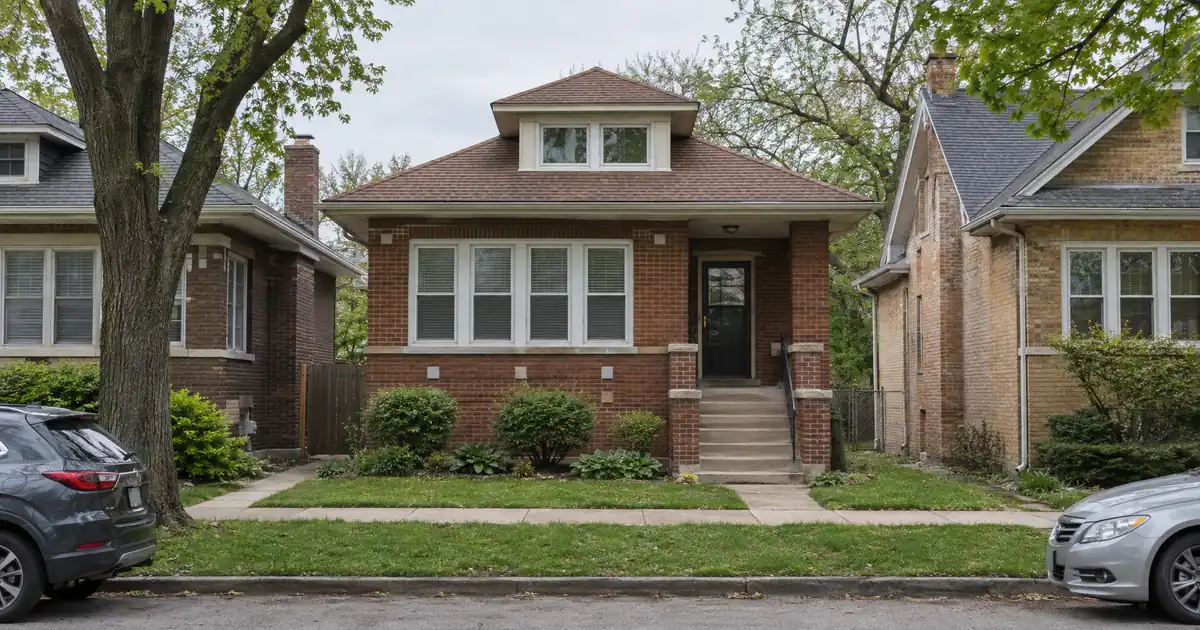
Picture an investor holding a two-flat bought at $450,000 near the Davis Street Purple Line stop. Leases have been reset to market as tenants turned over, and the building is now likely to appraise well above the purchase price. The investor wants to pull capital out for the next acquisition without pushing the building’s rent-to-debt ratio under water. The question is how much equity is actually reachable, and what decides it.
At a Glance: A cash-out refinance in Evanston, Illinois is underwritten primarily on the property’s rental income measured against its full monthly obligation, and the city’s Housing Gap Analysis finds older small rentals especially tight.
DSCR Cash-Out Calculator
Run the cash-out numbers in Evanston, IL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Older 2-4 flats are under-represented against Cook County.
- North Evanston detached homes carry prices that rent rarely covers.
- Cash-out proceeds are capped at 75 percent of appraised value.
- About six months of ownership typically precedes a cash-out.
- Thin comparable sales make appraisal, not rent, the main swing factor.
Evanston, Illinois is one of the 41 markets — 40 states plus Washington, D.C. — where Lendmire places DSCR loans for investment-property borrowers (NMLS# 2371349). The brokerage arranges these through wholesale and investor channels, so eligibility and approval sit with the lender. For statewide context, see Lendmire’s Illinois DSCR platform.
How the Equity Math Works, Step by Step
The reachable equity is the smallest of three ceilings: the loan-to-value cap, the coverage test, and the reserve requirement. Walk through them in order and the answer becomes predictable. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Step one is the value ceiling. On a cash-out, the program cap is 75 percent of appraised value. That is lower than the purchase-side cap, and it does not bend. If the existing payoff already equals 50 percent of appraised value, the gross headroom is 25 percentage points of value. Nothing more.
Step two is seasoning. Programs generally look for about six months of ownership measured from title recording. An investor who bought recently and renovated can often satisfy this quickly in calendar terms, but the appraised value still has to support the number.
Step three is coverage. The standard DSCR benchmark is 1.00, meaning rent used for lender review covers the full monthly obligation: principal, interest, taxes, insurance and any association dues. A bigger new loan raises that obligation. So a building that clears 1.00 at its old balance can fall short at the new one. Some programs review lower coverage with lower leverage or extra cash reserves, and some lenders review no-ratio files, but those usually come with tighter terms. Eligibility depends on lender guidelines, credit profile, reserves and property review.
Step four is reserves and credit. Expect about six months of reserves, rising to about nine on balances above $1,500,000. Credit tiers commonly sit at 620, 660, 680 and 700, with 620 as the floor. Better credit can widen the leverage available. Standard programs run up to $3,000,000, and smaller balances route through select lenders in the network.
Run the sequence, and the proceeds are whatever remains under the value ceiling after the payoff, closing costs and reserves, limited again by coverage. It is never a guaranteed cash figure. A primer on “What Is a DSCR Loan” covers the underlying formula, and the cash-out page explains pulling equity out in more detail.
Why Older Small Flats Are Evanston’s Best Cash-Out Collateral
Evanston’s 2-4 unit buildings are scarce, old and sitting in a tight rental segment, which makes them the strongest candidates for a DSCR cash-out. The city’s Housing Gap Analysis says attached single-family and 2-4 unit buildings make up a significantly lower share of housing than across Cook County. It also describes the for-sale market as tight and rental vacancy as balanced-to-tight, with particularly tight conditions in older Class C properties. Read together, that supports stacked-unit income. That is an inference from the sources, not a published rent-to-value figure.
The stock skews old. Point2Homes reports that 33 percent of apartment rentals, 4,534 units, were built in 1939 or earlier, and that two-bedroom units are the largest slice of rentals at 38 percent. That favors two-bedroom-per-floor duplexes and triplexes. RentCafe puts renter-occupied households at 13,898, or 44 percent of the total.
Value by structure type shows why stacking matters. City-Data lists mean values of $755,130 for detached houses and $458,809 for two-unit structures. Its 3-4 unit mean of $285,529 is probably skewed by condos or small samples, so treat it qualitatively: multi-unit values sit well below detached values. The same source shows median gross rent of $1,737.
| Property type | Mean value (City-Data) | Cash-out fit |
|---|---|---|
| Detached house | $755,130 | Weak: one rent, large balance |
| 2-unit structure | $458,809 | Strong: two rents, one loan |
| 3-4 unit structure | Skewed, qualitative only | Strong if comps exist |
| 5+ unit building | Commercial programs | Outside typical DSCR scope |
One modeled illustration, not a sourced coverage figure: a single median-rent unit is a small fraction of a $755,000 house’s value, while two or three units on a lower-priced parcel improve that ratio considerably. The math favors the flat.
Working DSCR brokers see a recurring pattern in older, small-building suburbs like this one. The rent side usually looks fine. The friction sits in the appraisal, where a thin set of comparable sales and an older building’s deferred maintenance pull the value below the owner’s expectation. Files that arrive with a recent rent roll, documented capital work and a short list of comparable small-building sales tend to hold their leverage assumptions better than those that rely on the owner’s opinion of value.
Thin Comps, Noisy Medians
Appraisal risk is the core technical problem in Evanston cash-outs. A listing snapshot from Homes.com showed just 8 multi-family listings, priced from $369,000 to $1,045,000, with an average of 19 days listed before selling. That is a very thin inventory. A cash-out lives on the appraiser’s comps, and a small pool means the value may lean on a few sales or on older ones. Ask the lender how comps are selected before committing to a leverage assumption.
Submarket medians make it worse. Portal data for individual neighborhoods swings widely, with year-over-year moves in the tens of percent in both directions, and the samples are small and mix condos with houses. Those swings likely reflect a changing mix of property types rather than real price moves. The practical takeaway: do not build a refinance on a neighborhood median. Build it on a handful of closely matched sales, and size leverage conservatively.
City-level readings are steadier but still disagree. Zillow puts the average Evanston home value at $459,534, up 3.5 percent over the past year, with homes going pending in around 9 days. Movoto reports a higher median sold price of $487,000, reflecting a different method. Both describe a market with modest positive appreciation and real buyer competition. That is enough to support a cash-out, because value is not falling, but not enough to assume large gains since purchase.
Where the Coverage Holds (and Where It Doesn’t)
Coverage is best in the transit-adjacent flat markets and weakest in North Evanston. Submarket-level rent data is the gap here: no reliable neighborhood rent source turned up for 2-3 bedroom units, so the submarket read below rests on sale prices, housing stock and demand anchors rather than rents.
Downtown and the Davis corridor. Downtown Evanston is the transit hub, with the CTA Purple Line at Davis and Metra UP-N. Redfin showed a median near $415,000 and about $365 per square foot. The sample is small and includes condos, so use it as a directional read. The cash-out case here is a small flat or a condo-adjacent asset where the lower balance keeps the coverage test comfortable.
Central Street and the Ryan Field corridor. This area pairs restaurants and shops with Evanston Hospital and the university’s athletics district. The Daily Northwestern notes Ryan Field is a 5-10 minute walk west of the Central station. No price data was sourced here, but the tenant mix of hospital staff and graduate students is what keeps older flats leased.
North Evanston. Skip the detached homes. Redfin shows a median near $916,000 and about $403 per square foot. At that price, single-family rent rarely covers a large refinance balance once taxes and insurance are included. A coverage number that pencils on principal and interest alone will break when those carrying costs go in.
South Evanston, West Evanston and the Dempster-Dodge area. All are transit-adjacent, with the Main Street and South Boulevard Purple Line stops and the high school on Dodge. No sourced price or rent data exists for them, so they stay qualitative. They are where an investor should hunt for 2-4 flats, while pulling recent closed sales directly.
For larger buildings, LoopNet lists Evanston apartment-building cap rates typically between 5.98 and 6.65 percent. That likely reflects larger assets, not 2-4 flats, and small buildings probably price at lower yields because owner-occupants compete for them. Treat it as a benchmark only. Buildings beyond four units move to commercial or multifamily programs outside typical DSCR scope.
The Tenant Base Behind the Rent Roll
Evanston’s demand does not come from population growth. Census Bureau QuickFacts shows 75,994 residents across 7.8 square miles, with median household income of $93,016. Census QuickFacts shows a 75,070 estimate and a 3.9 percent decline from the April 2020 base. Flat to slightly shrinking. Institutions carry the load.
Northwestern University enrolled 23,312 students per a regional college: 9,039 undergraduate and 14,273 graduate. The large graduate share matters for small-building landlords, since graduate students rent off campus. The university has described itself as Evanston’s largest employer, though that claim comes from a dated newsletter and no current headcount was found.
Endeavor Health is headquartered in the city and cites more than 27,000 team members across nine hospitals system-wide, with the Evanston-only count unavailable. The Illinois Education and Career Success Network lists the Mayor’s Employer Advisory Council at 156 members representing 91 employers. The City of Evanston counts seven Purple Line stops plus three Metra stops, and the DePaul Institute for Housing Studies places the city 12 miles north of downtown Chicago. City-Data also reports a daytime population gain of 13,719, or 18.1 percent, from commuting.
Rent data needs a caveat. RentCafe’s $2,604 average rent, with $2,430 for a one-bedroom and $3,245 for a two-bedroom, comes from buildings with 50 or more units. It does not represent small 2-4 flats. Point2Homes shows 2.4 percent rent growth against RentCafe’s 0.51 percent. Call it roughly flat to low single digits. No reliable single vacancy number is available either, because sources conflict, so the city’s balanced-to-tight read is the one to use.
Recycling the Proceeds
The point of a cash-out is what the money does next. Most investors here use proceeds one of three ways: as a down payment on the next small building, to fund capital work that lifts the next appraisal, or to build the reserves a larger file requires. The second use compounds in this market, because older stock carries capex questions and documented improvements help the appraiser support value.
One caution on sequencing. Cash-outs held in LLC title are available on many programs, subject to lender program eligibility, but entity structure should be settled before the refinance, not after. Also confirm current local rental rules, taxes and insurance with qualified local professionals, since those carry costs feed directly into the coverage number.
For a comparison of structures, Lendmire’s guide to DSCR versus conventional financing covers how income documentation differs. Investors weighing a rate-and-term or cash-out path can review their refinancing options, or compare DSCR options directly. A call to 828-256-2183 also works.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Evanston, IL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The Blind Spot: Appraisal Dependence
The single biggest risk for DSCR-financed investors in Evanston is that value, not rent, caps the cash-out. A scarce small-building inventory is what makes these assets attractive, and it is also what leaves an appraiser with few closely matched sales. Combine that with old buildings that may draw inspection and capital questions, and a flat population that offers no growth cushion, and the owner’s expected value can come in light. Size every cash-out on a conservative value, not the optimistic one.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Evanston, Illinois?
Qualification centers on the property’s rent used for lender review against its full monthly obligation, with 1.00 as the standard benchmark. Lenders also review credit (tiers commonly start at a 620 floor), about six months of reserves and about six months of ownership. Cash-out leverage tops out at 75 percent of appraised value. Final eligibility is subject to lender guidelines and property review.
What are the requirements for an investment property loan in Evanston, Illinois?
Expect a review of rent against debt service, credit tier, reserves and property type. Manufactured homes, log homes and barndominiums fall outside these programs. Older 2-4 flats are eligible property types, but appraisal and condition matter. Requirements vary by lender and loan scenario, and nothing here is a commitment to lend.
Can a North Evanston single-family rental support a cash-out?
Rarely, in many cases. Because values in the neighborhood sit well above much of the metro, one rent has to carry a large balance plus taxes and insurance, and coverage usually lands below 1.00. A lower-leverage structure or a different property may work better. Some lenders review sub-1.00 files, typically with lower leverage, stronger reserves or different pricing.
Does Evanston’s older housing stock complicate a cash-out appraisal?
It can complicate one. About a third of apartment rentals predate 1940, so appraisers may weigh condition and capital needs, and the thin small-building comp pool can limit the value used. Documented repairs, a current rent roll and recent comparable sales help the file.
What loan-amount ranges may DSCR lenders review for Evanston rental properties?
Lendmire arranges DSCR investor loans. Final amounts depend on rent, reserves, credit and the 75 percent cash-out ceiling.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor financing, helping arrange programs through wholesale and investor-lending channels in 41 markets, including Washington, D.C. DSCR loans are evaluated by the lender on property cash flow rather than personal income, subject to lender guidelines, supporting LLC closings and accommodating investors with four or more financed properties. Scotsman Guide Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. City of Evanston Housing Gap Analysis
2. Point2Homes
3. RentCafe
4. Homes.com
5. Zillow
6. Movoto
7. Redfin
9. LoopNet
10. U.S. Census Bureau QuickFacts, Evanston
12. Endeavor Health
13. Illinois Education and Career Success Network
14. City of Evanston Public Transportation
15. DePaul Institute for Housing Studies
16. 2025
17. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Evanston, IL · Investment Property Cash-Out Refinance in Illinois
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.