
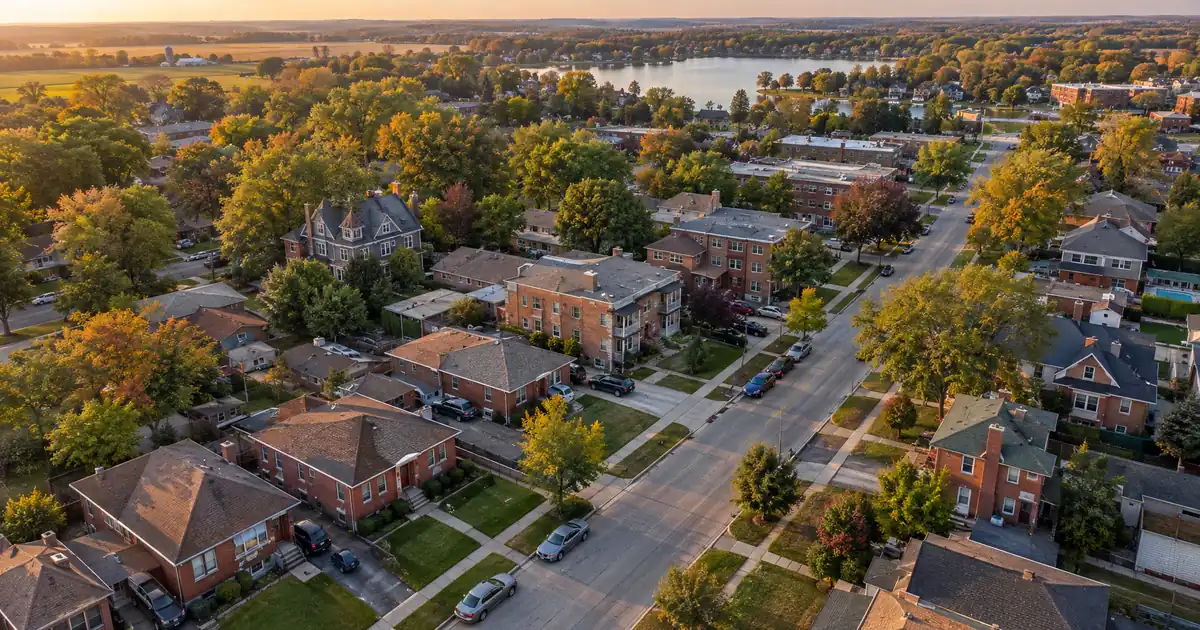
If you own a rental in Crystal Lake that has appreciated since you bought it, the question isn’t whether there’s equity. The question is how much of it a lender will count after the appraisal, the 75% loan-to-value ceiling, and the coverage test. This is a cash out refinance investment property market where the answers differ sharply by property type. A three-bedroom house, a condo, and a scarce duplex near the train each pencil differently.
DSCR Cash-Out Calculator
Run the cash-out numbers in Crystal Lake, IL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A cash-out refinance on a Crystal Lake, Illinois rental is underwritten primarily on the property’s rental income measured against its full monthly obligation. Proceeds are capped by a 75% loan-to-value ceiling and roughly six months of ownership, subject to lender guidelines.
- Downtown’s median sale price is $353K, up 9.9% year over year, per Redfin.
- Three-bedroom rents near $2,713 (Apartment Finder) put modeled coverage near 1.0, taxes and insurance included.
- Multi-family listings number in the low single digits at any time, so duplex appraisals rest on thin comps.
- New downtown apartment deliveries argue for conservative rent assumptions on older small rentals.
Crystal Lake Market Snapshot
A quick read on the Crystal Lake investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $420,886 median value (NeighborhoodScout) |
| Typical rents | $1,475 and $1,375 rents (Realmo Crystal Lake multifamily) |
| University enrollment | +670 students spring 2025 (Shaw Local / Northwest Herald) |
| Employment | 4,000+ employees (2013) (Centegra Health System) |
What the Appraisal Will Say About Your Equity
Crystal Lake’s equity story is steady, not spectacular, and the sources disagree enough that you should expect appraiser variance. A market source puts the citywide median at $369,500, up 2.64% year over year, with about 42 days on market and 0.62 months of supply. This article uses that median as the canonical citywide figure. Zillow’s average home value runs higher, at $388,566 and up 4.3%, but that reflects a different methodology (Zillow).
The submarket spread matters more than the citywide gap. Downtown Crystal Lake’s median sale price is $353K, or $228 per square foot, up 9.9% year over year, with roughly two offers per sale and about 44 days on market (Redfin). Downtown is priced below the citywide medians yet appreciating faster. For an owner who bought there, that’s the clearest path to new equity.
Context for the buyer pool: the city has about 41,513 residents per Data Commons, and the authoritative population and housing tables sit on Census Bureau QuickFacts. Tenure is lopsided. RentCafe counts 11,491 owner-occupied households against 3,315 renter-occupied, a 78/22 split (RentCafe). A small renter base means rentals compete for a limited tenant pool, and that shows up in the coverage math below.
The 75% Ceiling and Six Months on Title
Cash-out proceeds are the gap between your existing balance and 75% of the appraised value, then reduced by reserves and costs. The 75% cap is firm for cash-out, even though purchases can run higher. Equity is a ceiling, not a payout.
Per the program guidelines Lendmire works within, seasoning runs about six months of ownership measured from title recording. Reserves typically run about six months of the full monthly obligation (more on balances above $1,500,000). Minimum coverage is a 1.00 benchmark, rent measured against principal, interest, taxes, and insurance. Credit tiers step through 620, 660, 680, and 700, with 620 as the floor. Loan sizes reach up to $3,000,000 on standard programs. Everything here is subject to lender guidelines, credit approval, and property review, and none of it is a commitment to lend. The DSCR qualification mechanics explain how the ratio is built. The investor refinance breakdown covers the refinance types side by side.
Entity ownership works too. LLC-titled rentals can be considered, subject to lender program eligibility.
Here’s the practical read on equity. Suppose your balance sits near 60% of the new appraised value. You have real headroom under the 75% line. Suppose it sits near 74%. You have almost none, and the refinance only makes sense if you’re restructuring rather than extracting. The appreciation figures above are why owners from a couple of years back often land in the first group, while recent buyers at the top of the market land in the second.
Where the Coverage Number Clears
Single-family and duplex coverage in Crystal Lake diverge enough that the property type, not the neighborhood, decides whether a cash-out works. Modeled with full taxes and insurance, a three-bedroom lands near 1.0, an average-rent unit falls well under it, and a duplex clears with room.
Run the numbers on these modeled inputs. Rents and prices below are sourced. The financing assumptions are modeled (a standard 30-year term at 75% LTV), and coverage is rent divided by the full monthly obligation including taxes and insurance, rounded down. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
| Property input | Rent / price (modeled) | Coverage read |
|---|---|---|
| 3BR single-family | $2,713 on $369,500 | Right around 1.0 |
| Average-rent unit | $2,038 on $369,500 | Roughly 0.75-0.80 |
| Duplex, two units | $2,850 on $320K | Roughly 1.2-1.25 |
The three-bedroom rent comes from Apartment Finder, the $2,038 average rent from RentCafe, and the $320K from the median multi-family listing price on Redfin. Rent sources disagree, with Apartments.com at $1,820 for the city average (Apartments.com), so a roughly $1,800 to $2,500 band is the honest description.
If your rental lands under 1.00, there are paths a lender may review. Some programs allow sub-1.00 coverage with lower leverage or stronger reserves. Interest-only structuring can change the debt-service line. Eligibility review depends on lender guidelines, credit profile, and property review, so none of this is a promise.
DSCR files in markets like this one typically look like a commuter suburb with strong rents but heavy tax and insurance load. The single-family files cluster right around the benchmark instead of well above it. The stronger files tend to be the ones where the borrower arrives with a lease already in place, an insurance quote in hand, and a plan for what the proceeds do next.
This one’s close to a toss-up. A near-1.0 single-family cash-out can work if your balance is low. But if you hold a larger balance, trimming leverage may beat forcing the 75% ceiling.
Duplexes: Scarce, and the Appraisal Is Where They Bite
The 2-4 unit product has the best coverage math in town and the thinnest evidence base. Redfin showed two multi-family listings at a $320K median listing price, with most homes in the city sitting 81 days. Homes.com’s dated snapshot listed four between $299,000 and $340,000 (Homes.com). Monthly, Redfin counted about six multi-family units for sale, against 34 home sales in the past month.
One listed two-unit building rented its units at $1,475 and $1,375, under a mile from the train station (Realmo). That’s one listing, not a market average, but it shows the mechanism: two smaller rents can out-earn one house, lifting coverage. Local listing copy describes unit mixes of 2BR/2BR and 1BR/2BR within walking distance of the train, downtown dining, and shopping.
Skip the assumption that a duplex appraises like a house, though. Appraisers working with a handful of recent comps can come in below your expectation, and a lower appraised value cuts the cash-out directly. Underwrite each unit on its own comps. Plan for a cushion between your target value and a realistic one.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Crystal Lake, IL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Where the product exists, it’s also scarce enough that price discovery is noisy. That cuts both ways.
Demand Anchors Behind the Rents
Crystal Lake’s rental demand rests on commuters, healthcare, and a community college. Not on one dominant employer. Data USA counts 22.2k employed residents, led by manufacturing (2,880), health care and social assistance (2,742), and retail (2,369), with employment up 2.35% year over year (Data USA). Those are counts of residents by industry, not jobs inside city limits. Median household income is $104,586.
The city sits about an hour northwest of Chicago, with two Metra stations on the Union Pacific Northwest Line (City of Crystal Lake). Most trains on that line terminate here, per Wikipedia. That makes Crystal Lake the outer-edge one-seat ride rather than a mid-line stop, and it’s the strongest hook for commuter tenants. Average commute runs 29.3 minutes. Rentals near either station, particularly downtown, are the commuter play.
Healthcare adds a steady mid-income tenant pool. Northwestern Medicine absorbed Centegra Health System in 2018. Northwestern Medicine McHenry Hospital is a 143-bed teaching hospital with 600+ physicians, and the local Crystal Lake Medical Arts site is a department of it. The hospitals themselves sit in McHenry, Huntley, and Woodstock, not Crystal Lake. That’s a nuance worth pricing: nurses and technicians choose Crystal Lake for the commute and the lifestyle, not because the hospital is next door.
McHenry County College adds a smaller layer. U.S. News lists 7,814 students, and a recent spring term grew by 670 students per Shaw Local. It’s a commuter college, so it nudges demand along U.S. 14 rather than creating a dorm-style market.
The Supply Wave Near Downtown (What’s the Catch?)
The catch is new rental supply, and it lands right where small-rental coverage looks best. Named projects in the research include The Enclave downtown with 99 units a short walk from the station, Water’s Edge with 240 apartments and 20 townhomes (Bisnow, sponsored content), and a developer’s 93-unit apartment complex (Shaw Local). That’s more than 400 units across three named projects, against only about 3,300 renter households citywide. Some may not be built or delivered, and no sourced absorption or vacancy figure exists.
Newer amenity-heavy buildings compete with older small rentals for the same tenants. The likely effect is concessions or slower rent growth. That’s an inference, not a measured result. Underwrite with a conservative rent and a vacancy cushion before you size a cash-out against downtown rents, and treat the appraiser’s rent comps as a ceiling rather than a floor. Investors should also confirm current local rental rules, taxes, and insurance with qualified local professionals.
Redeploying the Proceeds
The point of the refinance is the next asset, and in Crystal Lake that next asset has to clear its own coverage test. Proceeds from a cash-out typically fund the 20-25% down payment on a purchase. For owners comparing financing routes, Lendmire’s guide to weighing conventional against DSCR financing on investor loans covers the tradeoffs, and DSCR cash-out refi mechanics covers how proceeds are sized. For loan options statewide, see Lendmire’s Illinois DSCR loan programs.
Pull the next acquisition from the same pockets that support the current one. A second three-bedroom near downtown or a Metra stop, bought at a price that clears its own number, is a cleaner use of capital than a stretch buy chasing coverage the rents don’t support. Reach Lendmire at 828-256-2183 or request a quote once you know the target.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Crystal Lake?
The property’s rent has to cover its full monthly obligation (principal, interest, taxes, and insurance) at a 1.00 benchmark or better, subject to lender guidelines. You also need about six months on title, credit in the 620-and-up tiers, and about six months of reserves. In Crystal Lake, a three-bedroom near downtown or the Metra tends to sit right around the benchmark, while a duplex clears with more room.
What are the requirements for an investment property loan in Crystal Lake, Illinois?
Typical requirements are a credit score at or above 620, a coverage ratio at or above 1.00, reserves of about six months, and a 75% LTV ceiling on cash-out. Loan amounts run up to $3,000,000 on standard programs. Manufactured homes, log homes, and barndominiums fall outside these programs. All terms are subject to lender guidelines and property review.
Will a duplex near the Metra station support a bigger cash-out?
Often the coverage is stronger, but the appraisal is the risk. Two smaller rents can out-earn one house, which lifts the ratio. But with only a handful of multi-family listings at a time, appraisers may lean on sparse or older comps, and a lower appraised value cuts the available cash directly. Build a cushion into your expected value.
How long do I need to own a Crystal Lake rental before cashing out?
About six months of ownership, measured from title recording, is the typical seasoning guideline. The 75% LTV ceiling then determines how much of the appraised value can come out. Strong recent appreciation, like downtown’s 9.9% year-over-year gain, can make that six-month mark more productive than usual. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
About Lendmire
A non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR financing for real estate investors in 41 markets — 40 states plus Washington, D.C. Because deals are underwritten primarily on property cash flow rather than personal income documentation, the structure suits self-employed buyers and entity-owned portfolios. Lendmire places loans through wholesale investor lenders; it is not a direct lender. Lendmire is recognized as a 2026 Scotsman Guide Top Workplace and a 2025 Scotsman Guide Top Mortgage Workplace.
The asymmetric opportunity in Crystal Lake sits in older two-unit and workforce three-bedroom stock within walking distance of the downtown Metra station. That product is priced below the citywide median yet appreciating faster, and it rents to commuters who have few alternatives at the outer end of the line.
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Illinois
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.