
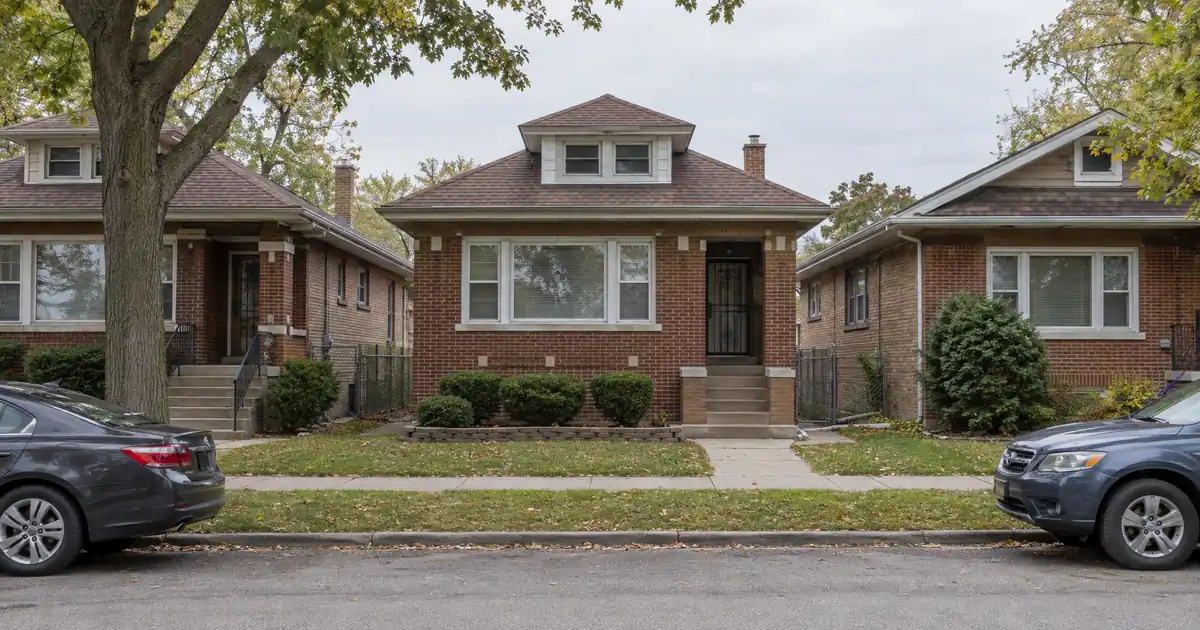
If you own a rental in Calumet City that has climbed in value since the pandemic, here’s what most brokers won’t say: the rent roll won’t set your cash-out number. The appraisal will. Single-family prices in the Calumet City and Harvey submarket rose 85.8% from early in the pandemic through mid-decade, according to DePaul’s Institute for Housing Studies. Current value data points the other way. That gap between what you think the building is worth and what a lender’s appraiser will support is where these files win or lose.
DSCR Cash-Out Calculator
Run the cash-out numbers in Calumet City, IL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A cash-out refinance on a Calumet City, Illinois investment property is underwritten primarily on the rental income the property produces measured against its full monthly obligation, including taxes and insurance, with proceeds limited by appraised value, a ceiling of up to 75% LTV, and roughly six months of seasoning from title recording. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
- Redfin’s multi-family median listing price is $255K. Homes.com shows a $174,900 median on a different snapshot. – Average rent runs $1,176 per RentCafe, with about 75% of rentals between $1,001 and $1,500. – Zillow shows values down 2.7% over the past year, so appraisals may come in flat.
- Two-flats clear coverage more easily than single-family rentals at these price points.
Lendmire (NMLS# 2371349) places DSCR investor loans on Calumet City, Illinois properties through wholesale lending channels reaching 41 markets, including D.C. The rest of this piece is about how that works on a file here.
Calumet City Market Snapshot
A quick read on the Calumet City investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $150,256 median value (City-Data) |
| Typical rents | $1,209 median (City-Data) |
| Employment | 9,217 jobs (Redfin Multi-Family (city)) |
| Vacancy | 8.4% rental (Wikipedia: Calumet City) |
The Equity Is Real. The Run-Up Has Stalled.
Many Calumet City owners hold meaningful equity, but the recent direction of values limits how much of it a lender will release. The DePaul index groups Calumet City with Harvey as one submarket. It shows a 12.7% one-year gain through the fourth quarter of 2024. Zillow now puts the average home value at $156,808, down 2.7% year over year, with homes reaching pending in about 33 days.
There’s a longer-term wrinkle. In an earlier DePaul release, the same submarket had the smallest long-run gain in Cook County: 100.1%, against 125.1% for the county overall. So this is a market that jumped hard, then flattened, and has lagged the county over the long haul.
Two conclusions follow for a cash-out file:
- Underwrite the refinance on rent coverage, not on expected appreciation.
- Expect the appraisal to lean on recent closed sales, not list prices or the number you paid.
City-Data puts the median house or condo value at $150,256. Coldwell Banker’s undated county comparison suggests that’s roughly half the Cook County median. The price gap against the county is why investors look here at all. It also means smaller loan balances, which matters later.
Why Two-Flats Carry the Math
Multi-unit properties clear coverage at Calumet City prices more easily than single-family rentals, because rent roughly doubles while price does not. Apartments.com’s bedroom-level data shows 2BR units at $1,157 and 3BR from $1,246. RentCafe has 2BR at $1,260. A three-bedroom house rents for about what one two-bedroom unit in a duplex does. Put two 2BR units in one building and gross rent lands around $2,300 to $2,500, against a price that isn’t twice the house.
Run the numbers on two modeled cases. These are assumptions, not sourced market data:
- The two-flat. Assume a $255K value (the Redfin median listing figure, not an appraisal), 75% LTV, and two 2BR units at $1,150 to $1,250 each. Rent divided by full PITIA, including taxes and insurance, lands around 1.3x.
- The single-family rental. Assume a $156,808 value (the Zillow average), 75% LTV, and rent near $1,209, the City-Data median gross rent. Including taxes and insurance, coverage is around 1.1x. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Both clear the standard 1.00x benchmark, but the single-family case has much less cushion. A softer appraisal, a vacancy month, or a rent that comes in under the schedule pushes that file toward the line. Most DSCR programs build around 1.00x because rent covers the payment there. Some lenders review lower ratios with tighter leverage and credit terms. Exact eligibility depends on lender guidelines, credit profile, reserves, and property review.
One inference worth stating as an inference: a Krembo Group guide to the south suburbs describes two-flats and three-flats as common in Calumet City, Dolton, and Harvey. The guide calls yield potential there attractive but notes that management demands come with it. That’s a broker’s view, not data. It fits the stock pattern, though. RentCafe reports 63% of rental units are in buildings under 50 units and 23% are single-family rentals. Small-building DSCR products are the natural fit.
Separate utility meters help. One Homes.com duplex listing describes each unit with its own gas and electric meters. That supports a clean unit-level rent schedule and lowers owner-paid utilities, which gives the lender fewer questions. For details on the program basics, see the guide “What Is a DSCR Loan”.
What the Appraiser Will Actually See
Appraisal is the highest-friction step on a Calumet City cash-out, and the drivers are local. The median year built is 1968 per Point2Homes, and RentCafe puts the average apartment building at about 41 years old. Older stock means condition adjustments, deferred maintenance flags, and sometimes lender repair conditions.
Market-time data also splits by area. Redfin’s city-wide multi-family snapshot shows 15 homes at an 83-day typical market time. Its Town Center page shows 4 multi-family homes at a $188K median listing price and a 178-day typical market time. The long hold time suggests thinner buyer demand there. That is an inference from a four-listing sample, but it tells you appraisers may struggle to find tight comps and may pull from a wider radius.
Here’s how to prepare:
1. Build the comp packet before the appraisal. Closed sales of similar 2-flats and 3-flats in the same part of the city, with condition notes.
2. Document the rent schedule unit by unit. Leases, or a market-rent basis if a unit is vacant.
3. Get the meter configuration and any recent capital work on paper. New roof, boiler, or electrical updates change the condition adjustments.
4. If the value comes in light, request appraisal reconsideration. Attach recent in-neighborhood closed sales and condition support. It’s a routine step, not an emergency move.
Don’t use listing medians as the value target. They run from $174,900 to $255K depending on the snapshot. The spread is wide, and the homes behind those figures aren’t yours.
Seasoning, Reserves, and the Leverage Ceiling
Cash-out leverage tops out at 75% LTV, and the equity you can pull depends on appraised value, rent used for lender review against PITIA, and reserves. Nothing here is a guaranteed cash figure. Illinois can carry a tighter overlay on refinances depending on the program, so the working LTV on a given Calumet City file can land below the ceiling. Plan the proceeds conservatively. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Other parameters to plan around, all subject to lender guidelines:
- Seasoning. About 6 months of ownership, measured from title recording. Files that assume seasoning away, especially on a recent purchase or renovation, get kicked back. The settlement statement documents it.
- Reserves. About 6 months of PITIA, documented with statements. Reserves documentation is where clean files separate from slow ones.
- Credit. Tiers at 620, 660, 680, and 700, with 620 as the floor. Pricing and leverage generally improve as the score rises.
- DSCR. A 1.00 minimum on the standard approach, with rent used for lender review measured against PITIA.
- Loan size. Standard programs go up to $3,000,000. At Calumet City values, many balances are small, and smaller balances route through select lenders in the network. Confirm the lender match early.
The entity side needs its own attention. LLC-titled properties are eligible subject to lender program eligibility, and entity documents (operating agreement, EIN letter, good standing) should be in the file before submission. For the refinance mechanics, see the cash-out refinance details and the broader refinancing options.
Watch the property-size line. A 12-unit brick building near the Indiana border appears in one Homes.com listing excerpt. At five units or more, loans commonly move to commercial or multifamily underwriting, so a small-apartment-building owner shouldn’t assume the 1-4 unit DSCR path applies.
Who Rents Here (and Who Employs Them)
The tenant base is workforce-driven, and the rent schedule is easy to defend because the band is tight. About 44% of households, 6,346 in all, are renter-occupied. Median household income is $56,843. Population is 34,855 per City-Data, a slow decline over the long run.
Two rent numbers conflict. Zumper shows an average of $1,317, down 4% year over year. RentCafe shows $1,176, up 5.9%. Different methods, different direction. Don’t model strong rent growth. Model at market rent and let the lender’s rent schedule decide. The dated 8.4% rental vacancy figure on Wikipedia’s Calumet City page is a 2020-era number, so treat it as background, not a current read. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Demand anchors sit in and around the city rather than concentrated in one employer:
- UChicago Medicine runs Ingalls Memorial in nearby Harvey and an outpatient site in Calumet City. Wikipedia cites about 3,000 employees at the hospital, an older and unverified figure.
- River Oaks Center, a mall with 60+ stores, anchors retail activity.
- Commuter employment sits across the state line, including casino and hospital employers in northwest Indiana.
Healthcare and retail jobs are a steady base for lease renewals. They are not a college-rental or high-income story. Calumet City is not a student market, and the nearby schools shouldn’t be presented as tenant demand drivers.
What the deal desk sees. On files from older, small-building, workforce markets like this one, the common friction point is a rent schedule that doesn’t match the appraiser’s rent estimate. The cleaner files tend to arrive with unit-level leases, a current rent roll, and entity documents already matched to the vesting on title. Files with mismatched names between the LLC and the title commitment add preventable review time. Reserves statements dated within the lender’s window are the other recurring item.
Turning Proceeds Into the Next Deal
Cash-out proceeds are capital for the next acquisition, and Calumet City’s price structure shapes where that capital goes. Some investors recycle the proceeds into another 2-flat in the same city. Others cross the state line, since Calumet City borders Hammond, Indiana, per DePaul’s housing studies portal. That makes it possible to compare Illinois and Indiana pricing within a few miles.
The refinance math shouldn’t assume the next deal is already won. Size the proceeds against your reserve requirement first, then against the down payment needed on the next property. Keep the two buckets separate on paper. A lender reviewing the new acquisition will look at post-refinance reserves, not the cash you had before the cash-out.
DSCR vs. conventional financing
Two common ways to finance an investment property in Calumet City, IL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
For investors weighing this against a conventional route, Lendmire’s comparison of DSCR versus conventional loans covers the differences in more depth. Illinois-specific program detail sits on the Illinois DSCR financing page. To talk through a file, call 828-256-2183.
Frequently Asked Questions
How much equity can I pull from a Calumet City two-flat?
It depends on appraised value, rent used for program review against PITIA, reserves, and the 75% LTV ceiling. Illinois overlays can lower the working LTV on some programs. With listing medians ranging from $174,900 to $255K depending on the snapshot, the appraisal is the number that matters. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Does the flat market for home values hurt a cash-out here?
Yes, in one specific way. Zillow shows values down 2.7% over the past year, so a recent purchase or renovation may appraise flat. That directly limits how much equity a refinance can release. A comp packet and appraisal reconsideration are the standard responses when a value comes in light.
Is a two-flat easier to refinance than a single-family rental in Calumet City?
On coverage, generally yes. Two 2BR units gross about $2,300 to $2,500, nearly double a single 3BR rental, against a price that is not double. In the modeled cases above, the two-flat lands around 1.3x and the single-family rental around 1.1x, both including taxes and insurance. Subject to lender guidelines.
Does a 12-unit building qualify for the same DSCR cash-out?
Usually not on the same path. At five units or more, lenders commonly move the loan to commercial or multifamily underwriting. Confirm the program rules before ordering an appraisal on a larger building.
Do I need to wait after buying before I can cash out?
About 6 months of ownership, measured from title recording, is the typical seasoning period. The settlement statement documents it. Verify current lender requirements at the time of the file.
The Blind Spot
The biggest risk for DSCR-financed investors in Calumet City is a stalled value on small-building stock with an old housing base. Appraisals can come in flat while rents read mixed, and a thin-cushion single-family file leaves little room when either moves. Cook County property taxes also weigh heavily on the coverage ratio, so confirm current local rules, taxes, and insurance with qualified local professionals before sizing a cash-out.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income rather than the borrower’s W-2 history, which suits LLC-titled portfolios and self-employed investors. All scenarios stay subject to eligibility review and program guidelines. Lendmire was recognized by Scotsman Guide as a 2026 Top Workplace and was also named a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. DePaul Institute for Housing Studies, Cook County House Price Index (Q2 2025)
3. Homes.com — Calumet City IL Multi Family Homes for Sale
4. RentCafe
6. $150,256
7. Wikipedia’s Calumet City page
8. DePaul Institute for Housing Studies, Cook County House Price Index (Q4 2024)
9. DePaul Institute for Housing Studies, Cook County House Price Index (Q2 2024)
10. Apartments.com — Rent Market Trends Calumet City IL
11. krembogroup.com — South Suburban Chicago Investment Property Guide 2026
12. RentCafe — Apartments for Rent Calumet City IL
13. Point2Homes
14. Redfin — Calumet City Town Center Multi Family Homes for Sale
15. Zumper shows an average of $1,317, down 4% year over year
17. Wikipedia cites about 3,000 employees at the hospital
18. DePaul Institute for Housing Studies, Calumet City profile
19. recognized by Scotsman Guide as a 2026 Top Workplace
20. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Illinois
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.