
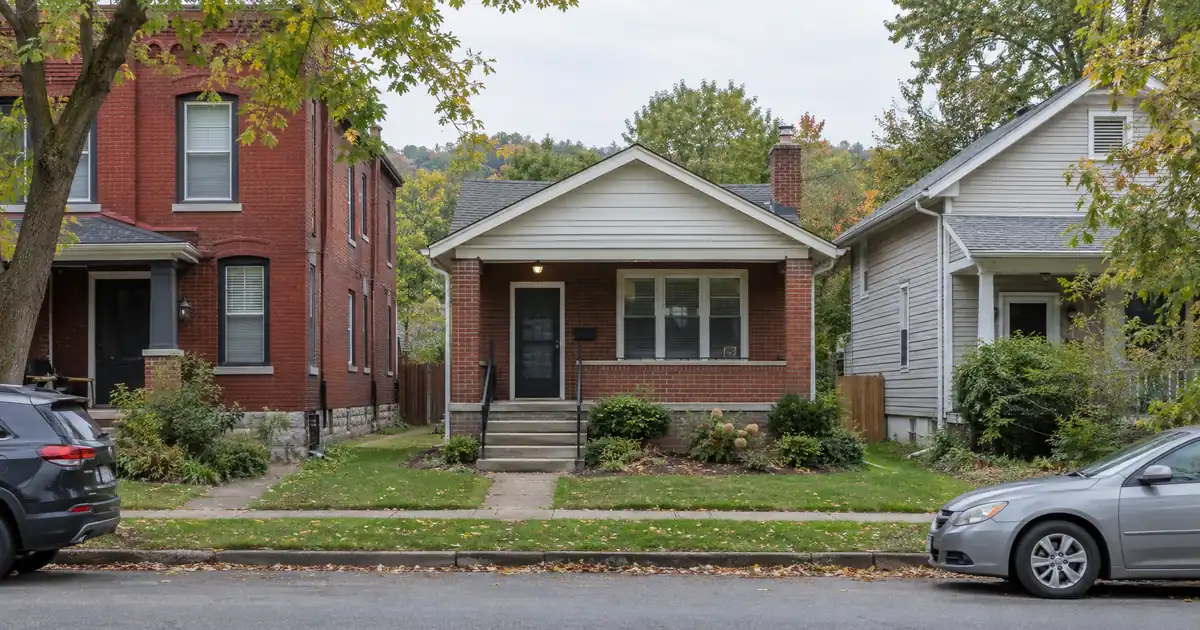
A DSCR cash out refinance in Columbia, Missouri, works very differently for two investors who look similar on paper. One owns a single-family rental priced near the citywide median, which Redfin puts at $339K, against a median rent of $1,395 per Zumper. The other owns an older-core duplex where two rent rolls stack against a single value. On coverage math, the duplex owner has the stronger file. The single-family owner often runs into the coverage test before the loan-to-value cap comes into play.
TL;DR: A cash-out refinance on a Columbia, Missouri rental fits the investor holding older-core small multifamily or lower-priced workforce housing, where stacked rents can clear the coverage threshold, and it is underwritten primarily on the property’s rental income measured against its full monthly obligation, subject to about six months of seasoning and a 75 percent LTV ceiling.
DSCR Cash-Out Calculator
Run the cash-out numbers in Columbia, MO
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Single-family at the citywide median price models well below 1.00 coverage once taxes and insurance are counted.
- Older-core duplexes near Mizzou stack two rent rolls against one value.
- Cash-out tops out at 75 percent LTV, with seasoning of about six months from title recording.
- Refinance with executed academic-year leases in place, not during summer turnover.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that arranges investor loans across 40 states plus Washington, D.C., 41 markets total. This piece covers only the equity-extraction side: the investor already owns the property and wants to know how much capital it can release and where that capital should go next. Purchase mechanics are a different conversation.
Columbia Market Snapshot
A quick read on the Columbia investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $230,000 median price (Homes.com) |
| Recent appreciation | +2.71% home value (Ark7) |
| Vacancy | 5.2% (CapRateCity) |
Why Coverage Binds Before Leverage Does
Most Columbia single-family rentals will hit the coverage test before the leverage cap. CapRateCity models a rent-to-price ratio near 0.45 percent for the city, well below the 1 percent rule of thumb, and the Redfin and Zumper figures above imply roughly 0.41 percent. Treat these as directional, since aggregator models and listing medians use different methods.
Run the numbers on a median-priced house this way. These are modeled assumptions, not sourced market data. Take a $339K value at 75 percent LTV with a rent near $1,395. Divide that rent by a full monthly obligation of principal, interest, taxes and insurance, and coverage lands somewhere in the 0.6 to 0.7 range. That is well under the 1.00 benchmark most standard DSCR programs are built around.
Sub-1.00 doesn’t mean dead. Some lenders review sub-1.00 programs, interest-only structures, or lower-leverage requests, but each usually brings tighter proceeds, stronger credit expectations or different pricing. Whether a file qualifies depends on lender guidelines, credit approval and property review. The honest question is whether the investor should use those structures or accept that this particular house isn’t the right cash-out candidate.
Appreciation complicates the picture. Redfin shows the median sale price up only 0.5 percent year over year, while Ark7 reports five-year appreciation of about 54.90 percent and current home-value growth near 2.71 percent. So equity built up over the hold, but current yield is thin. Owners are sitting on real equity and modest cash flow. A cash-out is only useful if the property’s income can carry a bigger balance.
A Demand Base With More Than One Leg
Columbia’s rental demand doesn’t depend on a single employer. The Columbia Regional Economic Development boone county employer list shows the University of Missouri at 9,998 employees, MU Health Care at 8,103, Veterans United Home Loans at 2,847, the Truman Veterans’ Hospital at 2,074 and Boone Health at 1,400. That mix of university, academic medicine, VA care and a national mortgage servicer sits inside one compact commute shed. It is unusual among mid-Missouri cities, though “unique” would overstate it.
The student layer matters most for the older core. The Columbia Missourian reports a projected Mizzou total of 31,650 students, and a regional college says 73 percent of students live off campus. The University of Missouri counts 1,849 graduate and professional students among its 9,138 newcomers and reports 91 percent first-year retention. Students who stay and graduate students rent for several years. RentCafe puts 51 percent of households in renter-occupied units.
Enrollment is growing modestly. That supports a stable-demand story for a lender or appraiser, but it doesn’t support a rent-growth argument. Keep those two things separate in your own underwriting.
Where Stacked Rents Beat the Median
The strongest cash-out candidates are older-core duplexes and small multifamily in Benton-Stephens, East Campus, North Central and the Arcade District. Homes.com reports a $175,000 12-month median sale price in Benton-Stephens, up 8 percent. It also lists a separate listing-based median of $230,000, and the two figures conflict, so use the labeled one. Housing stock there mostly dates from 1910 to 1950, and the same page shows homes selling after about three days on the market. A duplex in that pocket carries two 3- or 4-bedroom units against a price per door well under the citywide median.
Rent per side wasn’t extractable from the listings, and no source reports duplex or fourplex rent-to-value for Columbia. So here is a modeled example, with rent as an assumption. Picture a duplex appraised at $320,000, financed at 75 percent LTV, with combined rent modeled at $2,700 across two units. Counting principal, interest, taxes and insurance, coverage models around 1.3x, rounded down. Compare that to the median single-family house in the 0.6 to 0.7 range. Same city, same tenant pool, very different file.
| Factor | Median single-family | Older-core duplex |
|---|---|---|
| Rent rolls per value | One | Two stacked |
| Modeled coverage | Well under 1.00 | Above 1.00 (modeled) |
| Binding constraint | Coverage | LTV cap |
| Seasonal exposure | Moderate | Higher (student turnover) |
East Campus is the other obvious pocket. Rent.com shows one-bedroom rents around $920 there, against about $1,526 downtown and in the North Village. Downtown’s newer and lofted product prices differently, and purpose-built apartments compete with small-building owners in that district, so the East Campus and North Central duplex is the more relevant comp for most older-core owners.
Workforce Pockets and the Grindstone Question
Northland-Parker, Hawthorne and Colonial Gardens are entry-priced. Rent.com shows one-bedroom rents near $760 in Hawthorne and $925 in Northland-Parker, and a neighborhood guide from 10 Federal Storage says single-family homes there are often under $200,000. The rent-to-value picture may be better than the citywide 0.4 to 0.45 percent, but house-level rent data is thin, so run each property on its own lease.
Grindstone-Rock Quarry is the mixed case. Homes.com shows a $208,000 median sale price there, up 22 percent over 12 months, plus a side-by-side duplex listed with both sides on month-to-month leases. That’s a good illustration of a documentation problem, not a rent problem. The rent may be fine, but a lender reviewing a month-to-month rent roll may want a lease, a market rent schedule or both.
Two areas are worth skipping for cash-out purposes. Old Southwest sits around $430K, and the newer south and southwest subdivisions run $575K to $800K in the highest-end areas. Both are owner-occupant markets. Rent-to-value is weak, so a cash-out there depends on coverage the rents can’t support.
What the File Actually Looks Like
This section is plumbing. Most Columbia cash-out files come down to four items: the lease documents, the timing, seasoning, and the reserves. Miss one and the file stalls in lender review.
DSCR files in markets like this one typically look like a stack of rent-roll documentation before they look like anything else. Lenders want executed leases or a market rent schedule that matches what the appraiser sees. Student-heavy submarkets add a wrinkle, because rent rolls in the campus core can look different depending on the month a review happens. Investors who refinance mid-summer often find turnover, vacancy or concessions in the rent roll that wasn’t there in spring. In-place, fully executed academic-year leases give the cleaner file.
The calendar helps if you plan for it. Apartment List describes seasonal turnover in East Campus and summer discounts. A vendor page from RentCollegePads says house pre-leasing begins in mid-October and November, mainly in East Campus and North Central. That is a marketing page with no absorption data, so treat it qualitatively. It also says the past decade saw a rental boom near campus with many downtown options. That is a risk flag, not a measured oversupply finding, but it argues for conservative concessions and vacancy in any small-building rent assumption.
Then the program parameters, which are typical guidelines subject to lender overlays:
- Seasoning: about six months of ownership, measured from title recording.
- Leverage: a 75 percent LTV ceiling on cash-out, lower than the purchase cap.
- Credit: tiers commonly improve at 660, 680 and 700, with terms that vary by scenario.
- Reserves: about six months of PITIA on most files.
- Loan size: up to $3,000,000 on standard programs, with smaller balances routed through select lenders in the network. Most Columbia balances fall in that smaller category.
If the property is titled in an LLC, that is generally workable, subject to lender program eligibility. Anyone who wants the mechanics behind coverage can read the guide “What Is a DSCR Loan”. The cash-out refinance details and investor refinance options pages cover the rest.
Where Should the Proceeds Go?
Proceeds should go where coverage still works at current pricing. A cash-out from an older-core duplex used to buy another older-core duplex keeps the math straightforward. Equity pulled from a Columbia property and pushed into an out-of-state market where the numbers don’t pencil is a different decision, and it deserves a stress test first.
There is also a concentration question. Reinvesting in the East Campus and North Central pocket doubles down on one tenant pool tied to one university. This one’s a genuine toss-up. Recycling equity into the strongest submarket you know is a defensible strategy, but if Mizzou enrollment softens again, both properties feel it at the same time. An investor could reasonably balance a campus-core duplex with a workforce property in Northland-Parker or a hospital-adjacent rental.
Conventional financing is the flip point for some owners. A W-2 borrower with one or two rentals and clean personal income may find a conventional cash-out or a home equity line carries less friction, and it may be the only workable path when a house sits well below 1.00 on coverage. DSCR becomes more practical for entity-owned portfolios, self-employed investors, or anyone whose personal returns don’t cleanly support the rental income. The comparison between DSCR and conventional financing comes down to these trade-offs. The break-even often arrives around the third financed property.
Investors can reach Lendmire at 828-256-2183 or request a scenario quote to see how a specific Columbia rent roll runs. Program specifics for the state live on the Missouri DSCR financing page. Investors should also verify current local rental rules, taxes and insurance with qualified local professionals.
Frequently Asked Questions
How much equity can I pull from a Columbia single-family rental?
It depends on rent used for lender review, the full monthly obligation, reserves and the 75 percent LTV ceiling, and it isn’t a guaranteed figure. At the citywide median price, coverage tends to bind first, so proceeds may be limited well before the LTV cap. Lower-priced workforce houses often pencil better than newer south-side product.
DSCR vs. conventional financing
Two common ways to finance an investment property in Columbia, MO. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Does the academic calendar affect when I should refinance a campus rental?
Yes. The cleanest file is one with executed academic-year leases in place. A review during summer turnover can show vacancy or concessions that understate normal rent. Timing the refinance for after lease-up gives the lender a full rent roll to read.
Can I refinance a Benton-Stephens or East Campus duplex soon after buying it?
Typically not immediately. Seasoning of about six months from title recording is a common guideline, and the exact rule varies by lender, property type and unit count. Multi-unit and lower-coverage files often face tighter limits, so confirm before planning around a date.
Are month-to-month leases a problem on a Grindstone duplex?
They can be. A lender may want lease terms, a market rent schedule or both before counting the income. Converting to written leases before applying usually makes the rent roll easier to document.
Is Columbia too dependent on Mizzou to support a cash-out?
The campus layer is large, but the demand base isn’t single-legged. MU Health Care, the Truman VA hospital, Boone Health and Veterans United together employ well over 14,000 people according to the Columbia Regional Economic Development employer list. Still, campus-core small multifamily carries more seasonal and enrollment exposure than a workforce house.
Where the Mismatch Sits
The asymmetric opportunity in Columbia is the older-core duplex in Benton-Stephens and East Campus, where price per door stays well under the citywide median while two large-bedroom rent rolls stack against a single value. It’s underpriced against its coverage fundamentals, and a seasoned owner holding one of those with fully executed academic-year leases is the investor whose equity most likely converts into a usable cash-out.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income, not the borrower’s W-2 history — a practical fit for LLC-titled portfolios and self-employed investors. All scenarios remain subject to lender review and program guidelines. Lendmire has earned two consecutive Scotsman Guide Top Mortgage Workplace recognitions (2025, 2026).
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Columbia housing market
2. Zumper, Columbia rent research
3. Homes.com
4. Ark7
5. CapRateCity
6. Columbia Regional Economic Development, Boone County largest employers
7. Columbia Missourian, Mizzou fall enrollment
8. University of Missouri, new student cohort release
9. RentCafe, Columbia average rent
10. Rent.com
11. Apartment List
12. RentCollegePads
13. recognized by Scotsman Guide as a 2026 Top Workplace
14. Scotsman Guide 2025 Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Independence, Missouri: Equity Math for Older Rentals · DSCR Cash Out Refinance in St Joseph, Missouri: The 2026 DSCR Refinance Guide to Museum Hill · DSCR Cash Out Refinance in Raytown, Missouri: The 2026 DSCR Financing Guide to Raytown Road
Guides: Investment Property Cash-Out Refinance in Columbia, MO · Investment Property Cash-Out Refinance in Missouri
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.