
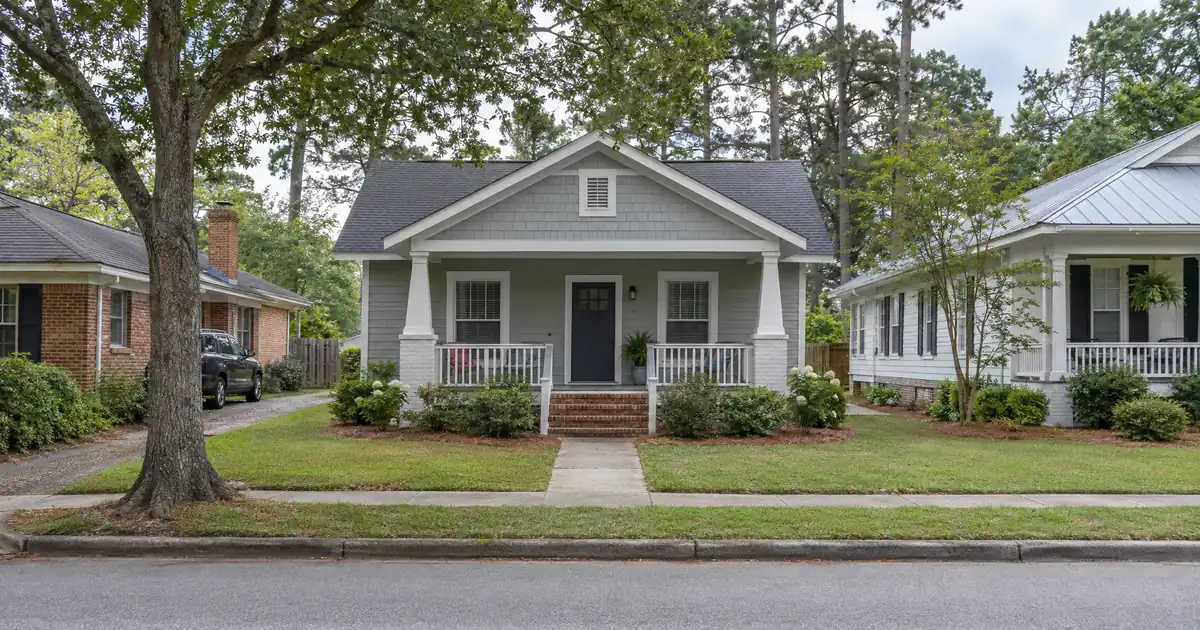
Fairhope is a market where the equity is real and the rent can’t carry it. Most investors assume a bayfront Eastern Shore city with a record of rising values makes cash-out easy. In practice the limit here is rarely equity. It is coverage: how much rent the property produces against its full monthly obligation once a new, larger loan sits on it.
The Quick Read: A cash-out refinance on a rental in Fairhope, Alabama is underwritten primarily on the property’s rental income measured against its full monthly obligation, after roughly six months of title seasoning, an appraisal built on sold comparables, and a leverage ceiling that caps proceeds before coverage trims them further.
DSCR Cash-Out Calculator
Run the cash-out numbers in Fairhope, AL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Zillow puts the typical home value at $461,041, so coverage, not equity, is the binding constraint.
- Modeled coverage at the 75 percent ceiling lands below 1.00 on median rents; lower leverage closes much of the gap.
- Only 18 percent of households rent, so a single vacancy moves the file.
- Stacked units and 3-bedroom workforce rentals are the cleanest collateral.
- Single Tax Colony leasehold parcels need extra title diligence before anyone orders an appraisal.
Fairhope Market Snapshot
A quick read on the Fairhope investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| University enrollment | Over 9,000 students (Coastal Alabama Community) |
| Population | 24,190 population (Alabama-Demographics) |
| Employment | 1,116 employees (Business Alabama, Baldwin) |
Why Equity Isn’t the Constraint Here
Fairhope’s problem is the ratio of rent to value, not a shortage of value. Zillow’s home value index sits at $461,041, up 3.8 percent over the past year. Zumper’s median rent across all property types is $2,090, up 11 percent year over year. Divide one by the other and monthly rent runs about 0.45 percent of value. (That ratio is Lendmire Research’s own arithmetic, not a sourced figure.)
Sources disagree on both sides of that ratio, and the disagreement matters. Data USA, using Census-derived data, puts median property value at $430,900. Movoto reports a median sale price of $575,000 with homes sitting around 90 days on the market. On rent, RentCafe’s average apartment figure is $1,558, but that comes from Yardi Matrix data on buildings with 50 or more units, so it describes large complexes rather than single-family rentals. This article uses the Zillow value and the Zumper median as its working pair and treats everything else as a range.
The population behind those numbers is about 24,190 residents with a median household income of $94,274. That is a high-income town where ownership dominates. Buyers there are paying for the lifestyle, and rents haven’t priced up to match.
Walking the Math, Step by Step
Run the numbers on a typical 3-bedroom house. These are modeled assumptions, not market facts: value near the Zillow figure, rent at the Zumper median of $2,090, a 30-year amortizing structure, and full taxes and insurance at Alabama-average loads. Debt coverage is monthly rent divided by principal, interest, taxes, insurance, and any HOA dues. The result at the 75 percent ceiling lands in the high 0.7s, below the 1.00 baseline that most standard programs are built around.
That doesn’t end the conversation. It changes the structure. Pull leverage down to roughly 60 percent and the same rent produces coverage in the mid-0.9s, still modeled, still including taxes and insurance, and rounded down on purpose. Each step down in leverage buys coverage at the cost of proceeds.
Where a file lands under 1.00, a few paths exist that a lender may review: a lower-leverage cash-out, a program that accepts sub-1.00 coverage with compensating factors, or an interest-only structure. None is a promise. Eligibility turns on the lender’s guidelines, credit profile, reserves, and property review. For the mechanics behind the ratio, see the guide “What Is a DSCR Loan”.
Stacked units change the math more than any other lever. A duplex or fourplex puts several rents against one tax bill, one insurance policy, and one loan. That is why small multifamily is the structural answer to Fairhope’s thin single-family coverage. Supply is the catch. Homes.com showed only nine multi-family listings when this research was pulled, and it counts everything from duplexes to apartment complexes in that bucket. Comps will be scarce, so a rent roll and a handful of sold properties will matter more than any market average.
Which is better, a cash-out on a single-family house at reduced leverage or a sale of the house to buy a small multifamily? That one is a toss-up. The house keeps the equity working at lower proceeds, and the multifamily trades Fairhope’s premium pricing for better coverage but a thinner pool of comparables.
What Appreciation Will and Won’t Do
Don’t underwrite a Fairhope cash-out on a forecast. Price direction is mixed depending on who is measuring. Zillow shows values up 3.8 percent, while Homes.com shows a 12-month median sale price of $471,576, down 3 percent from the prior 12 months. Movoto shows list price per square foot down 4 percent year over year. Flat to modest is the fair read.
Seasoning compounds the point. Most programs look for about six months of ownership measured from title recording before a cash-out, and the appraisal that follows will lean on sold comparables. Homes in Fairhope take roughly 69 to 90 days to sell depending on the source, and asking prices run well ahead of what closes. A list-price anchor will overstate value; a sold-comp anchor won’t. The proceeds you plan around should come from the second number.
Equity available is therefore the lesser of two things: 75 percent of appraised value less the existing payoff, or whatever balance the rent can cover at full monthly obligation. In Fairhope the second limit usually bites first. Plan around it, not around the headline ceiling. The DSCR cash-out refi mechanics page walks through the seasoning clock and how proceeds are sized.
Who Actually Rents in Fairhope?
Demand starts with employment, and Fairhope’s is healthcare-heavy. Data USA shows Health Care and Social Assistance as the largest resident industry with 2,192 people, followed by Retail Trade at 1,189 and Construction at 976. Those counts reflect where residents live, not where they work.
Thomas Hospital, part of Infirmary Health, is the clearest local anchor. Business Alabama reported 189 beds and 1,116 employees, though other sources list fewer beds and staff, so “roughly 1,000 employees” is the safer description. Baldwin County Public Schools is the area’s largest employer at over 4,000 employees, a county-wide figure. Nurses and clinicians on 12-month leases are a plausible tenant segment, though no source in this review quantifies it.
The commuter story widens the pool. Many Fairhope residents work in Mobile, and the region’s anchors include Infirmary Health, the University of South Alabama, Austal USA, and Airbus Alabama, per The Kirkland Company. Closer in, Collins Aerospace in Foley employed 1,160 workers by Business Alabama’s count, though that figure is dated. Pipeline projects add depth: Baldwin Alliance says the Novelis facility at the South Alabama Mega Site will create about 1,000 jobs, and ALDI’s Loxley distribution center brought 200.
Here’s the catch. RentCafe reports only 1,710 renter households, 18 percent of the total. A renter pool that small means one vacancy is a larger share of income than in a deep market. For single-family underwriting, the 3-bedroom band is the realistic benchmark: RentCafe shows $1,817 for apartments, Apartments.com shows $1,946, and house rentals run higher. Use the lower end for conservative coverage math. Point2Homes counts 650 rentals with 3-bedrooms at 39 percent, the largest share.
Submarkets: Where the Collateral Sits
No reliable per-neighborhood price or rent source exists for Fairhope. Zumper states it doesn’t have enough active inventory to publish neighborhood rents. So the profiles below are qualitative, organized by tenant base.
Downtown, the bayfront, and the French Quarter. Homes.com describes waterside homes, a town center, and a hidden French Quarter. Older housing stock sits near downtown and Mobile Bay, per a local agent. Tenants here are professionals and workers tied to the town’s visitor economy. Values skew high, so coverage is hardest to reach in this core.
The hospital corridor. Thomas Hospital sits along Morphy Avenue, and the surrounding blocks draw healthcare workers. It is the strongest employment story in town, but price and rent data for the area aren’t published. Collateral near the hospital is the first place to look for 3-bedroom rentals with stable demand.
The airport and aviation cluster. Segers Aerospace operates at the Fairhope Airport, and a training academy there brings together Coastal Alabama Community College, Baldwin County schools, and the airport authority, per Business Alabama. Demand is technicians and trainees. It is a small niche and unquantified.
The college area. Coastal Alabama Community College has a Fairhope campus and reports combined enrollment of over 9,000 students across all locations, a college-wide number rather than a Fairhope-only one. The campus is adding a nursing cohort, which feeds the same healthcare demand described above.
Newer subdivisions in 36532. Zillow puts the ZIP’s typical value at $452,701, up 4.3 percent. A local agent notes new subdivisions within a few miles of downtown. Owner-occupants dominate these streets, which means fewer comparable rentals for an appraiser to use.
The Colony Question
Some Fairhope parcels aren’t fee-simple. The Fairhope Single Tax Corporation, a land-lease colony founded in the late 1800s, owns roughly a quarter of the town’s land and leases it to residents, per Progress.org and WKRG. Great Retirement Spots calls it one of two such colonies in the country, the other in Arden, Delaware.
For a refinance, the question is the collateral. A local agent notes that leasehold properties may require special attention from lenders and title companies. This research did not verify any lender’s specific leasehold policy, so there is no basis here to say a program will or won’t take colony land. Treat it as a diligence item: confirm whether the parcel is leasehold or fee-simple before the file goes anywhere, because it can change which programs are even a fit.
Where the Proceeds Go
An investor pulling cash from a Fairhope rental usually wants to redeploy it, and the placement decision matters as much as the extraction.
The deal desk at Lendmire sees a consistent pattern on files from high-value, thin-rental markets like this one. The cleaner files tend to have a fully executed lease at or near market rent, a fresh insurance quote in hand before submission, and a conservative leverage request that fits the coverage number rather than the equity number. The common friction point is a file built around the maximum proceeds that then has to be cut back once full taxes and insurance hit the ratio.
If the proceeds fund the next acquisition, the cleaner use in this market is a higher-coverage property elsewhere, since Fairhope’s own rent-to-value ratio makes it a poor place to stack leverage. Lendmire’s Alabama DSCR platform covers other Alabama submarkets where rents run closer to value. For refinance structure options, the rate-and-term and cash-out refi details are on the site. The tradeoffs between conventional and DSCR financing show how the conventional alternatives compare.
Investors should verify current local rental rules, taxes, and insurance with qualified local professionals. Gulf Coast hurricane exposure makes the insurance conversation especially worth having before a file is submitted.
Three Numbers to Watch
Track these over the next quarter to judge whether Fairhope’s cash-out math is improving.
1. Sold-versus-list gap. If sold prices close in on asking prices, appraisals will support more value. Watch the Movoto and Homes.com median sale prices against the Zillow index.
2. Rent growth versus value growth. Zumper’s 11 percent annual rent gain is the number to watch. If rents keep climbing while values stay flat, coverage improves without anyone touching the loan.
3. Hospital and industrial hiring. The Novelis build-out and any Thomas Hospital expansion drive tenant demand. More jobs within commuting range tighten a renter pool that is only 18 percent of households.
Fairhope won’t reward leverage for its own sake. The investors who do well here will be the ones whose cash-out files fit the rent rather than the other way around.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Fairhope, AL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Fairhope, Alabama?
Qualification centers on the property’s rent measured against its full monthly obligation, with a typical 1.00 baseline, a credit floor around 620, and about six months of reserves. In Fairhope, coverage is usually the limiting factor because rents run low relative to values. Final eligibility depends on lender guidelines, credit, reserves, and property review.
What are the requirements for an investment property cash-out refinance in Fairhope, Alabama?
Programs typically want about six months of ownership from title recording, a loan-to-value ceiling of 75 percent on cash-out, and an appraisal supported by sold comparables. Loan amounts run up to $3,000,000 on standard programs. Smaller balances route through select lenders in the network. Call 828-256-2183 to talk through a specific property.
How do DSCR lenders review rental income instead of tax-return income in Alabama?
Lendmire arranges DSCR investor loans. The file is generally reviewed around the property’s rent against its full obligation instead of personal income documents, subject to lender guidelines. That structure suits self-employed borrowers and LLC-held portfolios, depending on program requirements.
Does a Single Tax Colony leasehold affect a Fairhope cash-out refinance?
It can, because leasehold parcels may call for added attention from lenders and title companies, and this research found no lender-specific leasehold policy. Confirm whether a parcel is leasehold or fee-simple before ordering an appraisal, since it can change which programs apply.
How much equity can an investor pull from a Fairhope rental?
It is the lesser of 75 percent of appraised value less the existing payoff and whatever the rent can cover at full monthly obligation. In Fairhope the coverage test usually binds first, so proceeds often land below the leverage ceiling. It isn’t a guaranteed figure, and a lower-leverage request can clear coverage more cleanly.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a non-QM mortgage broker (NMLS# 2371349), Lendmire facilitates DSCR investor loans across 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income instead of personal income documentation, subject to lender guidelines, which serves LLC-structured portfolios and self-employed borrowers who don’t fit conventional boxes. Lendmire was recognized by Scotsman Guide in 2025 and named a top-ranked workplace in 2026.
For broader investor-financing rules and property-type coverage across the state, see Alabama DSCR loans.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow, Fairhope home values
2. RentCafe, Fairhope average rent
3. Coastal Alabama Community College
4. Alabama-Demographics, Fairhope
5. Business Alabama, Baldwin County health care
6. Zumper, Fairhope rent research
8. $575,000
9. Homes.com — Fairhope AL Multi Family Homes for Sale
11. Infirmary Health
15. Baldwin Alliance, industry
16. Apartments.com — Fairhope AL 3 Bedrooms
17. Point2Homes — Average Rent Fairhope
18. Business Alabama
19. $452,701
20. Progress.org, Fairhope Single Tax Corporation
21. WKRG
22. recognized by Scotsman Guide in 2025
23. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Fairhope, AL · Investment Property Cash-Out Refinance in Alabama
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.