
The Quick Read: A fourplex cash-out refinance replaces your current loan with a larger one and pays you the difference, and the loan size is set by whichever of two tests is tighter: how much equity the building has, or how well the four units’ combined rent covers the new payment. Both tests must pass on the same file.
- Cash-out on an investment property tops out around 75% LTV (loan-to-value, the loan as a share of appraised value) across most of the network.
- Lenders expect about 6 months of ownership, counted from title recording, before they size on appraised value.
- Coverage of 1.00 is where select programs start. Stronger ratios open better pricing and leverage.
- Credit floors vary by scenario in parts of the network. Most programs want about 660, and 700+ unlocks the strongest tiers.
- Reserves are commonly about 6 months of PITIA (principal, interest, taxes, insurance, and association dues), stepping up to about 9 months above $1,500,000.
How a Multi Family Investment Property Cash-Out Refinance Works on a Fourplex
The new loan pays off the old one, then the leftover cash goes to you. That leftover is not your full equity. Payoff, junior liens, closing costs, and any funded reserves all come out first.
DSCR Cash-Out Calculator
Run the cash-out numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 8, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 8, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
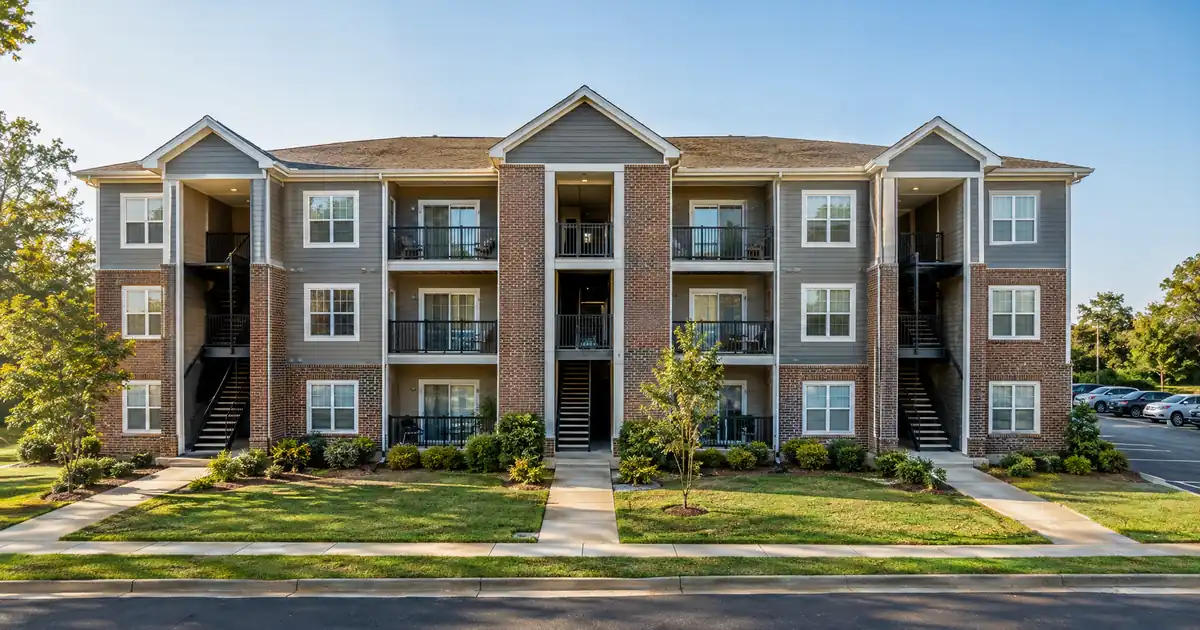
A fourplex sits in an unusual spot. It has four units, yet lenders treat it as small residential, not commercial. Five or more units move into commercial underwriting, which is a different process and outside this article.
DSCR (debt service coverage ratio) loans suit this building well. The lender looks mainly at the property’s rent compared with its payment, and qualification runs primarily on property-level rental income covering the payment, subject to lender guidelines. Your W-2s and traditional personal-income documentation is not the center of the file. That helps self-employed investors and anyone with many financed properties.
For the full background on the product, see Lendmire’s complete DSCR loans guide.
The Two Tests That Size the Loan
Every file faces an equity test and a coverage test. The smaller loan amount from the two wins.
The equity test. The lender applies a leverage ceiling to the appraised value. On a cash-out refinance of an investment property, that ceiling is about 75% LTV across most of the network. A rate-and-term refinance, which returns no cash at closing, can go higher, up to about 85% LTV on an investment property. Those figures are ceilings, not entitlements. A thin credit profile or a weak appraisal can pull the number lower. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
The coverage test. Monthly rent is divided by the full monthly property payment (PITIA). Clearing 1.00 means the rent covers that payment on paper. It does not mean the building cash flows. Repairs, vacancy, management, utilities, and capital expenses all sit outside the ratio.
A fourplex pools four rents against one payment. That is why these buildings often cover better than a single-family rental. It also means the equity test is the binding limit more often. More rent will not raise the loan if LTV is already the cap.
A Fourplex Example, Side by Side
Here are two modeled cases. They use ratios and percentages only, so you can see which test controls.
| Factor | Strong-rent fourplex | Thin-rent fourplex |
|---|---|---|
| Rent coverage | Around 1.3x | Around 0.95x |
| Cash-out ceiling | 75% LTV, investment property | 75% LTV, investment property |
| Binding limit | Equity (LTV) | Rent coverage |
| Likely path | Loan sized at the leverage cap | Select-lender path with adjusted leverage |
In the first case, the rent clears the coverage test with room to spare. The appraisal and the 75% cap decide the loan. Your move is to raise value or equity, not rent.
In the second case, coverage is below 1.00. A larger loan means a larger payment, which pushes coverage lower still. Programs that take coverage below 1.00 are available through select lenders in the network, with leverage and terms adjusted. Whether a given file fits depends on the borrower, the property, and the lender’s review.
This is the payment-shock problem. A building that cash flows today can look weak once the new, bigger payment replaces the old one. Test the post-refinance coverage before you order the appraisal, not after.
From Gross Loan to Cash in Hand
Think of net proceeds as a short subtraction.
| Step | What happens |
|---|---|
| New loan amount | Sized by the lower of the equity and coverage tests |
| Minus payoff | Existing first mortgage is retired |
| Minus junior liens | Any second loan or lien is paid off |
| Minus closing costs | Lender, title, and appraisal charges |
| Minus funded reserves | Any required reserves held back |
| Equals | Cash to you |
Seasoned equity can look large on paper and still produce a modest check. Run this subtraction first, then decide whether the next move still pencils.
On reserves, the rules vary by lender, leverage, loan size, and transaction type. About 6 months of PITIA is common. Conservative rate-and-term files at modest leverage under $1,500,000 can see reserves waived, while loans above that size typically step up to about 9 months. Ask the lender whether cash-out proceeds can count toward your reserve requirement, because policies differ.
What the Appraiser and Lender Do With Four Units
The lender orders an appraisal on a small-income-property form. For two- to four-unit buildings, that is Form 1025, which Fannie Mae’s Selling Guide lists for traditional appraisals of two- to four-unit properties. DSCR loans are not agency products, but they borrow the form names by convention. The appraisal gives you two numbers at once: a value for the leverage test and a rent opinion for the coverage test.
The appraiser forms an independent rent opinion. The lender then decides which figure to use. As McKissock, an appraiser-education provider, explains, income is ultimately decided by the lender. Your rent roll helps, but it does not set the number alone.
Four units create four chances for friction.
- Mixed tenancy. A fixed-term lease, a month-to-month tenant, an expired lease, and a vacant unit can each be treated differently. A common convention is to use the lower of lease rent and market rent.
- A vacant or below-market unit. One weak unit lowers the total, and it can pull the whole ratio down with it.
- A unit under renovation. Expect the lender to ask how that unit is counted, or whether the work should finish first.
- Access. The appraiser needs to see all four units, so one uncooperative tenant can stall the file.
Where the General Rule Breaks
The 75% cash-out figure and the 1.00 coverage starting point cover the standard case. These edge cases bend them. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
- Seasoning. About 6 months from title recording is the common expectation. This is lender policy, not law. Inherited property, a transfer from an LLC to an individual, and cash purchases refinanced soon after can each be treated differently, depending on the lender.
- Short-term rental units. A fourplex with units run as short-term rentals is underwritten differently. Cash-out on short-term-rental collateral caps near 70% LTV, versus 75% for a standard rental, and lenders typically want a 640+ score and about 12 months of hosting history. Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income.
- Condo-style projects. A two- to four-unit building inside a condo or co-op project triggers extra project review.
- An existing prepayment penalty. Many DSCR loans carry a penalty that steps down over time. Paying off a loan early can trigger it, so read your current note before you order an appraisal. The same applies to the new loan, since it affects your next refinance or sale.
- Non-eligible structures. Manufactured homes (single- and double-wide), log homes, and barndominiums are not offered in the network’s DSCR programs.
- Buildings of five or more units. These leave the small-residential lane entirely.
Structures and Loan Terms
The 30-year fixed loan is the spine of most programs. Extended terms such as a 40-year schedule, and interest-only periods, are available through select lenders in the network. ARM structures exist for investors who want them.
Standard programs run up to $3,000,000. Above $2,500,000, the network generally holds to 30-year fixed structures. A larger down payment on a purchase lowers the payment and can lift coverage. It never erases leverage caps, credit floors, reserve rules, or property eligibility. The strongest files clear both tests: enough equity and enough rental coverage.
Business-Purpose Treatment
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage. The Federal Register rulemaking states that investment-purpose loans are considered business-purpose loans. Expect to sign a statement that the proceeds are for business or investment use, and use them that way. Legal commentary in Lexology stresses that business purpose is something the lender must determine, not a blanket pass.
Tax treatment can depend on how the funds are used and how the property is held; investors should keep clear records and speak with a qualified tax professional before relying on any deduction.
Documents and Process, Step by Step
1. Application and vesting. You can usually hold title individually or in an LLC, subject to lender program eligibility.
2. Entity and payoff paperwork. An LLC adds entity documents. Your current lender supplies a payoff statement.
3. Rent evidence. Leases or a rent roll, plus proof tenants pay.
4. Credit and reserves. Credit review, plus proof of reserves.
5. Insurance. A policy that matches the building.
6. Appraisal. The lender orders it and sees all four units.
7. Sizing. The lender compares the equity limit and the coverage result, and the lower one sets the loan.
8. Funding of the net proceeds. Payoff, costs, and reserves come out, and you receive the rest.
Programs change and every file is underwritten individually, so treat each step as typical, not guaranteed.
Deciding Whether to Pull the Cash
Ask three questions before you refinance.
Does the building still cover its payment after the refinance? If coverage lands near 1.0x, stress-test it with your own vacancy and repair numbers. A file can pass and still run thin.
Does the next move beat the cost of this one? Using cash-out proceeds to buy another rental works only if the new property’s own coverage and your reserves hold up. Lendmire’s piece Using Cash Out Refinance To Buy Investment Property walks through that decision.
Is another tool a better fit? A rate-and-term refinance returns no cash and allows higher leverage. Investment-property HELOC lines cap at $500,000 total, and they generally need personal title, so an LLC-held building often cannot use one. Selling releases equity but gives up the asset.
Key Terms Defined
- Cash-out refinance: A new loan larger than your payoff balance, with the difference paid to you.
- LTV: The loan amount divided by the appraised value.
- DSCR: Monthly rent divided by the full monthly property payment.
- PITIA: Principal, interest, taxes, insurance, and association dues, the full monthly payment the coverage test uses.
- Seasoning: The waiting period after you take title before a lender sizes on appraised value.
- Reserves: Liquid funds you must show, counted in months of PITIA.
- Vesting: How title is held, such as in your name or in an LLC.
Frequently Asked Questions
How much cash can I take out of a fourplex?
It depends on the lower of two limits. On an investment property, cash-out generally tops out around 75% LTV, and rent coverage must also clear the program’s floor. From that loan amount, payoff, liens, costs, and any funded reserves come out. What remains is your cash, which is why equity alone never tells you the check.
Does one vacant unit hurt my chances?
It can. A vacant or below-market unit lowers the combined rent, and that lowers the coverage ratio. Lenders often count the lower of lease rent and market rent, so a unit with no lease may be counted at the appraiser’s figure. Filling the unit before applying usually strengthens the file.
Can I hold the fourplex in an LLC?
Often yes, subject to program terms. DSCR lenders generally let you vest title individually or in an LLC, and an LLC adds entity documents. If you want to move title between yourself and an entity, raise it early, because seasoning and ownership rules can differ by lender.
What if coverage lands below 1.00?
That does not end the conversation. A separate select-lender path takes coverage below 1.00, with leverage and terms adjusted. The tradeoff is a lower loan amount or different terms than a stronger-coverage file would see, and eligibility depends on credit, reserves, and property review.
Do I need my traditional personal-income documentation?
The file centers on the building’s rent, not your personal income, so traditional personal-income documentation is not the core document. You still provide rent evidence, an appraisal, insurance, credit, and reserves.
Next Step
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. Lendmire is a broker that arranges financing through select lenders in its wholesale network across 41 markets, including Washington, D.C. This is not a commitment to lend. The calculator on this page gives an illustrative estimate only, and your actual terms depend on lender review.
For how equity extraction works on an investment property, see Lendmire’s guide to cash-out refinance on an investment property.
About Lendmire
As a non-QM mortgage broker (NMLS# 2371349), Lendmire facilitates DSCR investor loans across 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income instead of personal income documentation, subject to lender guidelines, serving LLC-structured portfolios and self-employed borrowers who don’t fit conventional boxes. A two-time Scotsman Guide Top Mortgage Workplace (2025, 2026).
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. McKissock: Form 1007 and short-term rental appraisals
3. Federal Register: Ability-to-Repay and Qualified Mortgage Standards Under Regulation Z
4. Lexology: Beware of Business Purpose
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Investment Property Cash-Out Refinance for Landlords Sizing Equity Limits · Cash-Out Refinance on a Rental for Investors: Where to Reinvest the Cash · Cash-Out Refinance vs Refinance Plus HELOC When Paying Off a HELOC
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.