
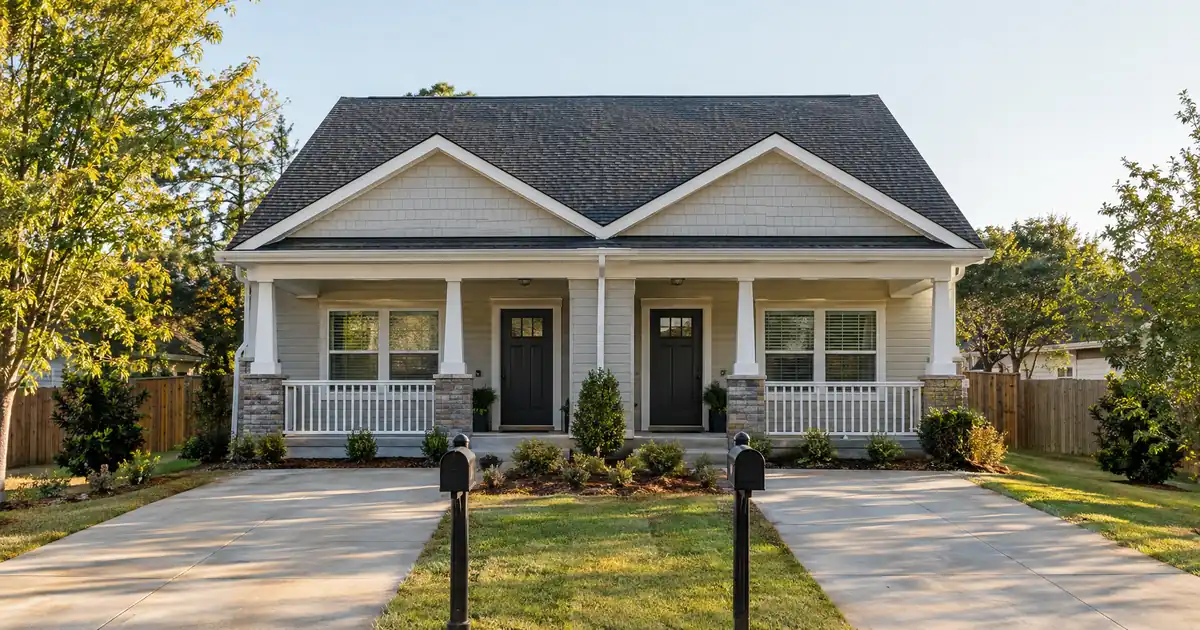
The Quick Read: Two duplexes count as two properties and four units. A portfolio minimum written in properties is met at two, while one written in units must be checked against the four doors. Coverage is then tested on the pooled rent, subject to lender guidelines.
- On a property-count test, two duplexes equal 2. On a unit-count test, they equal 4.
- The 30-year portfolio loan in Lendmire’s wholesale network starts at 2 properties, so two duplexes fit.
- The rental portfolio term loan starts at five or more properties or units, so two duplexes fall one door short.
- Coverage is measured on the pool: combined rent against combined PITIA. A strong building can offset a weaker one.
- Each building is still appraised, and each needs a lease or an appraiser-supported market rent.
No regulator or trade body defines “portfolio minimum.” It is a program parameter, set in each lender’s guidelines and written into the loan documents. That makes the first job simple: find out whether the program counts properties, units, or both.
Properties, Units, and Loans: What Actually Gets Counted
A duplex is one building on one lien, with two rentable doors. So two duplexes are two collateral properties, four units, and one loan if you pool them. Those are three different counts, and portfolio minimums can be written against any of them.
| Count | Two duplexes equal | Where it matters |
|---|---|---|
| Properties | 2 | Minimum number of properties in the pool |
| Units | 4 | Unit-based tiers and rent totals |
| Loans | 1 (pooled) or 2 (separate) | Closing, servicing, release terms |
Across the programs we place files with, the wording differs. Some state a minimum number of properties. Some state a minimum number of units. Some list both as separate lines. The same two buildings can pass one test and miss the other.
Duplexes belong in the pool without any special treatment. They are 2-4 unit residential properties, and those stay in residential-style underwriting. Five or more units in a single building moves a property into commercial underwriting, which is a different path.
Which Portfolio Loan Fits Two Duplexes?
The 30-year portfolio loan fits. It takes 2 to 20 properties under one note, with loan sizes of roughly $300,000 to $5,000,000 (larger balances on review). Leverage goes up to 80% of value on a purchase or rate-and-term refinance of investment property. Programs of this type typically allow SFR, 2-4 unit, condo, and townhome collateral, and an interest-only period is available. All of it is subject to lender guidelines.
The rental portfolio term loan is built for bigger holdings. It starts at five or more rental properties or units under one loan, with balances from $500,000 up to $50,000,000 and leverage up to 75% of value. Terms are fixed for 3, 5, 7, or 10 years with a balloon at maturity, and non-recourse structures exist with carve-outs. Terms depend on the lender’s guidelines, the property type, the leverage, and a full review of the credit profile.
Run two duplexes through the unit test and you get four, which is one door short of five. Add a third property and the picture changes. Two duplexes plus a single-family rental is three properties and five units. Whether that qualifies depends on whether the lender’s tier counts “properties or units,” so ask for the wording.
For the loan-size side, two duplexes can clear the count and still fall short on aggregate balance. A modest pair of buildings with low leverage may not reach the loan-size floor. Check both numbers, not just the property count.
One more pair of tests applies to the pool. Credit floors typically start around 640, and some portfolio structures want 680 or 720. Some structures also require a special-purpose entity, usually an LLC, subject to program terms.
How Underwriting Treats Two Duplexes, Step by Step
Here is the sequence a pooled file typically follows. Steps run in this order because each one feeds the next.
1. Classify each building. Each duplex is a two-unit residential property. A legal unit count matters here, because an unpermitted conversion changes the file.
2. Count the collateral. Each duplex carries its own lien. The pool holds two properties, and the unit count of four is used for rent and for any unit-based tier.
3. Order the appraisals. Each duplex gets its own appraisal on Form 1025, the small residential income property report for 2-4 units, which appears on Fannie Mae’s list of appraiser forms. It reports value and per-unit market rent in one document. A pooled loan does not remove appraisal costs. Every building is still valued.
4. Set the rent per building. The rents of both units are added together. Underwriting typically uses the lower of the appraised market rent or the signed lease. Every property still needs a lease or an appraiser-supported market rent.
5. Pool the numbers. Add the rent from all four doors. Divide it by the combined PITIA, which is principal, interest, taxes, insurance, and any association dues, on the single note.
6. Assign allocated amounts. The lender allocates part of the loan to each building. Those allocations drive the release terms if you ever sell one.
7. Close under one note. Expect one credit review, one asset verification, and one servicer.
The textbook version of this ratio, as Corporate Finance Institute explains, measures cash flow against debt obligations, with a result above 1.0 meaning the income covers the debt. Rental DSCR loans simplify the numerator to rent and the denominator to PITIA. DSCR qualifies primarily on property-level rental income covering the payment, subject to lender guidelines.
A Worked Example With Ratios Only
Run the numbers on two duplexes with roughly equal monthly obligations. These are modeled assumptions, not market data.
- Duplex one, tested alone, covers its payment at about 1.25x.
- Duplex two, tested alone, covers it at about 0.90x.
- Pooled, the combined rent against the combined PITIA lands near 1.08x.
On a pooled test, the stronger building carries the weaker one. The pool clears a 1.00 floor even though one building would not. A rental below 1.00 can sit inside the pool, but pooled coverage, leverage, and terms are what underwriting tests, subject to underwriting.
Split them into two loans and duplex two becomes its own coverage-below-1.00 file. That is a separate path. Select lenders in the network offer coverage below 1.00, with leverage and terms adjusted. It is not the same product as the pooled structure.
Clearing 1.00 is also not the same as positive cash flow. Repairs, vacancy, management, utilities, and capital expenditures sit outside the calculation. A pool at 1.08x can still be tight after a roof claim.
Where the Pool Can Go Wrong
Pooling helps when one duplex is thin. It hurts when one duplex is truly weak, because the lender holds both buildings as collateral for one note. A default on the loan touches both properties.
Picture an investor whose first duplex is stabilized and whose second is half vacant after a renovation. Pooled, the vacant units count only if the program allows market rent on vacant doors, and that is program-dependent. Rent from occupied units counts. The investor may do better to stabilize the second building first, or to carve it out into its own loan.
| Factor | Two-duplex pool | Two separate loans |
|---|---|---|
| Coverage test | Pooled rent vs pooled debt | Each building alone |
| Weak building | Carried by the strong one | Stands on its own |
| Selling one | Follows release terms | Each lien is independent |
| Closing | One closing, one servicer | Two of each |
| Appraisals | One per building | One per building |
The decision is flexibility against pooled coverage. A pool gives qualifying strength. Separate loans give clean exits. Many investors choose based on whether they plan to sell either building in the next few years.
Edge Cases Where the General Rule Breaks
Several situations change the answer for two duplexes. Most are paperwork problems that surface late.
- A unit-based tier. Four units miss a five-unit threshold. Ask the lender whether the minimum counts properties, units, or either one.
- Separate notes sold as a portfolio. Only a cross-collateralized structure pools the risk. If you want separate liens, confirm in writing that each property carries its own note and release.
- Mixed ownership. Several LLCs can share one note when the same people ultimately own them, but programs differ on how they handle it. This is subject to lender program eligibility.
- Unit-count legality. Lenders want evidence the building is legally two units. Separate parcels or tax IDs can also change which program the file fits.
- Owner-occupied units. If you live in one side of a duplex, that building is owner-occupied. Owner-occupied property is ineligible in a DSCR pool.
- Vacant units. Rent from occupied units counts. Treatment of a vacant unit is program-dependent.
- Short-term rental use. The appraisal forms were built around monthly long-term rent, and the lender decides how to treat short-term income. Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income.
- Ineligible property types. Manufactured homes, log homes, and barndominiums are not offered in these programs. Neither are mixed-use or commercial properties.
- Different markets. The rental portfolio term loan allows properties in several markets under one loan. Whether the 30-year loan does depends on the lender.
For a conventional comparison, Fannie Mae’s selling guide counts financed properties rather than units, and a two-unit property counts as one property. That is a conventional-loan rule, not a DSCR rule. DSCR programs write their own counting language, but the logic points the same way: a building is a property.
Release, Exit, and Adding a Third Property
Release terms decide how much freedom you have after closing. A release clause lets you sell one building and keep the other under the loan. It is common, but not guaranteed. The release price runs above the property’s allocated balance, and the remaining portfolio must still cover its debt service.
With two duplexes, that second condition bites. Sell one and the building you keep has to carry the leftover balance by itself. Some structures also treat a drop below the program minimum as a trigger for a full payoff. Without any release clause, selling one building may mean refinancing the whole pool. Tax treatment varies; consult a qualified professional.
Cash-out on a pooled loan stays at or below 75% of pooled value, and seasoning rules cap proceeds early in ownership. For a broader picture of refinancing options, see Lendmire’s complete DSCR loans guide.
Adding a third property later is usually not automatic. Substitutions and additions follow the loan documents and the lender’s terms. Often the practical route is a new loan or a restructure. If you expect to grow past two buildings, ask about it before you sign.
Pre-Application Checklist for a Two-Duplex Pool
Gather these before you talk to anyone:
- Leases for all four units, plus a current rent roll.
- Proof of legal unit count for each building, and parcel or tax ID details.
- Vesting and entity documents, if the buildings sit in LLCs.
- Insurance and tax details for each building, since both flow into PITIA.
- Asset statements for reserves. Reserves vary by lender, leverage, and loan size, commonly around 6 months of PITIA. Lendmire’s piece Does a Portfolio Investor’s Brokerage Count Toward DSCR Reserves? covers that side.
Then ask the lender these questions in writing:
1. Is the minimum counted in properties, units, or both?
2. Is there a minimum aggregate loan amount?
3. Is the loan cross-collateralized, or are the notes separate?
4. Is there a release clause, and how is the release price set?
5. What happens if I sell one building?
Expect the appraisal rent to come in below a hopeful seller listing on a 2-4 unit property. Underwrite your own numbers conservatively before you rely on the advertised rents.
Key Terms Defined
Portfolio DSCR loan: one loan secured by several rental properties, qualified on their combined rent against their combined debt service.
Cross-collateralization: using every property in the pool as collateral for the whole loan, not just its own share.
Release clause: a loan term that sets the price and conditions for removing one property from the pool.
PITIA: principal, interest, taxes, insurance, and association dues, the full monthly housing obligation on a property.
Allocated loan amount: the slice of the pooled loan the lender assigns to each building.
Frequently Asked Questions
Does a duplex count as one property or two?
One property. A duplex is one building on one lien, with two units. It counts as one property on a property-count test and as two units on a unit-count test. Always confirm which test the program uses.
Is two properties enough for a portfolio loan?
On the 30-year portfolio loan in the network, two properties is the starting count, subject to lender guidelines. The rental portfolio term loan starts at five or more properties or units, so two duplexes would fall short there.
Do both duplexes need to pass individually?
Not on a pooled test. Coverage is measured on pooled rent against pooled debt service, so a stronger building can offset a weaker one. Underwriting still reviews leverage, credit, reserves, and each property’s rent support.
Can I mix a duplex and a single-family home in the pool?
Yes. Portfolio programs typically accept single-family, 2-4 unit, condo, and townhome collateral together, subject to lender guidelines. A single-family rental adds one unit, which can matter on a unit-based tier.
What if one duplex has a vacant unit?
Rent from occupied units counts. Whether a vacant unit counts at market rent depends on the program, so ask before you apply. Stabilizing the unit first often makes the pooled number stronger.
Next Steps
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. As a broker with DSCR programs across 41 markets, including Washington, D.C., it arranges financing through select lenders in its wholesale network. Two duplexes are a small pool, and small pools reward the investor who asks how the lender counts before the application starts.
About Lendmire
Lendmire — NMLS# 2371349 — is a mortgage brokerage specializing in DSCR investor loans, helping arrange financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. The model centers on property-level rental income reviewed by the lender rather than W-2 documentation, subject to lender guidelines, suiting entity-owned and multi-property investors. Lendmire holds Scotsman Guide Top Mortgage Workplace recognition for 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Fannie Mae: Appraisers Property Underwriting
2. Corporate Finance Institute: Debt Service Coverage Ratio
3. Fannie Mae Selling Guide B2-2-03: Multiple Financed Properties Same Borrower
This article is part of Lendmire’s DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How to Raise Pooled DSCR Coverage Before a Portfolio Loan · How a Portfolio DSCR Loan Moves From Application to Closing · Can Vacant Rentals Be Included in a Portfolio DSCR Loan?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.