
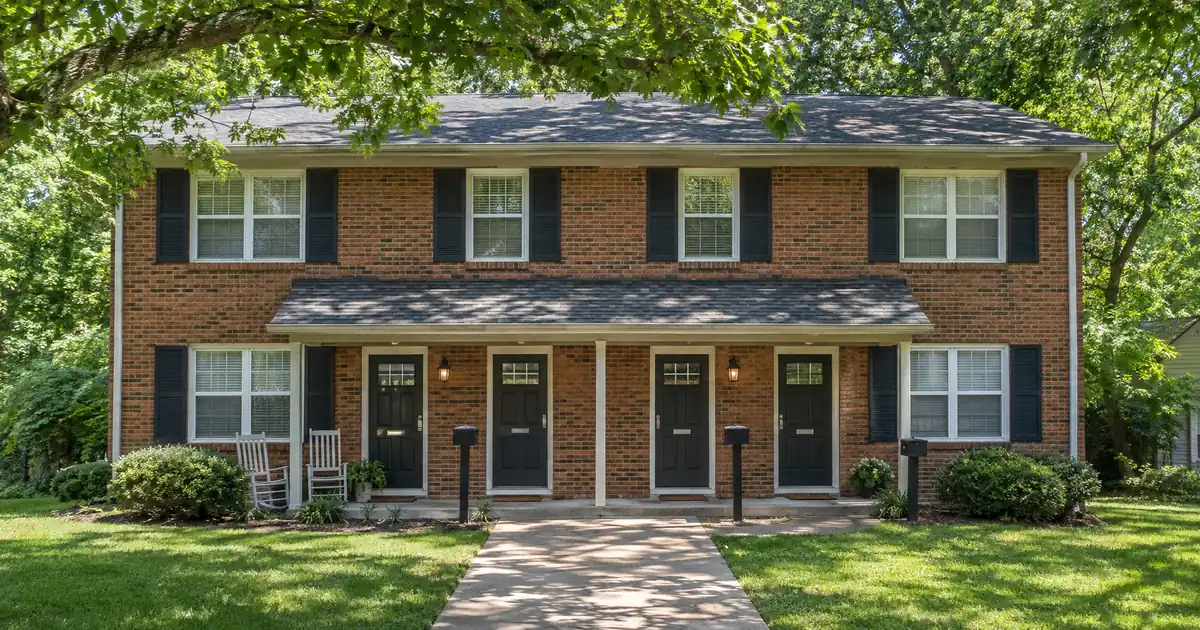
The Quick Read: On a small-town fourplex, a full appraisal is the norm across the wholesale lender network Lendmire places files with, because it sets both the property value and the market rent. An automated value estimates value alone, so it works best as a screening tool or a narrow exception on simpler, lower-leverage files. Neither product is a legal entitlement. Each lender decides which one it will accept.
- Appraisal: one inspected report gives you a value (which drives leverage) and a rent opinion for each unit (which drives coverage).
- Automated value: a computer estimate of value only. It does not inspect the building or support four unit rents.
- Small towns: thin sales and rental data weaken a model first and make an appraiser work hardest.
- Your move: ask early which valuation product the file will use and whether a desk review may follow.
The Honest Answer on Who Each Is For
The appraisal is for the investor who wants a loan on a fourplex and needs rent supported unit by unit. That describes most small-building buyers. The automated value is for a narrower situation: a lender screening a deal, cross-checking a report, or sizing a simple, conservative file where the model has plenty of data.
DSCR Calculator
Run the numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 15, 2026
Prefilled with starting assumptions — enter your own rent or nightly figures, taxes, insurance, and HOA for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 15, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Rent, nightly rate, occupancy, taxes, and insurance are editable estimates. Short-term rental figures are estimates only and vary significantly by season, property type, management approach, and local short-term-rental rules — confirm local regulations before relying on them. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
A fourplex strains a pure model more than a single-family house does. It has four rents to support, and a small town has few comparable sales. Treat the automated value as a helpful second opinion, not a replacement.
Side-by-Side
The automated-value column reflects published industry norms. Lender policy varies, so treat both columns as typical ranges.
| Factor | Full appraisal | Automated value |
|---|---|---|
| What it produces | Value plus unit-level market rent | Value estimate only |
| Human involvement | Licensed appraiser inspects | Model only, no inspection |
| Review basis | Value sets leverage; rent sets coverage | Supports the value side only |
| Documentation | Leases and rent comps support the report | Property record data; rent needs separate support |
| Property types | Fits 2-4 unit buildings | Better on standard, data-rich properties |
| Entity vesting | LLC titling is common, subject to lender program eligibility | Same entity rules apply |
| Timeline | Includes an inspection step | No inspection step; a desk review may still follow |
| Reserves | Set by loan size and leverage, not by valuation product | Same |
Key Terms Defined
DSCR is the debt service coverage ratio: monthly rent divided by the full monthly obligation (principal, interest, taxes, insurance, and any HOA dues, together called PITIA).
LTV is loan-to-value, the loan amount as a percentage of the property’s value or price.
Automated valuation model (AVM) is a computer model that estimates value from public records and sales data.
Desk review is a second look at an existing value, done from data rather than on site.
Form 1025 is the appraisal form for 2-4 unit income properties. It carries the rent analysis. Form 1007 is the single-family rent schedule and does not apply to a fourplex. These names are borrowed vocabulary, since DSCR loans are not agency products.
Seasoning is the waiting period a lender wants between buying a property and refinancing it.
When the Appraisal Is the Better Fit
Pick the appraisal path, which is the default on most small-building files, in these cases:
- You are buying a fourplex. A purchase needs a value that holds up against the contract price. On purchases, most files land at 75%-80% LTV, and a select high-leverage tier reaches 85% for borrowers around 700+, subject to lender guidelines.
- Rent is the weak link. A model has no way to look at four leases or a rent roll. The appraiser picks rental comparables for each unit and gives an opinion of market rent.
- The building is unusual. Mixed unit sizes, an odd layout, or extra land push a model past what it can read. Appraisers lean on both the sales-comparison and income approaches for 2-4 unit properties, per AppraiserPoint.
- The loan is large or leveraged. Higher leverage and bigger balances give a lender less room to lean on an estimate.
- You want a land-value breakout. Appraisers often separate land from improvements, and tax treatment can depend on how that split is used, so keep clear records and speak with a qualified tax professional.
Many programs credit the lower of your actual lease and the appraiser’s market rent. A strong lease does not lift coverage past what the market supports. Clearing 1.00 is also not the same as positive cash flow, because repairs, vacancy, management, utilities, and capex all sit outside the ratio.
When the Automated Value Is the Better Fit
An automated value earns its place in a few narrower situations:
- Screening before you commit. A lender or you can run a model early to see whether a deal is in range.
- Cross-checking a report. A second data point can flag an appraisal that looks out of line, which can lead to a desk review.
- A simpler refinance. Where the property is standard, the market is data-rich, and leverage is conservative, a lender may lean on lighter valuation. Lendmire’s piece Appraisal Waivers on a Refinance: When the Automated Value Is Enough covers that case.
- A rent sanity check. Separate automated rent models exist. Whether a lender accepts one in place of an appraiser’s rent opinion varies, so ask.
A model gives you a number and, usually, a confidence score. It cannot see a gutted unit, a failed roof, or a leaking basement. Skip it as your only support on a mixed-condition fourplex. The saving rarely survives a surprise.
Why Small Towns Strain Both Products
Small-town fourplexes expose weak data first. Rural markets have fewer transactions, so appraisers may widen the search to neighboring towns, according to McKissock, an appraiser-education publisher. When comps are scarce, appraisers commonly widen the radius, adjust for differences, and use local insight, as another McKissock piece describes.
A model works from the same thin transaction data. Its confidence tends to be weakest exactly where the appraiser is working hardest. (That is a practitioner inference, not a published statistic.) Rental comps run thinner still, since a small town may have few active rentals. A cautious appraiser may land on a conservative rent opinion.
Bad property records add another trap. A wrong unit count, a wrong square footage, or an unpermitted conversion can corrupt a model’s output without anyone noticing.
Property type matters too. Manufactured homes (single- and double-wide), log homes, and barndominiums are not offered in the network’s DSCR programs. Rural buyers should check this before falling in love with a building. It is an eligibility question, not a valuation one.
Worked Example: One Fourplex, Two Valuation Routes
Here is a hypothetical, using modeled percentages only. Say you are buying a fourplex in a town with only a handful of recent nearby sales. You plan a 75% LTV purchase. The rents on your leases would produce a coverage ratio near 1.25x. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Route one, the model. The estimate comes back close to your contract price. It looks clean, but it says nothing about unit rents. A lender still needs support for rent.
Route two, the appraisal. The appraiser widens the search and lands 6% below the contract price. Because leverage is sized on the lower of value or price, your effective loan comes out near 70.5% of the price, since 75% of 94% is about 70.5%. The gap comes out of your cash to close. The appraiser’s market rent also comes in 8% below your leases. Coverage drops from roughly 1.25x to about 1.15x.
Both outcomes still clear 1.00x. Still, a lower coverage number can change which leverage tier a file fits, depending on the lender. The appraisal gave you worse news, and it was more complete news. Better to learn it before closing than after.
Across files like this, the surprise is rarely the value. It is the rent opinion, because investors tend to set expectations on leases and pro forma numbers, and neither is what the report uses.
What If the Two Numbers Disagree?
Work the disagreement in this order:
1. Check the data. Confirm unit count, square footage, and permitted status match the property record.
2. Send better comps. Supply recent sales and rentals the appraiser may have missed, along with unit-level lease data.
3. Ask for reconsideration. Request a value review with your supporting comps attached.
4. Reset the deal. If the value holds, expect a smaller loan, more cash to close, or a renegotiated price.
On refinances, cash-out tops out around 75% LTV across most of the network, with about 6 months of seasoning as the common expectation. A rate-and-term refinance can go higher, and select programs reach 85%, so a low value hurts a cash-out file more than a rate-and-term one. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
DSCR vs. conventional financing
There are two common ways to finance an investment property, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Where Valuation Meets the Rest of the File
The valuation method does not change the other tests. Credit still matters: a 620 floor exists in parts of the network, most programs want around 660, and 700+ opens the strongest leverage tiers. Reserves run about 6 months of PITIA on typical files, with loans above $1,500,000 commonly stepping up to about 9 months. Conservative rate-and-term files at modest leverage under that size can see reserves waived, depending on the lender. Standard programs go up to $3,000,000.
Most standard programs start around 1.00x coverage. A separate path through select lenders takes coverage below 1.00 with leverage and terms adjusted. No-ratio structures are available only through select lenders, generally for borrowers who already own a primary residence. Our complete DSCR loans guide walks through the full set of tests.
Words like appraisal and evaluation are not interchangeable either. Bank regulators treat an evaluation as something different from a full appraisal, and an evaluation need not come from a licensed appraiser, per FDIC guidance. Those rules govern regulated depository institutions, not DSCR files. The 2018 interagency rule’s commercial real estate definition also leaves out single 1-to-4 family collateral. Use them only as a reminder that valuation vocabulary is precise.
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage.
The Verdict
Choose the appraisal when you are buying, when rent needs unit-by-unit support, or when the building is anything other than plain. For a small-town fourplex, that is most files.
Treat the automated value as a screen or a cross-check, and as a possible primary tool only on simpler, lower-leverage files where the data is deep. A model can be wrong in either direction, and nobody inspects the interior. Which product a lender accepts is a lender decision, so ask before you order anything.
Frequently Asked Questions
Do I need an appraisal on every DSCR loan?
Not by any federal rule that applies to business-purpose loans. It is a lender policy choice. On a fourplex, most programs in the network use a full appraisal, though a lighter valuation may fit some simpler files.
Can an automated value replace the appraisal on a fourplex?
Rarely as the sole support. A model estimates value only, and the lender still needs rent supported across four units. A lender may use one as a screen or cross-check, subject to its guidelines.
Will the appraisal also set my rent?
Yes, on a 2-4 unit report. The appraiser gives an opinion of market rent, and many programs use the lower of that figure and your actual leases.
What if the appraisal comes in low?
Check the property data, send stronger comps, and request a value review. If the value holds, expect a smaller loan or more cash to close, and recheck whether coverage still clears the program’s floor.
How accurate are automated values in small towns?
They tend to be least reliable where sales are few, because the model works from the same thin data an appraiser struggles with. Condition and unusual features are also invisible to a model.
A Practical Next Step
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. As a mortgage broker, Lendmire arranges DSCR investor loans through select lenders in its wholesale network across 41 markets, including Washington, D.C. Call 828-256-2183 or request a quote to start.
In a town where only a few fourplexes sell each year, the appraiser’s judgment is the thing that fills the gap a model cannot.
About Lendmire
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that helps arrange investor financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR eligibility is generally reviewed by the lender around the property’s rental income rather than personal income documentation, subject to lender guidelines — which works for self-employed investors, LLC operators, and portfolios above four financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. AppraiserPoint: Appraisals by Property Type
2. McKissock: Appraising Rural Properties
3. McKissock: Arriving at an Accurate Appraisal When Comps Are Few
4. FDIC Financial Institution Letter on evaluations and appraisals
This article is part of Lendmire’s DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Can an Investor With a W-2 Job Skip the Bank for a DSCR Loan? · How to Underwrite a Condo on a DSCR Loan With the Dues and Budget · Can a Cash Buyer Get a Second Appraisal Before a DSCR Cash-Out?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.