
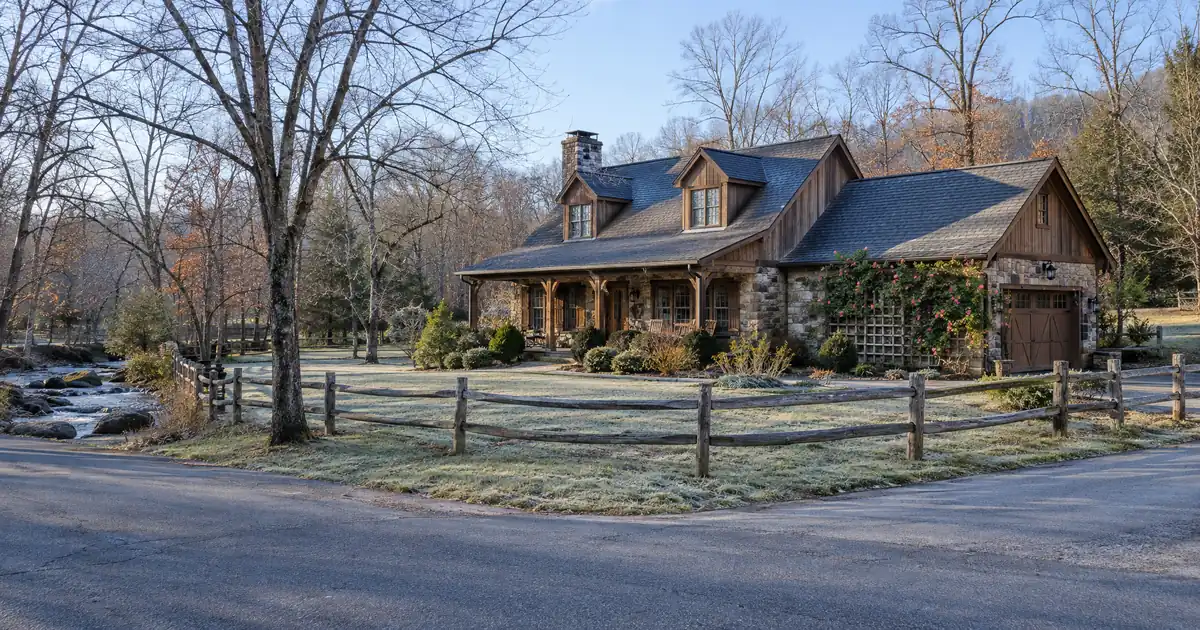
The Quick Read: A conventionally framed home on acreage can be reviewed for a DSCR loan, while a unique build such as a log home, barndominium, or manufactured home is not offered through the wholesale network’s DSCR programs. Structure type is screened before rent is ever counted. Acreage then adds a second screen on top of the first.
- A standard frame-built house on rural land is reviewed on its own facts, subject to lender guidelines.
- Log homes, barndominiums, and manufactured homes fall outside these programs, whatever the rent or equity.
- Acreage caps vary by program and loan size, and excess land may need to be carved out of the appraisal.
- A DSCR loan is a permanent takeout on a finished, rentable property. It does not fund construction.
- Purchases typically run 75%–80% LTV on most files, with qualification resting on rent covering PITIA.
The honest answer to who each option is for: a standard build suits an investor who wants a rural rental financed on property income. A unique build suits an owner-user or a builder who has a different financing path in mind, such as a farm-credit lender, rural bank, or portfolio lender. Those are not DSCR programs. Pick the structure first. The loan follows.
DSCR Calculator
Run the numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 15, 2026
Prefilled with starting assumptions — enter your own rent or nightly figures, taxes, insurance, and HOA for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 15, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Rent, nightly rate, occupancy, taxes, and insurance are editable estimates. Short-term rental figures are estimates only and vary significantly by season, property type, management approach, and local short-term-rental rules — confirm local regulations before relying on them. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Side-by-Side
| Factor | Standard build on acreage | Unique build on acreage |
|---|---|---|
| Review basis | Rent vs. PITIA, plus credit and leverage | Not applicable if type is ineligible |
| Structure screen | Reviewed on its own facts | Log, barndominium, manufactured: not offered |
| Appraisal | Value plus rent schedule | Thin comps, wider search, cost approach |
| Documentation | Contract, appraisal, insurance, entity papers | Same, but the file stops at property type |
| Entity vesting | LLC generally accepted, subject to program terms | Does not change property-type eligibility |
| Reserves | Commonly around 6 months PITIA | Moot if structure is ineligible |
| Timeline | Follows normal appraisal and review steps | Depends on the alternate lender used |
| Exit and resale | Broader buyer pool | Narrower pool, value swings with style |
Key Terms Defined
DSCR: Monthly rent divided by PITIA, which is principal, interest, taxes, insurance, and any HOA dues.
Standard build: A conventionally framed (stick-built or similar) single-family home, even if it has rustic finishes.
Unique build: A structure unlike nearby housing, such as a log home, barndominium, dome, or earth/berm home.
Excess land: Acreage that can be separated and sold on its own and has its own highest and best use.
Surplus land: Acreage that cannot be separated and is valued as part of the main site.
Takeout loan: The permanent loan that follows a completed build. It pays off short-term construction money.
How a Lender Screens the Two Options
The screen runs in a fixed order, and income comes late. Across the wholesale network, the property-type check comes first. Construction type, road access, water, septic, and permitted use at the address all get looked at before the coverage ratio matters. Strong rent cannot cure an ineligible structure. That surprises investors more than any other point on rural files.
Then comes the rurality screen. Appraisers generally want a neighborhood that is at least a quarter developed. Land above a program’s acreage cap typically has to be carved out of the appraisal. Caps tighten as loan size grows, so a parcel that works at a modest balance can fail at a higher one. Rural does not mean automatic denial. It generally means closer review, a lower leverage tier, an acreage cap, or a different program.
Why do unusual structures get screened out? Comps. An appraiser has to find comparable sales for value and comparable rentals for market rent. A structure unlike anything nearby has neither. No verified rent means no coverage number. The thin-comp problem that acreage already creates gets worse when the house itself is unusual.
What the Appraisal Does on a Rural File
The appraisal sets two numbers: value for LTV and market rent for coverage. On a single-family property, rent comes from a rent schedule completed with the value report. The agency form for that schedule is the Single-Family Comparable Rent Schedule, Form 1007, and the Fannie Mae Guide Forms list also shows Form 1025 for 2–4 unit income properties. DSCR is not an agency product, so those forms matter only as the names of the documents. The Fannie Mae Selling Guide shows the same form is required for a one-unit investment property when rent qualifies the borrower, which is a useful contrast for how the rent schedule works.
Form 1007 documents monthly rent only. It cannot estimate a nightly short-term-rental rate. An acreage cabin run as an Airbnb is underwritten on a full 12 months of income, so slow seasons count against the file. Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income.
The Acreage Piece: Excess vs. Surplus Land
Rent follows the house. Value can include land the rent never reflects. That gap is where acreage files get tangled.
McKissock explains that highest and best use is the reasonably probable, legal use that is physically possible, appropriately supported, financially feasible, and results in the highest value. It also separates excess land, which can be sold independently and is valued on its own, from surplus land, which cannot be separated and is valued as part of the primary site. In plain terms, a back forty that could be sold off is valued differently from a large yard that only serves the house.
How a lender treats that land is a program decision. Some programs carve it out. Others cap total acreage. The result is that LTV gets measured against the house and its supportable site, not against everything on the deed. Investors who price a deal on total acreage and then watch the appraisal carve out the excess are the ones who end up short on equity.
When a Standard Build Is the Better Fit
Choose the standard build when the goal is a rental financed on property income. A frame-built house on acreage can be reviewed on its own facts, subject to lender guidelines, credit approval, and property review.
Typical parameters on most files in the network apply:
- Purchases commonly run 75%–80% LTV, which means 20%–25% down.
- Cash-out refinances top out around 75% LTV on standard rentals.
- Coverage of 1.00 is where select programs start. A separate select-lender path goes below 1.00, with leverage and terms adjusted.
- Credit floors start at 620 in parts of the network. Most programs want about 660, and 700+ opens the strongest leverage tiers.
- Reserves commonly run about 6 months of PITIA, stepping up to about 9 months on loans above $1,500,000.
Gray areas matter here. A conventionally framed home with log-look finishes is reviewed on its own facts. A true log structure is not. The test is how the house is built, not how it looks. Cabin-style is not log. Frame-built cabins, A-frames, and lake houses are reviewed individually.
Consider a scenario with a frame-built three-bedroom on a few acres, bought at 75% LTV with rent that clears coverage in the low 1.2 range. That file is clean on structure, acreage, and coverage, so the open items are appraisal comps and well and septic checks. Now compare a similar house on a much larger parcel. The rent has not changed, but the acreage cap may force a carve-out, which can lower the supportable value and the loan amount. Same house, different file. Clearing 1.00 also does not mean positive cash flow. Repairs, vacancy, management, utilities, and capex all sit outside the calculation. Terms depend on the lender’s guidelines, the property type, the leverage, and a full review of the credit profile.
The paper trail is simple on a standard build: the purchase contract or title, the appraisal with rent schedule, insurance, well and septic information, and entity papers if the property is vested in an LLC, subject to program terms.
When a Unique Build Is the Better Fit
Choose the unique build only if DSCR investor loans is not the plan. A barndominium or log home can be a fine home, a fine business space, or a fine owner-occupied project. It is not eligible collateral for the network’s DSCR programs. Manufactured homes, single- and double-wide, fall in the same group. Domes and earth/berm homes tend to hit the same wall across non-QM.
An investor with strong rent and a large down payment still cannot cure the structure. A bigger down payment lowers the monthly payment and can lift the coverage ratio. It never erases property eligibility.
Outside commentary points to other routes for a barndominium, including farm-credit lenders, rural banks, and portfolio lenders. These are not DSCR programs, and their underwriting looks at income and the borrower differently. Some of those lenders treat a barndominium as agricultural property. Lendmire’s network excludes working farms and ranches, and agricultural zoning is also a problem.
Appraisal risk follows a unique build under any loan type. MeasureFloorplan notes that barndominium comps are often scarce, so appraisers may widen the search radius or lean on cost. It also notes that a structure that is half shop space appraises lower than an all-living-area building of the same size, because the market values living area above shop space. Build cost does not equal appraised value.
Resale is the other cost. A narrower buyer pool means value can swing with style, and exits take longer when the next buyer needs a different loan type too. Site costs on raw land add to it: power, well, septic, and driveway work can be large, and they come before any rent starts.
Where Both Options Run Into the Same Walls
A few rules apply no matter which structure is on the land.
Owner use. An LLC does not turn a personal-use cabin into a business-purpose property. Occupancy is judged on actual use.
Construction. A DSCR loan does not fund the build. It is a permanent takeout that follows completion. The file typically needs a certificate of occupancy, final inspection, utilities on, and builder documents. A certificate of occupancy is necessary, not sufficient. The home must also be lease-ready, appraised for value and rent, and an eligible property type. Ground-up work needs separate financing first.
Outbuildings. A barn or shop on the parcel can raise the agricultural flag even when the house is standard. If the secondary structure is a barndominium-style conversion used as a dwelling, the structure type issue returns.
Size and loan band. Standard programs run up to $3,000,000, and above $2,500,000 the network generally holds to 30-year fixed structures. Rural and acreage limits get tighter as the balance rises, so a parcel that fits one loan band may not fit the next.
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage.
DSCR vs. conventional financing
There are two common ways to finance an investment property, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Pre-Offer Checklist
Confirm these before writing an offer or ordering an appraisal:
1. Identify the construction type. Frame-built is reviewed. Log, barndominium, and manufactured are not offered.
2. Count the acreage and read the survey. Find out whether the parcel can be split or whether excess land will be carved out.
3. Check the surroundings. Look for developed neighbors and recent comparable sales and rentals nearby.
4. Confirm water, septic, road access, and permitted use at the address.
5. Decide the rental strategy. Long-term rent uses a rent schedule. Short-term rental needs hosting history and an annual income view.
6. Decide the vesting. LLC vesting is generally accepted on eligible properties, subject to program terms.
7. Ask for a property review before spending money on design or land.
The Verdict
The two options are not close on DSCR eligibility. A standard build on acreage is a workable rental project when the acreage, the comps, and the coverage all line up. A unique build is a different project that needs a different lender, a different underwriting basis, and a different exit plan. The strongest DSCR files clear both tests: enough equity and enough rental coverage, on an eligible structure.
For the full picture of how these loans work, see Lendmire’s complete DSCR loans guide. For how land size changes the file at higher price points, see Lendmire’s piece Acreage vs Standard Lot on a Luxury DSCR Loan After a Liquidity Event. If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. Tax treatment varies; consult a qualified professional.
Frequently Asked Questions
Does a log home qualify for a DSCR loan?
No. Log homes are not offered through the network’s DSCR programs, regardless of rent, comps, or equity. A conventionally framed home with log-look finishes is a different case and is reviewed on its own facts.
Does a barndominium qualify?
No. Barndominiums fall outside these programs. Investors with a barndominium typically look at farm-credit lenders, rural banks, or portfolio lenders, which underwrite differently and are not DSCR programs.
Does the acreage cap apply to the whole parcel?
Generally the lender looks at the whole parcel, and land above the program’s cap typically has to be carved out of the appraisal.
Can a DSCR loan fund the build itself?
No. It is a permanent takeout on a completed, rent-ready property. Construction needs separate financing, and the DSCR file typically follows a certificate of occupancy, final inspection, and utilities being on.
Does a rural label automatically disqualify a property?
No. Rural usually means closer review, a lower leverage tier, an acreage cap, or a different program. It is a screen that comes before income, so it is worth testing early.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire — NMLS# 2371349 — connects investors with wholesale lending channels across 41 markets, including Washington, D.C. The property’s rental income, not the borrower’s tax returns, is central to lender review, which works for self-employed operators and portfolios beyond four financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Fannie Mae: Selling Servicing Guide Forms
2. Fannie Mae Selling Guide B4-1.2-01
3. McKissock: Highest and Best Use in Appraisal
4. MeasureFloorplan: Barndominium Square Footage and Appraisal
This article is part of Lendmire’s DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How Much More Documentation a Bank Loan Needs Than DSCR · Can You Get a DSCR Loan After a Short Sale or a Lost Rental? · How to Refinance the Home You Moved Out of With a DSCR Loan
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.