
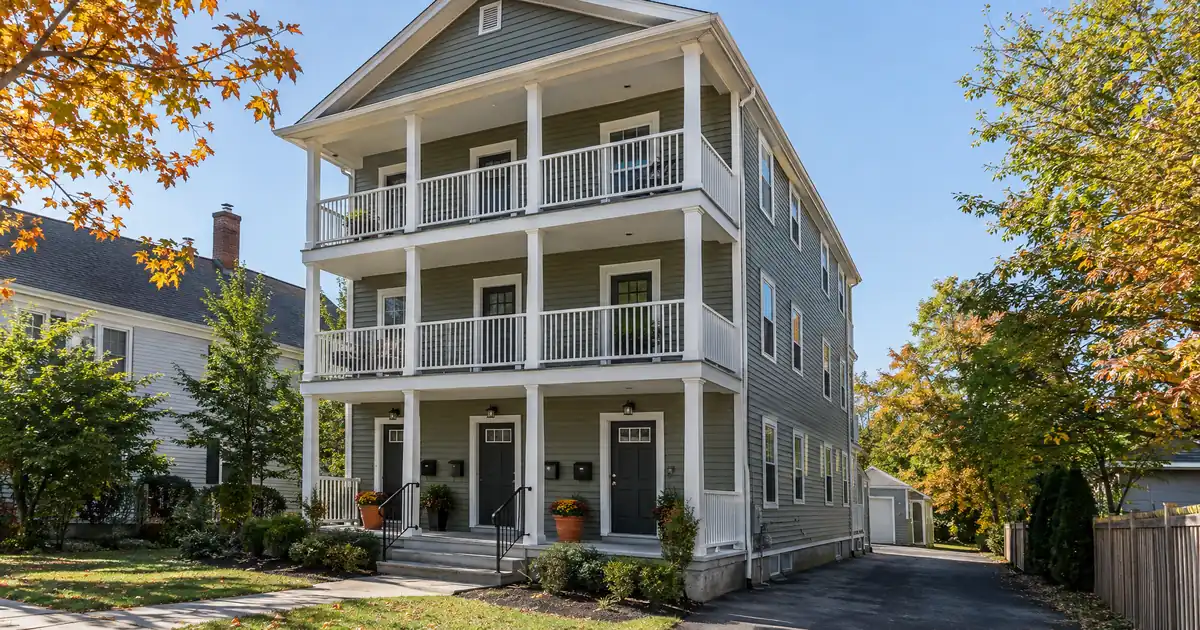
The Quick Read: FHA counts reserves as the verified liquid money you still have after you pay everything due at closing. The requirement depends on unit count: a three- or four-unit purchase calls for three months of the new payment in reserve, and a duplex usually has no blanket requirement on an automated file. Rent from the other units does not shrink that cushion. Details are subject to lender guidelines and full file review.
What “Reserves” Means on an FHA Loan
Reserves are your verified, documented liquid assets minus the total funds you must pay at closing. That is the definition in HUD Mortgagee Letter 2023-17. Think of it as the money left in the account after the closing table.
FHA payment estimate
Starting assumptions reflect an example price and the FHA minimum investment. Replace them with your own figures.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not an FHA loan quote.
Illustrative starting assumptions: a $350,000 price, the FHA minimum investment as the down payment, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not an FHA loan quote; your rate is set by the lender at lock. FHA mortgage insurance follows HUD’s published schedule for the term, leverage and loan size entered; taxes, insurance and dues are editable estimates; closing costs are not included; county loan limits are not checked here. Licensed in sixteen states for consumer mortgages. Lendmire is not affiliated with or acting on behalf of FHA, HUD, or the federal government.
The unit of measure is the monthly payment on the new loan, often shortened to PITI: principal, interest, property taxes, and homeowners insurance. Some lenders also fold in FHA mortgage insurance and association dues, so ask how your lender counts a “month.” Reserves are counted in months of that payment, not in a flat dollar figure.
Here is the part first-time buyers miss. The down payment and the reserve cushion cannot be the same dollars. Cash to close and cash after closing are two separate piles, and the file needs both.
Lendmire arranges these loans through wholesale lenders. Across the FHA loan programs it places, the base structure is a 3.5% minimum investment with maximum financing of 96.5%, at a decision score of 580 or higher. That 3.5% is the first pile. Reserves come on top of it.
How the Reserve Requirement Changes by Unit Count
Final terms depend on the lender’s guidelines, the property type, and the borrower’s complete credit picture.
The unit count sets the baseline. Here is how the HUD letter lays it out.
| Property | Reserve requirement | What to confirm |
|---|---|---|
| Duplex (2 units) | One month of PITI under manual underwriting | Whether your file is manual or automated |
| Triplex (3 units) | Three months of PITI | Self-sufficiency test also applies |
| Fourplex (4 units) | Three months of PITI | Self-sufficiency test also applies |
| 1 unit with an ADU, rent used to qualify | Two months of PITI | Only if the rent counts as income |
The one-month rule for one- and two-unit homes sits in HUD’s manual-underwriting section. A standard automated file on a duplex often carries no blanket FHA reserve rule. Other parts of the file can still ask for documented assets, so a duplex buyer should not assume zero.
Most of what you hear about house hacking and FHA runs through the occupancy rule. The loan is for a principal residence, one to four units, and you live in one of them. That is why the three- and four-unit cases get more scrutiny. More units mean more of the payment rests on tenants.
How the Underwriter Builds Your Reserve Number, Step by Step
Here is the sequence a file follows, in the order the underwriter sees it.
1. Pick the unit count. This sets the number of months required.
2. Size one month of the new payment. Principal, interest, taxes, and insurance, plus whatever your lender adds.
3. Total your verified liquid assets. Bank and brokerage statements are the usual proof.
4. Subtract the money needed at closing. That means your down payment, closing costs, and prepaids.
5. Strip out anything ineligible. Gift money, cash-out proceeds, and equity in other property come off the list.
6. Divide what remains by the monthly payment. On a three- or four-unit, the answer must be at least three.
7. Run the self-sufficiency test. On three- and four-unit homes, this is a separate test, and the file must pass both.
Picture a buyer eyeing a fourplex. Step four is where files stall. Savings that looked comfortable before closing costs and prepaids can drop below three months once those are paid. Do the subtraction before you make an offer, not after.
What Counts as a Reserve Dollar, and What Doesn’t
Money in your own bank, brokerage, or similar liquid accounts counts, if it is documented. HUD’s letter excludes several things, and they trip people up.
- Gift funds. A family gift can still help with your down payment and closing costs. It does not count toward reserves.
- Cash-out proceeds. Cash you take at settlement in a cash-out refinance is excluded.
- Incidental cash at settlement. Small amounts handed back to you at the closing table don’t count.
- Equity in another property. Your current home’s equity is not a liquid reserve.
Some lenders also treat borrowed funds as ineligible, and many lenders are stricter than the baseline. Ask yours for the list in writing. Retirement accounts and proceeds from selling another home are handled by lender policy, so treat them as a question to ask, not an assumption.
Sequencing matters too. Don’t move money between accounts late in the process. Unexplained deposits and large transfers need sourcing, and every explanation is more paperwork on your side.
Does Rent From the Other Units Reduce Reserves?
No. Rent helps you qualify, but it does not reduce the reserve requirement. Keep these three jobs separate. Leverage, reserves, and pricing vary by lender and program; the final terms follow the full file review.
- Reserves measure your savings after closing.
- Qualifying income is where rent from the units you don’t occupy may help your debt-to-income ratios. Lenders typically count only a portion of that rent, not all of it, so confirm the factor with your lender.
- Self-sufficiency is the three- and four-unit test. It uses the appraiser’s market rent for all units, subtracts a vacancy and maintenance allowance, and checks whether the result covers the full payment.
Reserves and self-sufficiency are not the same test. Many buyers pass one and fail the other. Treat the exact formula as something your lender must show you from HUD Handbook 4000.1, the consolidated source of FHA single-family policy.
The appraisal feeds this step. On a 2-4 unit, the appraiser’s market-rent figures drive both rental income and the self-sufficiency check. A low rent estimate can shrink your qualifying income or fail the test outright. Lendmire’s piece Can a House Hacker’s 2-4 Unit FHA Loan Survive Appraisal Problems? walks through that risk.
Where the General Rule Breaks
The unit-count table is the starting point. These cases bend it.
Manual versus automated underwriting. The one-month duplex rule belongs to manual underwriting. Most files run through the automated finding, which governs most files. If a file gets pushed to manual review, the reserve answer can change.
High ratios and compensating factors. The base ratio pair is 31/43 (housing over total) with no compensating factors. Documented factors can stretch that toward 40/50 at the top tier. Reserves are one of the factors lenders look at when a file is stretched, so a thinner cushion makes a stretched file harder. For more on that side, see Lendmire’s article on whether a house hacker with a high DTI can get an FHA loan on a 2–4 unit: Can a House Hacker With a High DTI Get an FHA Loan on a 2–4 Unit?.
The accessory dwelling unit. A one-unit home with an ADU carries a two-month requirement, but only when you use the ADU’s rent to qualify. Skip the rent as income and that trigger goes away.
Non-occupant co-borrowers. FHA allows a non-occupant co-borrower on these loans. Treat that as a question to put to your lender.
Five or more units. These fall outside single-family FHA financing. HUD runs separate multifamily programs for them, so a five-unit building is a different conversation.
Old guidance. Articles from several years back describe different compensating-factor reserve rules. They are outdated. HUD’s handbook is updated several times a year, so HUD’s FHA INFO page is the place to check for current changes.
Lender overlays. A lender may ask for more than HUD’s baseline. This varies by lender, so get the requirement in writing early.
What the Decision Looks Like in Practice
The practical question is not “does FHA require reserves?” It is “how much cash do I need in total, and in what order?”
Stack it the way the underwriter does. First comes your 3.5% minimum investment. Next come closing costs and prepaids, which seller or interested-party contributions can offset up to 6% of the price. Then comes the reserve cushion, in your own verified funds.
Say you are comparing a duplex and a fourplex at similar prices. The fourplex may bring more rent, but it also brings three months of reserves and the self-sufficiency test. The duplex asks for less cash after closing. For a first house hack, that gap can decide which building makes sense.
If you come up short, there are a few honest options:
- Aim at a lower price or a smaller unit count.
- Ask about seller contributions toward closing costs, which frees your own cash for the cushion.
- Keep building savings and re-run the subtraction.
- Use gift money for the down payment and keep your own savings for reserves.
Also separate the FHA reserve number from your own landlord buffer. A new owner-occupied fourplex will have repairs and a vacancy sooner or later. The requirement is a minimum for the file, not a plan for the building.
Key Terms Defined
Reserves: Verified liquid assets left after you pay your down payment, closing costs, and prepaids.
PITI: Principal, interest, property taxes, and homeowners insurance. This is the monthly payment used to count months of reserves.
Self-sufficiency test: A separate check on three- and four-unit homes. It tests whether the property’s projected rent covers the full payment after an allowance for vacancy and upkeep.
Manual underwriting: A file reviewed by a person rather than cleared by the automated finding. Reserve rules can differ here.
Seasoning: How long funds have sat in your account. Recent deposits usually need an explanation.
Compensating factors: Documented strengths, such as savings, that let a file carry higher ratios.
Frequently Asked Questions
Does FHA require reserves on a duplex?
Usually not as a blanket rule on a standard automated file. The one-month requirement sits in HUD’s manual-underwriting section, so it applies if your file is reviewed that way. A lender can also ask for documented assets for other reasons. Ask early which path your file takes.
Can gift money count as my reserves?
No. Gift funds can help with your down payment and closing costs, but HUD’s letter excludes them from reserves. The cushion has to come from your own verified liquid funds.
Does rental income lower the reserve requirement on a fourplex?
No. Rent can help your debt-to-income ratios and the self-sufficiency test, but the three-month requirement stays the same. It is a separate measure of your savings after closing. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Can I use equity in my current home as reserves?
No. HUD excludes equity in another property. Reserves have to be liquid assets you can document, such as account balances.
Are the reserve rules the same as a few years ago?
Not necessarily. HUD updates its handbook several times a year and folds earlier letters into it. Check current guidance, and ask your lender for its requirement in writing.
If you are buying a home and want to see whether an FHA loan fits your file, Lendmire can help you compare the options and what each one asks of the file. Program details are subject to lender guidelines and full file review, and nothing here is a commitment to lend.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage serving homeowners and home buyers in 16 states. FHA, VA, conventional and jumbo purchase and refinance loans are arranged through wholesale lending channels; Lendmire brokers the financing and the lender underwrites each application. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. HUD Mortgagee Letter 2023-17
2. HUD Single Family Housing Policy Handbook 4000.1
This article is part of Lendmire’s FHA loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: FHA Loan Guidelines on a 2-4 Unit Home You Live In · Is an FHA Loan Still the Right Choice for House Hacking? · VA Loan vs FHA Loan for a Veteran House Hacking a 2-4 Unit
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.