
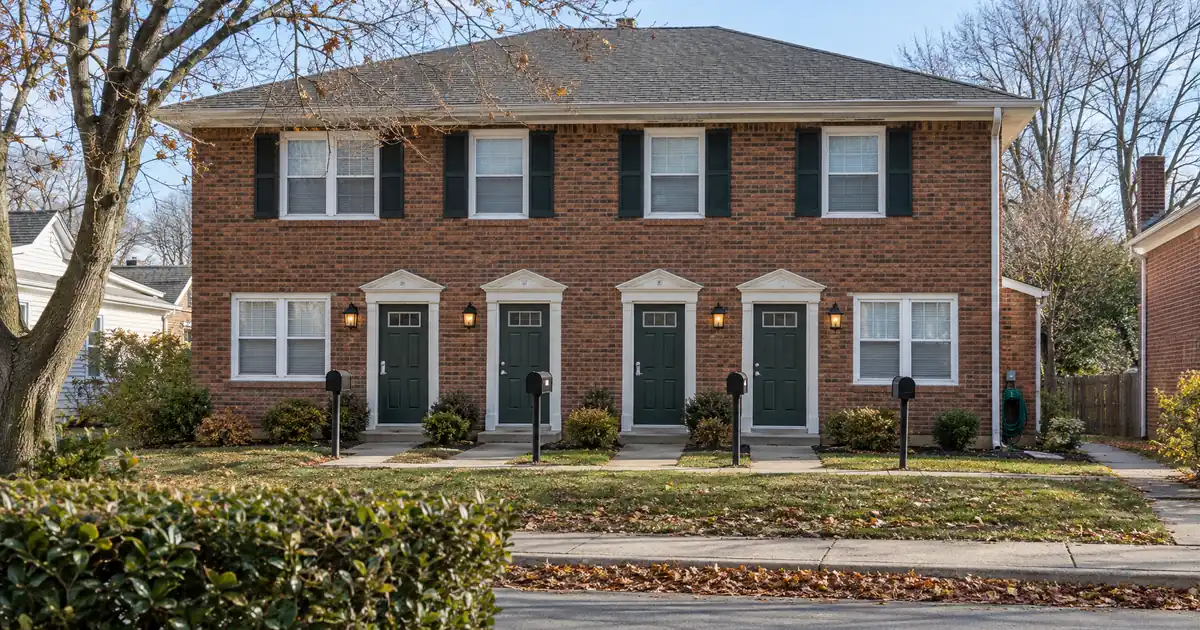
The Quick Read: A DSCR loan finances a fourplex you plan to rent out entirely. It qualifies primarily on property-level rental income covering the payment, subject to lender guidelines. FHA does the opposite: it requires you to live in one unit and holds the building to a stricter rent test. The deciding question is simple: will you live there, or will you only own it?
- Occupancy decides the product. Live in one unit and FHA is on the table. Rent all four and you are in DSCR territory.
- Leverage on a purchase: most files land at 75%-80% LTV (20%-25% down). Select high-leverage programs reach 85% LTV with roughly a 700+ score.
- Coverage: 1.00 is where many select programs start. A separate select-lender path takes coverage below 1.00, with leverage and terms adjusted.
- Credit: a 620 floor exists in parts of the network. Most programs want about 660, and 700+ unlocks the strongest leverage tiers.
- Reserves: commonly around 6 months of PITIA, the full monthly payment including taxes and insurance. This varies by lender, leverage, and loan size.
Can a DSCR Loan Finance a Fourplex?
Yes, with a clear boundary. A fourplex is the largest building that still gets residential-style underwriting. DSCR stands for debt service coverage ratio, which is monthly rent divided by the full monthly payment. On a fourplex, the rent from all four units goes into that calculation.
DSCR Calculator
Run the numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 29, 2026
Prefilled with starting assumptions — enter your own rent or nightly figures, taxes, insurance, and HOA for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 29, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Rent, nightly rate, occupancy, taxes, and insurance are editable estimates. Short-term rental figures are estimates only and vary significantly by season, property type, management approach, and local short-term-rental rules — confirm local regulations before relying on them. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Five or more units move toward commercial underwriting. There, lenders usually look at net operating income, not a simple rent-to-payment ratio. Four units is the ceiling for the approach here.
DSCR loans are non-owner-occupied products. You cannot live in the building. Do it anyway and you are breaching the loan terms.
Why FHA Doesn’t Fit a Pure Rental Fourplex
FHA is owner-occupant financing. It covers one-to-four-unit homes, but you must live in the property as your primary residence. The occupancy certification you sign at closing is not a formality. Misstating it is a serious problem.
That does not make FHA a bad tool. It is a strong one for the right buyer. The “house hack” works like this: you buy a fourplex, live in one unit, and rent the other three. The down payment is far lower than on an investor loan.
The catch is that the building must clear FHA’s rules, and you must actually live there. An investor buying a fourplex through an LLC to rent all four units does not fit. Neither does an investor adding a second or third building. FHA was never built to scale a portfolio.
After the occupancy period, an FHA owner can move out and rent every unit. That is a house hack maturing. It is not an investor acquisition.
FHA vs. DSCR on a Fourplex
| Factor | FHA (owner-occupied) | DSCR loan |
|---|---|---|
| Occupancy | You live in one unit | You cannot live there |
| Who is underwritten | Your income, debts, and the building | The property’s rent vs. payment |
| Down payment | Very low | Typically 20%-25% on a purchase |
| Buying in an LLC | Not a fit | Possible, subject to program terms |
| Tax returns and W-2s | Required | Not the basis of qualification |
| Repeat purchases | Limited | Each file stands on its own property |
FHA also caps loan size by county. The four-unit limits run from a floor near $1,041,125 to a ceiling near $2,402,625, depending on local costs. DSCR files have no FHA county limit. Across the wholesale network, standard programs go up to $3,000,000, with lender-set maximums by program.
Here is how that plays out by buyer:
| Your situation | Likely fit |
|---|---|
| You will live in one unit | FHA house hack |
| You will rent all four units | DSCR loan |
| You already own several rentals | DSCR loan |
| You will move out after a year or so | FHA first, DSCR refinance later |
How FHA Counts the Rent (and Why Fourplexes Struggle)
FHA does not take your word for the rent. On 2-4 unit properties with no rental history, HUD’s Mortgagee Letter 2023-17 has the lender count 75% of the lesser of the appraiser’s fair market rent or the actual lease rent.
Three- and four-unit buildings face a second test, the self-sufficiency test. The building’s net rent, after a vacancy and maintenance haircut, has to cover its own mortgage payment. Duplexes skip it.
This is where fourplexes in expensive areas often stall. When purchase prices are high compared with rents, the haircut leaves too little coverage. The fix is a smaller loan, which means more cash from you.
FHA also still reviews your personal income and debts. A strong building does not replace a thin personal file. Have a lender run the exact worksheet against HUD’s current handbook before you rely on it.
How a DSCR File Counts Four Units
The mechanics run in a fixed order.
1. The appraiser values the building and reports market rent. On a 2-4 unit property, the appraisal comes with a rent schedule. The appraiser’s form names (1025 for 2-4 units, 1007 for single-family) are borrowed by DSCR lenders. Agency rules do not govern the loan itself.
2. Each unit is rated on its own. The lender looks at lease rent for occupied units and market rent for vacant ones. The totals become gross rent for the building.
3. The lower figure usually wins. When a lease sits below market, the lender often uses the more conservative number. Rent-controlled or below-market leases can drag the coverage number down. Extras like pet fees, parking, or utility reimbursements are often left out.
4. The lender divides rent by PITIA. That is principal, interest, taxes, insurance, and any association dues. The result is the rent-to-debt ratio.
5. The ratio sets the options. Most programs want a ratio at or above 1.00. A stronger ratio opens better pricing and higher leverage. Coverage below 1.00 is available through select lenders in the network, with leverage and terms adjusted.
Notice what is missing: no traditional personal-income documentation, no pay stubs, no debt-to-income test. The file stands on the property’s income, though credit, reserves, and the appraisal still matter.
Mixed-use buildings need care. Commercial space sits outside the residential rent method, so only the residential units count.
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage. Federal rulemaking treats investment-purpose loans as business-purpose credit. That is the reason these loans do not need to be tested against your personal income.
What Happens When One Unit Goes Vacant
A fourplex spreads risk across four leases, so one empty unit does not stop the building. It still moves the numbers.
Run it with a modeled assumption: four equal rents and a building that clears about 1.25x. Lose one unit’s rent and the same building sits near 0.94x. That is a quarter of the rent gone, so the ratio falls by a quarter.
Underwriting and real life treat this differently. Many programs count market rent on a vacant unit, so the paper ratio may not change. Your bank account notices the empty unit anyway. Stress-test the building yourself with one unit dark before you commit.
Also compare leases to market rent unit by unit. A single-family house either rents or it does not. A fourplex can hide a below-market unit that pulls the whole ratio down.
Passing the Ratio Is Not the Same as Making Money
Clearing 1.00 does not mean positive cash flow. This is the most common misread of DSCR loans.
The ratio compares rent to PITIA and nothing else. It ignores repairs, vacancy, management, utilities, and capital expenses like roofs and boilers. A fourplex has four kitchens, four sets of appliances, and often shared systems. Those costs are real, and the lender does not count them.
A building at 1.10x can clear the lender’s test and still run thin once you pay for maintenance and a property manager. Build your own budget on top of the loan math. Tax treatment varies; consult a qualified professional.
(The honest benchmark is the number you would want even if the lender asked for less.)
What Qualifies: The Network’s Typical Ranges
These are typical ranges from select lenders in Lendmire’s wholesale network. They are not guarantees, and every file is underwritten individually.
- Purchase leverage: most files land at 75%-80% LTV, meaning 20%-25% down. Lenders can adjust leverage by property type and unit count.
- Cash-out refinance: tops out around 75% LTV on a standard rental, with about 6 months of seasoning as the common expectation.
Sub-1.00 files are available through select lenders, with leverage and terms adjusted. No-ratio structures exist only through select lenders, generally for borrowers who already own a primary residence.
- Credit: a 620 floor exists in parts of the network, most programs want about 660, and 700+ unlocks the strongest tiers.
- Loan size: up to $3,000,000 on standard programs.
- Reserves: commonly around 6 months of PITIA. Conservative rate-and-term files at modest leverage under $1,500,000 can see reserves waived. Loans above that size typically step up to about 9 months.
- Structure: the spine is the 30-year fixed. Extended terms and interest-only periods are available through select lenders, and ARM structures exist for investors who want them.
A bigger down payment lowers the payment and can lift the coverage number. It does not erase leverage caps, credit floors, or reserve rules. The strongest files clear both tests: enough equity and enough rent.
Manufactured homes, log homes, and barndominiums are not offered through these programs. A standard fourplex of conventional construction is the target.
The complete DSCR loans guide covers the full program in more depth.
Step by Step: Financing Your Fourplex
1. Decide your occupancy. If you will live in a unit, stop here and look at FHA. If you will not, continue.
2. Pull a quick coverage estimate. Add the realistic rents of all four units. Estimate the full payment, including taxes and insurance. Check the ratio against 1.00 and against a one-vacancy version.
3. Choose your entity. Closing in an LLC is available on many files, subject to lender program eligibility. Talk to the broker before you sign a purchase contract.
4. Gather the basics. Expect leases and a rent roll, an ID, proof of reserves, an insurance quote, and a property address and purchase contract. No pay stubs or tax returns are the basis of qualification.
5. Get matched to lenders. A broker compares guidelines across multiple lenders, since leverage, reserves, and credit overlays differ.
6. Order the appraisal. The appraiser reports value and per-unit market rent. The lender’s rent figure comes from this report.
7. Clear conditions and close. Respond to lender questions, confirm reserves, and sign. DSCR loans are business-purpose and exempt from the consumer disclosure timelines that apply to a standard owner-occupied mortgage.
If You Started With FHA
Plenty of investors start with an FHA house hack and move to DSCR later. You buy, live in one unit, and then move out after the occupancy period.
At that point the building is an investment property. A DSCR refinance can replace the FHA loan, and it can pull equity for the next purchase. A cash-out refinance tops out around 75% LTV on a standard rental, with about 6 months of seasoning the common expectation. The rent coverage and credit tests apply as with any other DSCR file. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Plan the exit before you buy. Check whether the building’s rents would clear coverage as a pure rental, not just as a house hack where your own unit is part of the picture. For homeowners weighing a similar move, see Lendmire’s piece Should a Lock-In Homeowner Tap a Rental Instead of an FHA Cash-Out?.
If the Ratio Comes Up Short
Four levers exist, and none is magic.
- Put more down. A larger down payment lowers the payment and can lift coverage. It will not get around credit floors or leverage caps.
- Adjust the structure. Interest-only periods and extended terms are available through select lenders and can lower the monthly obligation.
- Revisit the rent. Verify that leases reflect current market rent. A below-market lease may be fixable at renewal.
- Look at sub-1.00 options. Select lenders in the network take coverage below 1.00, with leverage and terms adjusted.
The simplest lever is the oldest one: pick a different building. A lower price per unit often changes the ratio more than any loan feature.
Key Terms Defined
DSCR (debt service coverage ratio): Monthly rent divided by the full monthly payment on the property.
PITIA: Principal, interest, taxes, insurance, and any association dues, the full payment the rent has to cover.
Non-owner-occupied: A property you own but do not live in as your home.
Market rent: What an appraiser says a unit would rent for today, which may differ from the lease.
Self-sufficiency test: FHA’s check that a three- or four-unit building’s net rent covers its own payment.
Seasoning: The waiting period a lender wants after you buy before it will refinance.
Reserves: Cash you keep after closing, usually counted in months of PITIA.
Frequently Asked Questions
Can I live in one unit of a DSCR-financed fourplex?
No. DSCR loans are for non-owner-occupied investment property, and living in a unit breaks that. If you plan to live there, FHA or another owner-occupied program is the right tool. Once you move out, a DSCR refinance becomes possible.
Is a fourplex treated as residential or commercial?
Residential, as long as it has four units or fewer. The lender uses a rent schedule and a simple rent-to-payment ratio. At five units and up, underwriting shifts toward commercial and net operating income.
Can I use FHA to buy a fourplex I will rent out?
Not as a pure rental. FHA requires you to occupy one unit as your residence. After the occupancy period you can move out and rent all four, but that is a house hack ending, not an investor purchase.
How much do I need down on a fourplex?
On a purchase, most files land at 75%-80% LTV, which means 20%-25% down. Lenders can adjust leverage by property type, so confirm for a specific building.
What if my coverage is below 1.00?
Options exist. Sub-1.00 coverage is available through select lenders in the network, with leverage and terms adjusted. A larger down payment or a different structure may also help. Eligibility review depends on credit, reserves, and the property review.
Where to Go From Here
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. As a broker, Lendmire arranges financing through select lenders in its wholesale network across 41 markets, including Washington, D.C. Not a commitment to lend. Compare your building to FHA before you sign, because the right loan is the one that matches how you will actually own it.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, a fit for self-employed investors and LLC-owned portfolios.
Scotsman Guide named Lendmire a Top Mortgage Workplace in 2026.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. AirDNA: FHA loan for investment property
2. Scotsman Guide: HUD FHA and HECM loan limits
3. HUD Mortgagee Letter 2023-17
4. Federal Register: Ability-to-Repay and Qualified Mortgage Standards
This article is part of Lendmire’s DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How a DSCR Loan Works on 5-10 Units Instead of a Bank Loan · How a DSCR Loan Works on an Edgartown Rental · How a DSCR Loan Works for a Sandusky Seasonal Rental
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.