
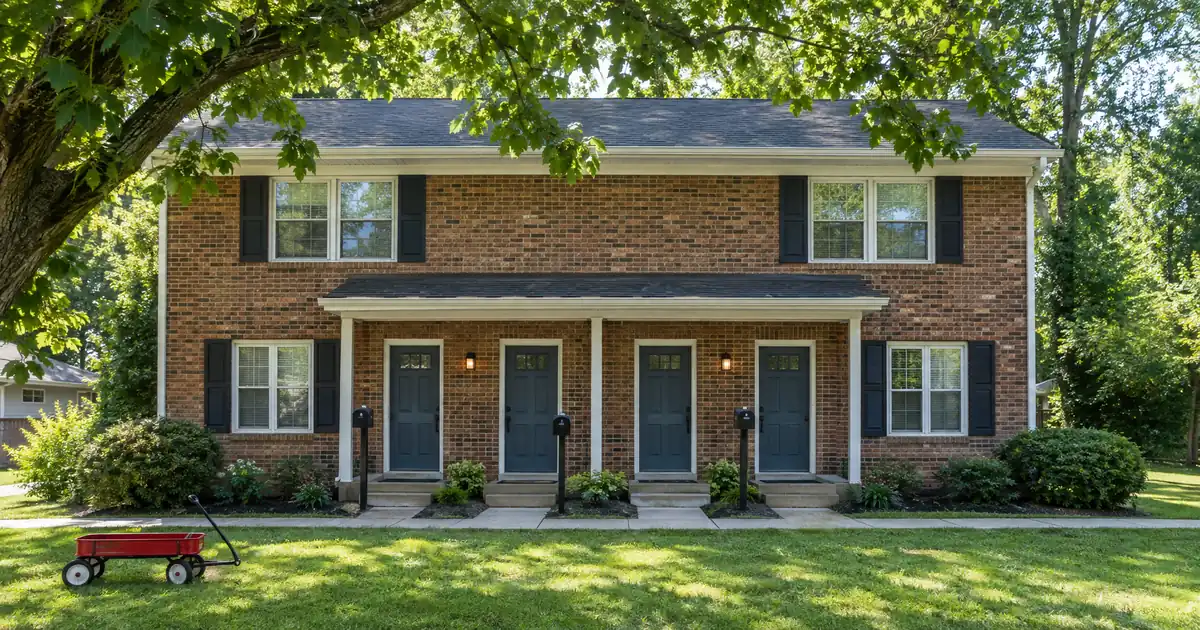
The Quick Read: A jumbo DSCR loan tests the fourplex’s rent against the full housing payment, while a bank statement loan tests the borrower’s deposits against total debts. The choice usually turns on occupancy first, then on which side of the file is stronger. A pure rental often fits DSCR. An owner-occupied fourplex cannot use DSCR at all.
- Occupancy decides the lane. Living in one unit makes the file owner-occupied, which takes DSCR off the table.
- DSCR tests the building. Rent from all four units is weighed against principal, interest, taxes, insurance and any HOA dues.
- Bank statement tests you. Twelve months of deposits become qualifying income, and every other debt stays in the ratio.
- “Jumbo” is a size label. It describes the loan balance, not a separate product.
- Both are alternative-documentation loans. Neither is a “no documentation” loan, and both are subject to lender guidelines.
The honest answer on who each option is for: the DSCR loan suits an investor buying a fourplex purely as a rental, especially a self-employed one whose tax returns understate real income. The bank statement loan suits a borrower who will live in one unit, or whose deposits are strong and whose other debts are light. An investor who fits both can usually pick the test the file passes more comfortably. Lendmire arranges both through select lenders in its wholesale network, so this comparison is about fit, not a sales pitch for one side. The complete DSCR loans guide covers the investor side in more depth.
What your deposits qualify you for.
Alt-doc programs read 12 months of business or personal bank deposits instead of tax returns. Enter your average monthly deposits and see the income a lender would credit you.
The expense factor is set by the lender from your business type and profit-and-loss statement; it is not a number you choose. This widget quotes no rate and no payment.
Program parameters shown update from Lendmire’s centralized guideline source.
Estimate
Illustrative estimate only — not a quote, Loan Estimate, approval, or commitment to lend. Deposit average, expense factor, and housing ratio are editable assumptions; the expense factor a lender applies is set from your business type and documentation. No interest rate or monthly payment is quoted here. Purchase capacity is a simplified illustration and does not account for taxes, insurance, HOA dues, or other debts. Alt-doc income documentation is available on consumer mortgages in the states where Lendmire is licensed for consumer lending; actual terms vary by lender, borrower, and property.
Side-by-Side
The column for the bank statement loan reflects published industry norms and the way most programs in the network treat these files. Specific terms follow each lender’s program sheet.
| Factor | Jumbo DSCR Loan | Bank Statement Loan |
|---|---|---|
| What is tested | Property rent vs. full housing payment | Borrower deposits vs. total debts |
| Review basis | Rental income, subject to lender guidelines | Documented income under the applicable program |
| Core documents | Leases or rent schedule, appraisal, entity papers | 12 months of statements, deposit explanations |
| Occupancy | Non-owner-occupied only | Owner-occupied; some programs allow investment |
| Personal DTI | Generally not the deciding test | Every debt stacks into the ratio |
| Entity vesting | Commonly an LLC, per program guidelines | Usually personal name |
| Reserves | Typically required; varies by lender | Commonly around 6 months of housing payment |
| Disclosure regime | Business-purpose, TRID-exempt | Consumer mortgage if owner-occupied; TRID applies |
| Typical failure point | Thin rent or a vacant unit | Heavy debt load or unexplained deposits |
What “Jumbo” Means on a Fourplex
A fourplex loan is jumbo only when the balance exceeds the conforming limit for four-unit properties in that county. FHFA’s conforming loan limit addendum sets the baseline limits at $1,066,250, $1,288,800 and $1,601,750 for two-, three- and four-unit properties. In high-cost areas the limit is built from 115 percent of the local one-unit median home value, multiplied by the unit factors.
Two points follow for a fourplex buyer. The four-unit limit is much higher than the one-unit number, so many fourplex loans are not jumbo at all. And once a balance does cross the local limit, the borrower is in a non-agency lane no matter what. The real question then becomes which alternative-documentation test fits the file.
Network programs for alt-doc files run from roughly $125,000 to $3,500,000, so most fourplex balances fit. Larger balances tend to draw tighter credit and reserve expectations, which varies by lender.
When a Jumbo DSCR Loan Is the Better Fit
DSCR is the stronger choice when the building carries the file. Picture an investor buying a fourplex with four leased units and no plans to live there. The lender sums the rent from all four units, whether from leases or the appraiser’s market rent, and tests it against the full housing payment. If the ratio clears the program’s floor, personal income and other mortgages are not the deciding test.
That structure helps in three situations:
- Portfolio growth. Each new payment does not stack into a personal debt ratio, so the tenth rental is not blocked by the ninth.
- Heavy write-offs. A self-employed investor with large deductions may show low taxable income. DSCR looks past that.
- Entity ownership. Closing in an LLC is common on DSCR files, subject to lender program eligibility.
The failure modes are mechanical. Rent comes in low at appraisal. One unit sits vacant and the appraiser’s market rent is lower than hoped. The lease files are incomplete, so a unit has no evidence behind its rent. Insurance quotes land late and change the payment. Clean lease evidence and a current insurance quote prevent most of these.
Coverage is also not cash flow. The ratio does not account for vacancy, repairs or management, so a fourplex that clears the floor can still run tight in practice.
Many programs want coverage at or above 1.00x, but select lenders in the network do offer sub-1.00 programs. Leverage and terms adjust when coverage runs below 1.00x. Qualification always depends on credit, reserves, the property and lender guidelines.
When a Bank Statement Loan Is the Better Fit
A bank statement loan is the better fit when the borrower will live in the fourplex, or when the borrower’s income is strong and well documented. The lender reviews 12 months of personal or business statements, totals the eligible deposits and removes transfers, refunds and one-off deposits. Business accounts get a lender expense factor applied. Personal-account deposits are often counted more fully. The result is qualifying income under the applicable program.
On a primary residence, select lenders allow up to 90% LTV on a purchase or rate-term refinance. That matters for a house-hack buyer who occupies one unit and rents three. Stronger files earn the top of the range. An asset-depletion alternative, qualifying from liquid assets, runs to about 80% LTV on a primary residence.
Cash-out is different. On a primary residence, cash-out tops out at 80% LTV with a fixed expense ratio, or 75% with an accountant-prepared ratio. On a second home it is up to 75% LTV. On an investment property, bank statement cash-out tops out around 75% LTV. Investment purchase leverage on bank statement documentation varies by lender, so treat it as a conversation, not a number.
The weak points are on the borrower’s side. Every existing debt stays in the ratio, so a fourplex payment stacks on top of current mortgages. Deposits that cannot be explained get removed. Thin or irregular statements shrink qualifying income. At jumbo balances, the new payment is large, and it crowds the ratio fast.
The related Lendmire piece on whether a spouse’s income helps on a super jumbo bank statement file covers that side of the file.
The Owner-Occupancy Line (the Sharpest Fourplex Trap)
This is where investors misjudge their own deal. One resident unit makes the loan owner-occupied. DSCR is built for non-owner-occupied investment property. Living in one unit and counting on tenants to cover the rest does not move the file back into DSCR.
The same logic shows up in federal rules. Regulation Z’s exempt-transaction rule says a property cannot be treated as non-owner-occupied if the owner expects to occupy it for more than 14 days in the coming year. Investment-purpose loans are treated as business-purpose and fall outside the consumer ability-to-repay rules. That is why a non-owner-occupied fourplex on DSCR is a business-purpose loan, while an owner-occupied one is a consumer mortgage with TRID disclosures.
Practical result: an owner-occupied fourplex goes to a bank statement or other owner-occupied program. A pure rental can go either way. Occupancy settles the lane before any math runs.
Entity, Documents and Reserves
Entity. DSCR files commonly close in an LLC, subject to lender program eligibility. Bank statement loans are usually vested in a personal name. If an investor wants LLC title on a fourplex, that points toward DSCR.
Documents. DSCR leans on property papers: leases or a rent schedule, the appraisal, entity documents, asset and reserve statements, insurance and a credit report. Bank statement files lean on borrower papers: 12 months of statements, deposit explanations and proof of business ownership.
Reserves. Both sides want cash left over after closing. Bank statement reserves commonly run around 6 months of the housing payment. DSCR reserve expectations vary by lender and leverage. Reserves documentation, meaning statements that show the funds are seasoned and accessible, is one of the quiet items that slows files on both sides.
Using Both Over Time
The two loans are not rivals across a whole portfolio. A common sequence: a self-employed investor buys a primary home on a bank statement loan, then buys rentals on DSCR so the new payments stay out of the personal debt ratio. Another sequence runs the other way. An investor house-hacks a fourplex on bank statement documentation, then moves out and buys the next building on DSCR.
If neither fits, say because rent is thin, one unit is vacant and the numbers fall short, the options are lower leverage, more cash down, a sub-1.00 program with adjusted terms, or a different property. Each is subject to lender guidelines.
Key Terms Defined
- DSCR (debt service coverage ratio): Monthly rent divided by the full monthly housing payment, including principal, interest, taxes, insurance and any HOA dues.
- Bank statement loan: A loan that qualifies the borrower on deposit averages from 12 months of statements instead of tax returns.
- Jumbo: A loan balance above the conforming limit for that property type and county.
- Non-QM: A loan that uses alternative documentation instead of standard tax-return and W-2 underwriting.
- Expense factor: The percentage a lender subtracts from business deposits to estimate usable income.
- Business-purpose loan: Credit for an investment or commercial purpose, reviewed differently from a standard owner-occupied mortgage.
The Verdict
Run the occupancy test first. If you will live in the fourplex, bank statement or another owner-occupied program is the path. If you will not, compare the two tests on the same deal. DSCR wins when rent is strong, the entity matters, or personal debt would crowd the ratio. Bank statement wins when deposits are strong, debts are light and the property’s rent is not the selling point. Many self-employed investors will find both work, and the stronger file decides.
If you are self-employed and want to see how the numbers work, Lendmire can help you compare bank statement loan options and DSCR structures based on your deposits, the property, credit profile, leverage and your goals. Reach the team at 828-256-2183 or request a quote. Any illustrative calculator estimate is not a quote or a commitment to lend.
Frequently Asked Questions
Can a bank statement loan finance a fourplex?
Yes, in most cases when the borrower will live in one unit. Select lenders also allow bank statement documentation on investment property, but leverage varies by lender. Loan sizes in the network run from roughly $125,000 to $3,500,000, subject to lender guidelines and credit approval.
Does DSCR count rent from all four units?
Yes. Rent from each unit, by lease or by appraiser market rent, is added up and tested against the full housing payment. The aggregate is what matters, not any single unit. A vacant unit is counted at appraiser market rent.
Do my other mortgages affect each loan?
On a bank statement loan, yes. Every existing debt and the new payment go into the debt ratio. On DSCR, personal debt ratios are generally not the deciding test, though credit and reserves are still reviewed.
Can I buy in an LLC?
DSCR files commonly allow LLC vesting, depending on program guidelines. Bank statement loans are usually in a personal name. If entity title matters for liability planning, raise it before choosing a lane.
What if one unit is vacant?
On DSCR, the appraiser’s market rent stands in for the empty unit, so the file can still be tested. Lower-than-expected market rent can pull the ratio down. On bank statement, the vacancy matters only through the borrower’s overall income and debts.
Can I live in one unit and still use DSCR?
No. Any resident unit makes the loan owner-occupied. DSCR is for non-owner-occupied investment property only. A house-hack buyer should look at a bank statement or other owner-occupied program instead.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage serving self-employed and high-net-worth borrowers in 16 states. Bank statement, P&L-only, 1099-only and asset-based mortgages are arranged through wholesale lending channels; Lendmire brokers the financing and the lender underwrites each application. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. FHFA – 2026 Conforming Loan Limit Addendum
2. CFPB – Regulation Z § 1026.3 Exempt transactions
This article is part of Lendmire’s bank statement loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How to Plan and Use a Bank Statement Cash-Out Refinance for Repairs Without a Contractor · How to Plan and Use a Super Jumbo Bank Statement Cash-Out Refinance for Down Payment · How Lenders Underwrite a Bank Statement Cash-Out Refinance Above the Conforming Loan Limit
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.