Does An Unsourced Large Deposit Disqualify A P&L Loan File?
An unsourced large deposit does not automatically disqualify a P&L loan file.

 Lendmire Research
An unsourced large deposit does not automatically disqualify a P&L loan file.
A ratio of 1.00 means the rent covers the payment exactly; above 1.00 means it covers with room to spare.
Lenders skip your K-1, your tax returns, and your W-2 entirely.
What Asset-based Borrowers Submit For A Vacation Rental DSCR Loan: what investors need to know about large-balance DSCR financing, from Lendmire.
Loan sizes on this collateral type generally cap near $2,000,000, with leverage, credit floor, and reserve requirements shifting as the loan amount climbs.
Coverage at 1.00 or better earns full leverage; select programs allow lower coverage or no-ratio qualification up to $2,000,000, at reduced leverage.
A stronger, well-documented income number produces a higher coverage ratio, and a higher coverage ratio is what lets a lender extend more leverage.
The fix is usually a short letter plus supporting documents, timed well before the file goes to underwriting.
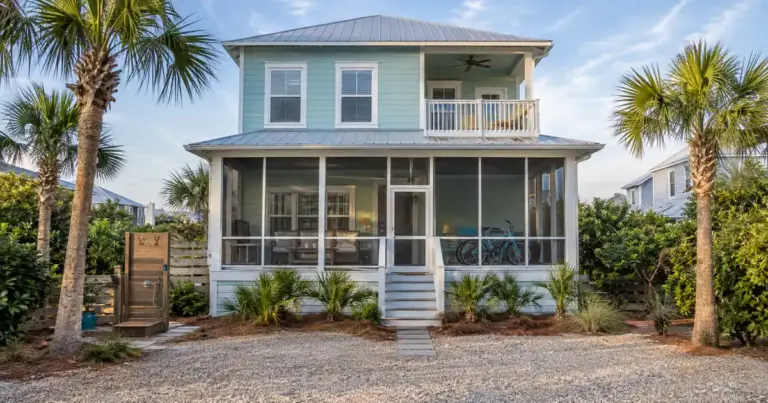
Add entity paperwork if you’re vesting in an LLC, credit and reserve documents, and standard purchase or refinance paperwork, and that’s the whole list.
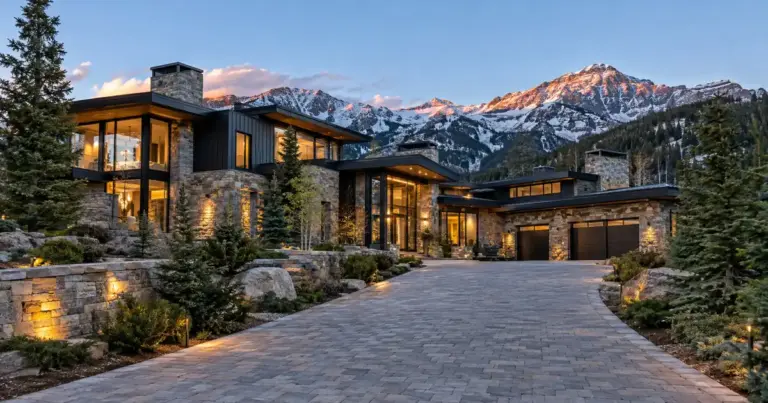
Short-term-rental income itself only qualifies up to $2,000,000; above that, the file has to lean on long-term market rent instead of nightly bookings.
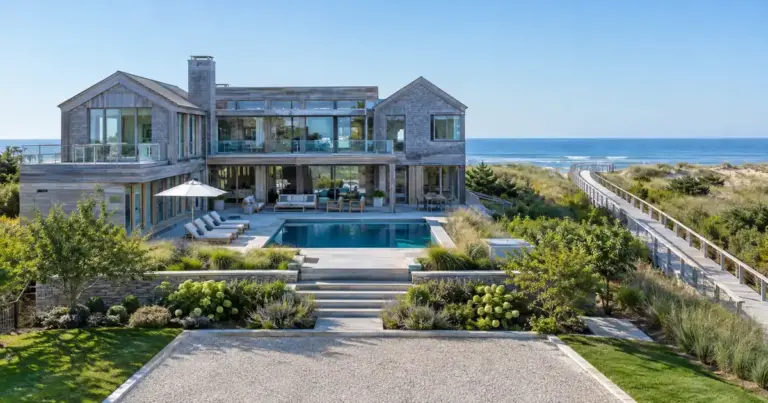
On files above $2,000,000, expect two appraisals instead of one.
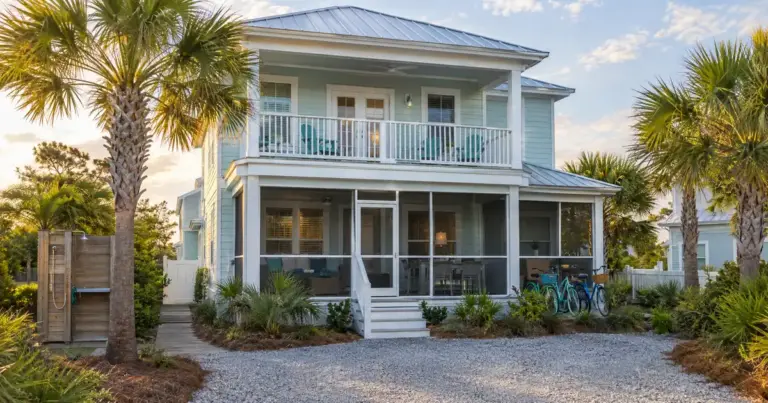
Coverage of 1.00 or better earns full leverage; select programs also allow coverage below 1.00, though leverage and terms adjust to compensate.
Document A Large Deposit On A Bank Statement — Lead with the paper trail.
Super Jumbo Bank Statement Loan Tiers Above The Jumbo Line — Once a loan amount clears the conforming limit, it becomes jumbo.
A first-time landlord can still get approved, subject to lender guidelines, but the path gets narrower the bigger the loan gets.