Cash First Vs Financed At Closing On A Retiree Rental Loan
Financing at closing skips that cap and starts the loan on day one, priced off the property’s rental income instead of Social Security or pension paperwork.

 Lendmire Research
Financing at closing skips that cap and starts the loan on day one, priced off the property’s rental income instead of Social Security or pension paperwork.
Ski Cabin Vs Beach House — Neither wins outright.
If your write-offs are heavy but legitimate, P&L usually shows more usable income.
Trust titling adds an estate-planning layer — mainly probate avoidance — without changing how a DSCR loan gets underwritten or how rental income gets taxed.
Beach House DSCR Vs Asset Depletion For A Retiree — DSCR loans qualify the property; asset depletion qualifies the person.
Both are business-purpose loans that qualify primarily on the property’s rental income rather than personal tax returns.
Reserves, credit, and entity structure stay the same regardless of who runs the calendar.
Financing at closing gets the loan underwritten before the trustee signs, income documented up front, and leverage locked in on day one.
Managed Vs Co-hosted Luxury Rental — Neither model wins on its own.
The real difference is paperwork and building risk.
Neither choice changes how a DSCR loan gets underwritten, since qualification runs on the property’s rental income either way.
This article treats the loan question and the tax question as two separate decisions, because they are.
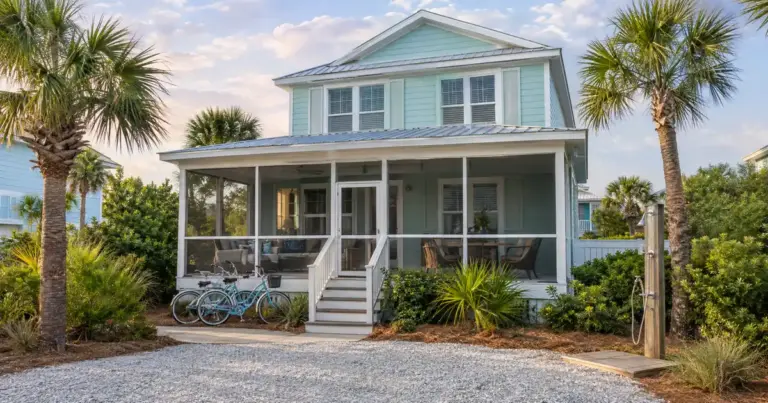
Rent analysis is a projected figure — usually an appraiser’s short-term-rent estimate — used when a property has no operating track record yet.
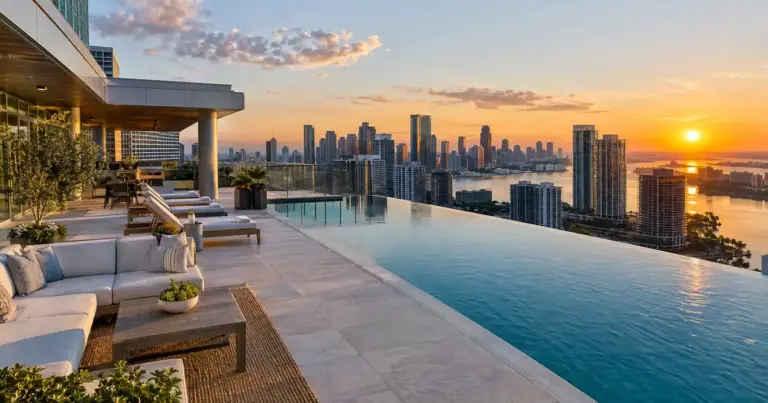
The condo adds a project-level review of the homeowners association — litigation, reserves, delinquencies — that a detached house never faces.
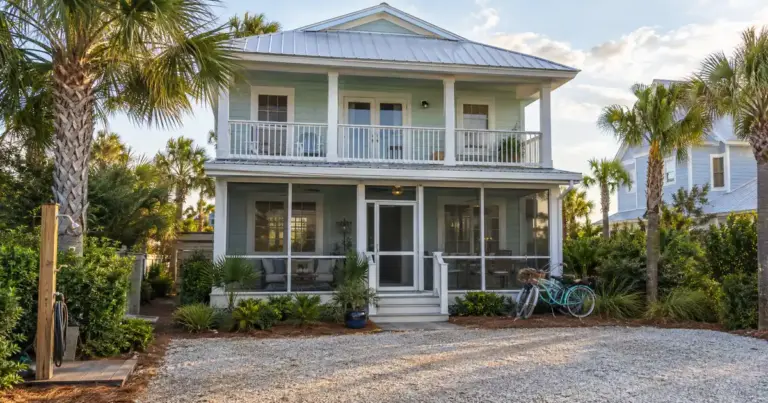
Below the ceiling, leverage runs higher and documentation is lighter.