Asset Depletion Mortgages In Sea Island: Assets, Not Income
Asset Depletion Mortgages In Sea Island — Asset depletion is a qualification method, not a separate loan product.

 Lendmire Research
Asset Depletion Mortgages In Sea Island — Asset depletion is a qualification method, not a separate loan product.
Nothing gets sold, pledged, or locked up; the assets stay exactly where they are.
Underwriters look at deposit history instead of a rent roll, and leverage steps down as the loan size climbs.
Leverage steps down as the loan gets larger, reserves step up, and above roughly $3.5 million to $4 million every file moves to case-by-case underwriting.
Luxury Rental DSCR Loans In Martha’s Vineyard — Lenders don’t take your Airbnb listing price times 365 nights.
Super Jumbo Bank Statement Loans In St. Simons Island: what borrowers need to know about high-net-worth bank-statement financing, from Lendmire.
Asset Depletion Loans In St. Simons Island: Qualifying On Assets Alone — what borrowers need to know, from Lendmire.
Second-Home Financing In Sea Island — A true second home means the owner or a family member actually uses the property.
Underwriters average 12 or 24 months of bank statements, apply an expense factor to business deposits, and size leverage down as the loan gets bigger.
It exists for people whose tax returns understate their real financial strength — retirees, sold-business owners, and high-net-worth investors.
There’s no federal definition of “super jumbo” — it’s a lender overlay, not a regulation.
Leverage steps down as the loan gets bigger — often starting near 90% on smaller files and falling into the 55%-65% range above $4,000,000.
Long-term rent is set by an appraiser, not a listing site. Short-term rent gets discounted before it ever touches the ratio.
Luxury Rental DSCR Loans In Nantucket — A Nantucket short-term rental doesn’t get qualified on its July numbers.
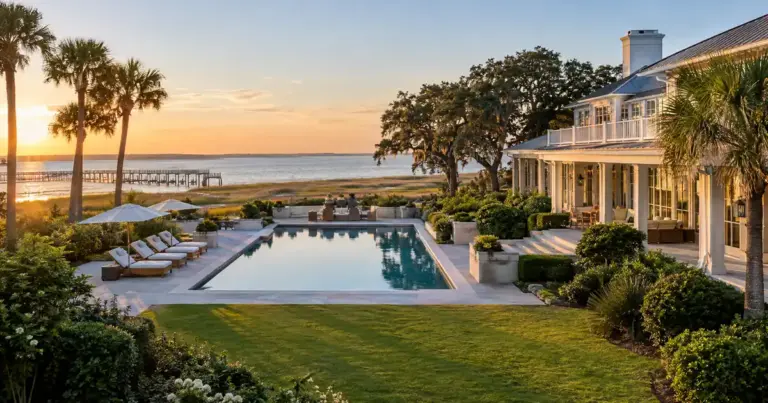
Sea Island and similar luxury coastal markets create a specific underwriting puzzle. The properties earn real money.