Buying A Vacation Home In Breckenridge On Bank Statements
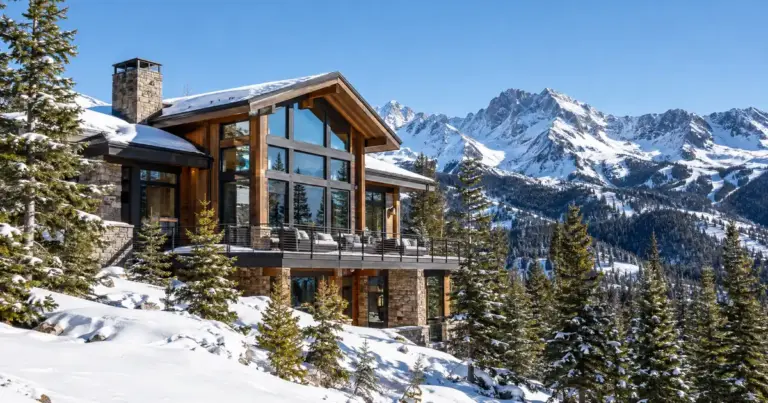
The loan is priced off your own cash flow if it’s a personal-use second home, or off the property’s rental income if it operates as a short-term rental.

 Lendmire Research
The loan is priced off your own cash flow if it’s a personal-use second home, or off the property’s rental income if it operates as a short-term rental.
This approach sits outside agency underwriting and lives in the non-QM space, where terms, haircuts, and divisors vary lender to lender.
For a long-term lease, that means the appraiser’s market-rent opinion.
That figure runs through standard debt-to-income underwriting like any other income source.
In Lendmire’s wholesale network, that ladder runs from $150,000 to $10,000,000, with leverage stepping down as size climbs.
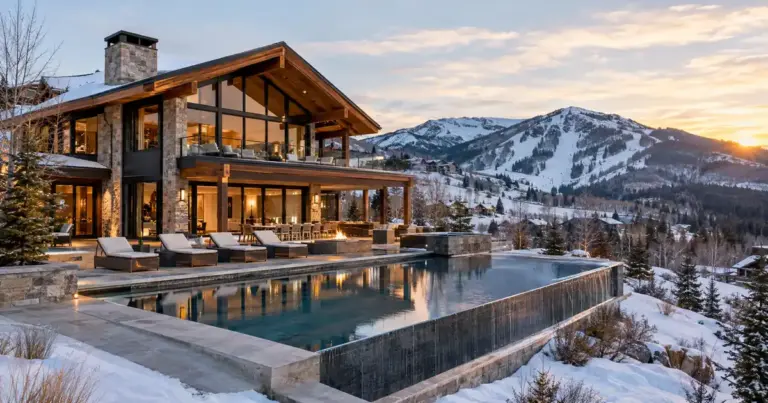
In a ski town where income swings hard between December and July, the coverage math that matters is the twelve-month picture, not the winter snapshot.
Asset Qualifier Mortgages In Aspen: How Retirees Qualify: what borrowers need to know about high-net-worth bank-statement financing, from Lendmire.
Leverage, credit floors, and reserve requirements all tighten together as the loan size climbs.
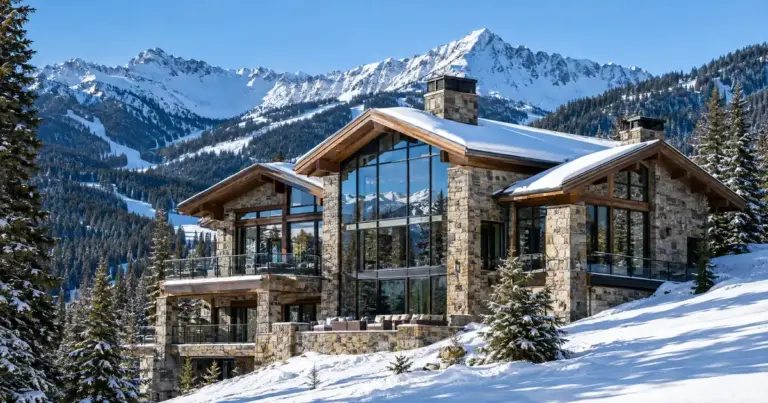
A lender divides eligible assets by a set number of months and treats the result as monthly income, alongside or instead of wages.
The mechanics don’t change because a home happens to sit in an affluent enclave; the loan size and the borrower’s deposit history do all the work.
A lender divides eligible assets by a set number of months to produce a monthly income figure, then underwrites the file like any other mortgage.
A borrower with a large portfolio but modest reported income divides eligible assets by a set number of months to produce qualifying income.
Bank statement loans qualify a second home; DSCR loans do not.
Asset Depletion Loans In Lake Arrowhead: Qualifying On Assets Alone — what borrowers need to know, from Lendmire.