Financing A Second Home In Lake Arrowhead On Bank Statements
Leverage on a second home runs a bit tighter than on a primary residence and steps down as the loan size grows.

 Lendmire Research
Leverage on a second home runs a bit tighter than on a primary residence and steps down as the loan size grows.
That single choice determines the documentation path, the leverage available, and whether rental income can even help you qualify.
A property you’ll use yourself and rent fewer than 14 days a year can qualify as a second home.
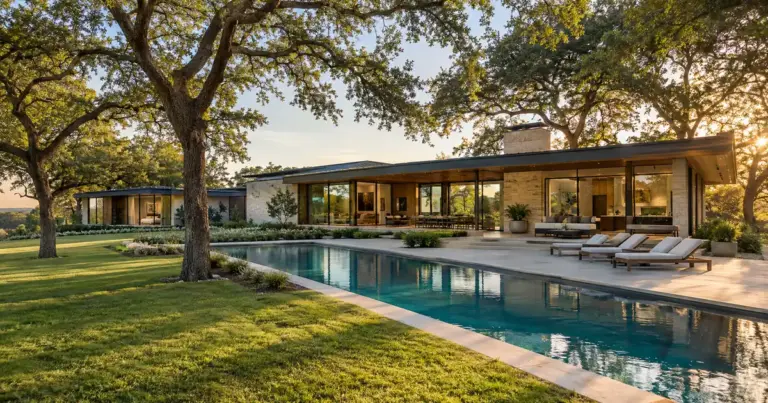
None of what follows depends on where the property sits; the same occupancy test applies whether the second home is in wine country or anywhere else.
Coverage of 1.00 or better earns full leverage; below that, select programs still work but at reduced leverage.
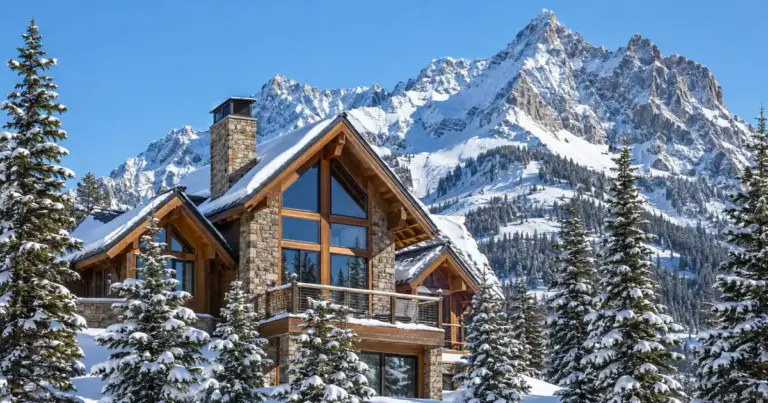
Which lane applies, and how it gets discounted, decides the leverage an investor gets on a mountain-town luxury property.
A ratio at or above 1.00 means the rent covers the payment on paper. 1007 rent schedule: an appraisal form built for long-term lease comps.
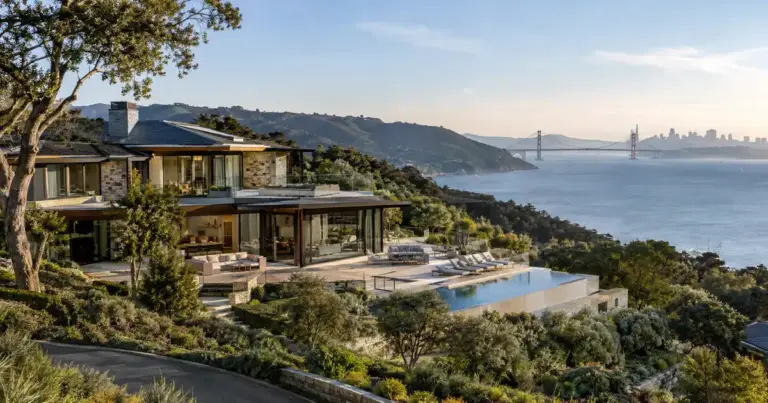
Super Jumbo DSCR Loans In Tiburon — These loans qualify on the rental income the property produces, not the investor’s tax returns.
A lender divides eligible assets by a set number of months, and that result gets treated like monthly income.
Retirees keep showing up as a named driver of this loan category in trade coverage, and for good reason.
It’s a consumer, owner-occupied and second-home tool — not a rental-property financing product.
There is no federal definition of “super jumbo” — each lender in the network sets its own threshold, which is exactly why shopping matters here.
A lender divides eligible balances by a set number of months to produce a monthly income figure, then underwrites the file against that number.
Underwriters take the eligible balance, apply account-specific discounts, and divide the result by a set number of months.
The two products solve different problems, and mixing them up creates real compliance risk.