Can A Converted Rental Qualify For A Jumbo DSCR Loan Right Away?
The appraiser produces a market-rent opinion in place of a lease, and that number drives the coverage ratio the same way a signed lease would.

 Lendmire Research
The appraiser produces a market-rent opinion in place of a lease, and that number drives the coverage ratio the same way a signed lease would.
Retirees navigate the estate appraisal on a jumbo DSCR rental loan by treating it as two separate documents, not one.
Most programs apply a haircut — a discount that reflects taxes, early-withdrawal penalties, and limited access to the money.
Can A Converted Rental Anchor A DSCR Portfolio Or Blanket Loan: what investors need to know about large-balance DSCR financing, from Lendmire.
Above a certain loan size, a second valuation product often gets layered on, and the lower number — never an average — controls how much gets financed.
The borrower does not need to withdraw or liquidate the account — the statement itself does the work. That’s the short version.
Can A Former Home Qualify As A DSCR Rental Right Away: what investors need to know about large-balance DSCR financing, from Lendmire.
A second appraisal or desk review usually shows up because of loan size or a flip-sale pattern, not because your income documentation is unconventional.
On a rental property, the payout history usually shows up only as proof of reserves — the property’s own rent carries the loan.
The appraisal runs on a separate track from income documentation — a clean asset file does not shortcut collateral review.
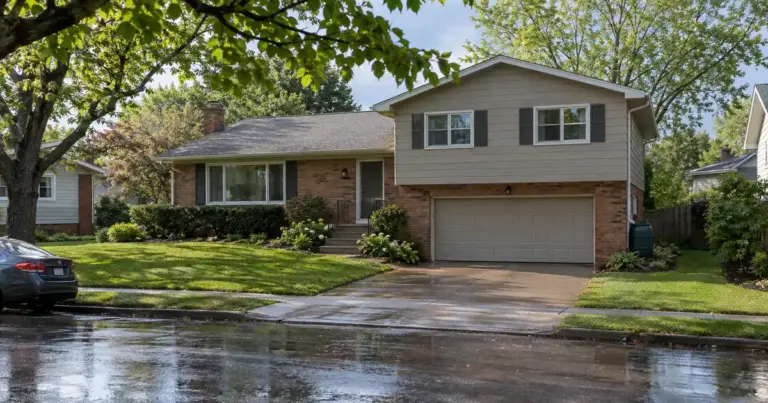
Converted Rental Qualify For A DSCR Loan Right — Yes, in most cases.
Can A Business Under Two Years Old Qualify For A P&L Loan?
A DSCR loan then qualifies the property on that rent, not on the borrower’s tax returns.
Yes, an IRA or 401(k) can cover reserves on a super jumbo bank statement loan, but not at full value.
Most programs still default to 24 months of self-employment as the baseline.