Blanket DSCR Loans In Rhode Island: How Multi-property Investors Qualify
Rhode Island’s dense stock of two-, three-, and four-family homes makes this structure a natural fit for investors scaling past a handful of doors.

 Lendmire Research
Rhode Island’s dense stock of two-, three-, and four-family homes makes this structure a natural fit for investors scaling past a handful of doors.
The rules on which assets count, how much they’re discounted, and what divisor gets applied vary widely by lender.
Great Falls doesn’t change any of this. No jurisdiction does.
Luxury Rental DSCR Loans in The Woodlands — Underwriters do not simply take a nightly Airbnb rate and multiply it by 30.
Get the income method right first — the loan size follows from there.
Nothing here is a promise of approval. Every file is underwritten individually, subject to lender guidelines, credit, reserves, and property review.
Seasonal income gets discounted and stress-tested before it counts.
The correct tool for a business owner is usually a bank statement loan, sized off business cash flow instead of tax returns.
A lender divides eligible assets by a set number of months to create a monthly qualifying-income figure.
A lender totals eligible accounts, applies discounts to volatile holdings, and divides the result by a set number of months.
The catch here is what “rent” can legally mean.
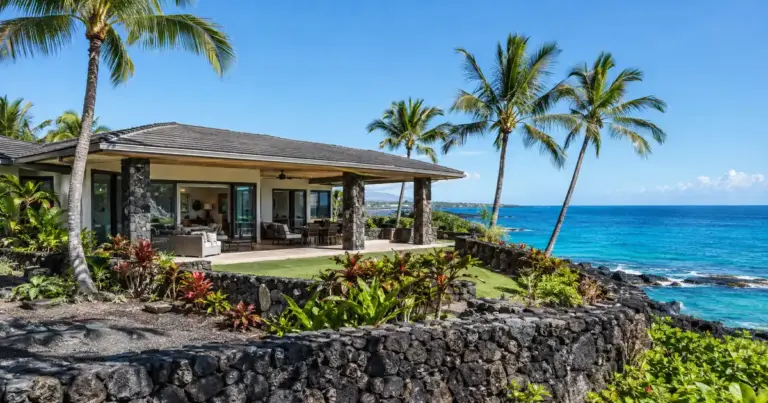
Asset Depletion Loans In Kailua-kona — These loans let a borrower qualify using liquid assets instead of a paycheck.
Asset Depletion Loans in Isle of Palms — These loans let a borrower qualify with liquid assets instead of a paycheck.
– Asset depletion converts eligible liquid assets into a hypothetical monthly income stream, added to (or replacing) documented income.
Underwriters lean on annualized income and build in reserve cushions for the slow months.