HELOC On An Investment Property
The property, the title, and the state all carry their own rules that determine whether a line is even an option.

 Lendmire Research
The property, the title, and the state all carry their own rules that determine whether a line is even an option.
Across the wholesale network Lendmire works with, leverage typically runs 85% to 93% of project cost, always capped at 75% of ARV.
Investors whose rentals are titled in an LLC hit a title wall, not a documentation wall, and typically pivot to a DSCR-based cash-out refinance instead.
Instead, they qualify the file on credit history, home equity, and debt-to-income using an interest-only payment estimate.
Using Home Equity To Invest In Stocks A Good Idea — For most people, no.
Both are business-purpose loans, which changes how they’re reviewed, priced, and documented compared to an owner-occupied mortgage.
Investment-property HELOCs exist, but they carry lower leverage, higher credit floors, and far fewer available lenders than a HELOC on a primary home.
Big banks, credit unions, and community banks typically sit in the first camp, capped by how many financed properties a borrower can carry.
Most sponsors who pool money from more than a few people rely on a Regulation D exemption, usually Rule 506(b) or 506(c).
– The lenders most likely to say yes are credit unions, portfolio lenders, and non-QM wholesale shops.
Using Home Equity To Invest — Homeowners tap built-up equity through a home equity line of credit, a home equity loan, or a cash-out
– “First-lien” or “first-position” describes where the loan sits on title — it isn’t a named program you shop by brand.
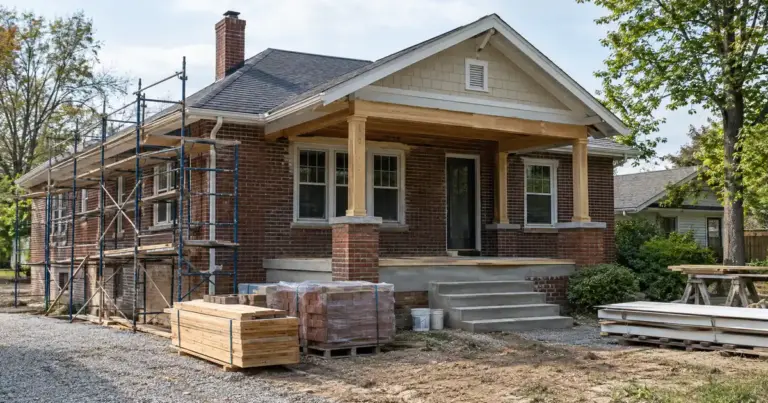
The lender sizes it on the deal (purchase price, rehab budget, and finished value), not on your paycheck.