How To Qualify For A Mortgage Self Employed
Which path fits depends on how long you’ve been self-employed, how your business is structured, and whether the property is a home or an investment.

 Lendmire Research
Which path fits depends on how long you’ve been self-employed, how your business is structured, and whether the property is a home or an investment.
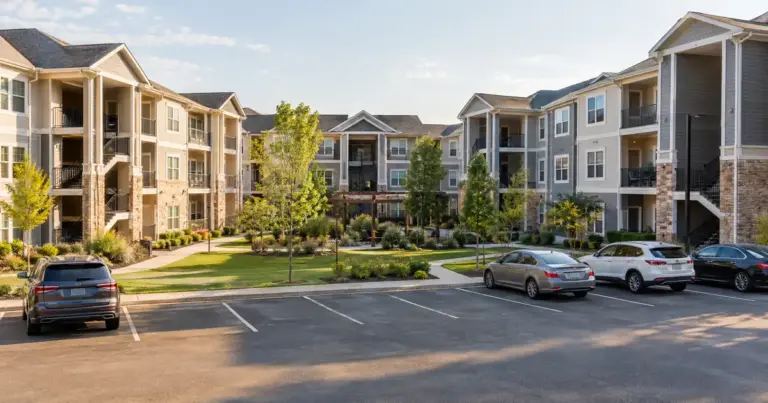
Apartment investment property refinance finance explained: unit-count lanes, cash-out limits, and DSCR coverage math, with Lendmire.
National data backs up why this product is getting more attention right now.
Personal statements are usually counted close to dollar-for-dollar, while business statements get a percentage haircut to strip out overhead.
– Refinance points and lender fees are amortized straight-line over the loan term — not deducted the year they’re paid.
It’s not complicated once you see the mechanics. It’s just not intuitive, and almost nobody explains it in plain terms before the refinance happens.
It comes in two structural flavors — a lump-sum second lien or a revolving line of credit — and it still runs through full credit, title, and equity review.
80 DSCR Refinance — The Quick Read: On a DSCR purchase, 80% LTV is a realistic leverage tier for many borrowers.
For rental property held in an LLC, or for leverage needs above the network’s equity-line ceilings, the practical path shifts to a DSCR loan instead.
For rentals held in an entity, or deals that need more leverage than that, a DSCR cash-out refinance is usually the better-fitting tool.
How Do Financial Institutions Verify Income for Stated Income HELOCs?
Full-documentation underwriting reads two years of tax returns and qualifies off net income after deductions.
How Many Years Do You Have To Be Self Employed To Get A Mortgage — The Quick Read: There’s no fixed number written into any law.